August 2026 Core-Cast Post-PCE

Month-over-month core PCE came in at +25bps (vs 28bps nowcast) while the year-over-year core PCE reading came in at 3.01% (vs 3.14% nowcast). While headlines noted that today's reading were a downside miss, the month-over-month core PCE reading was only 1 basis point away from rounding up to the consensus estimate of 0.3%.
Error bands were high going into today's PCE release due to the annual benchmark revisions and the three methodological changes for the portfolio management and investment advice, computer software and accessories, and legal services.
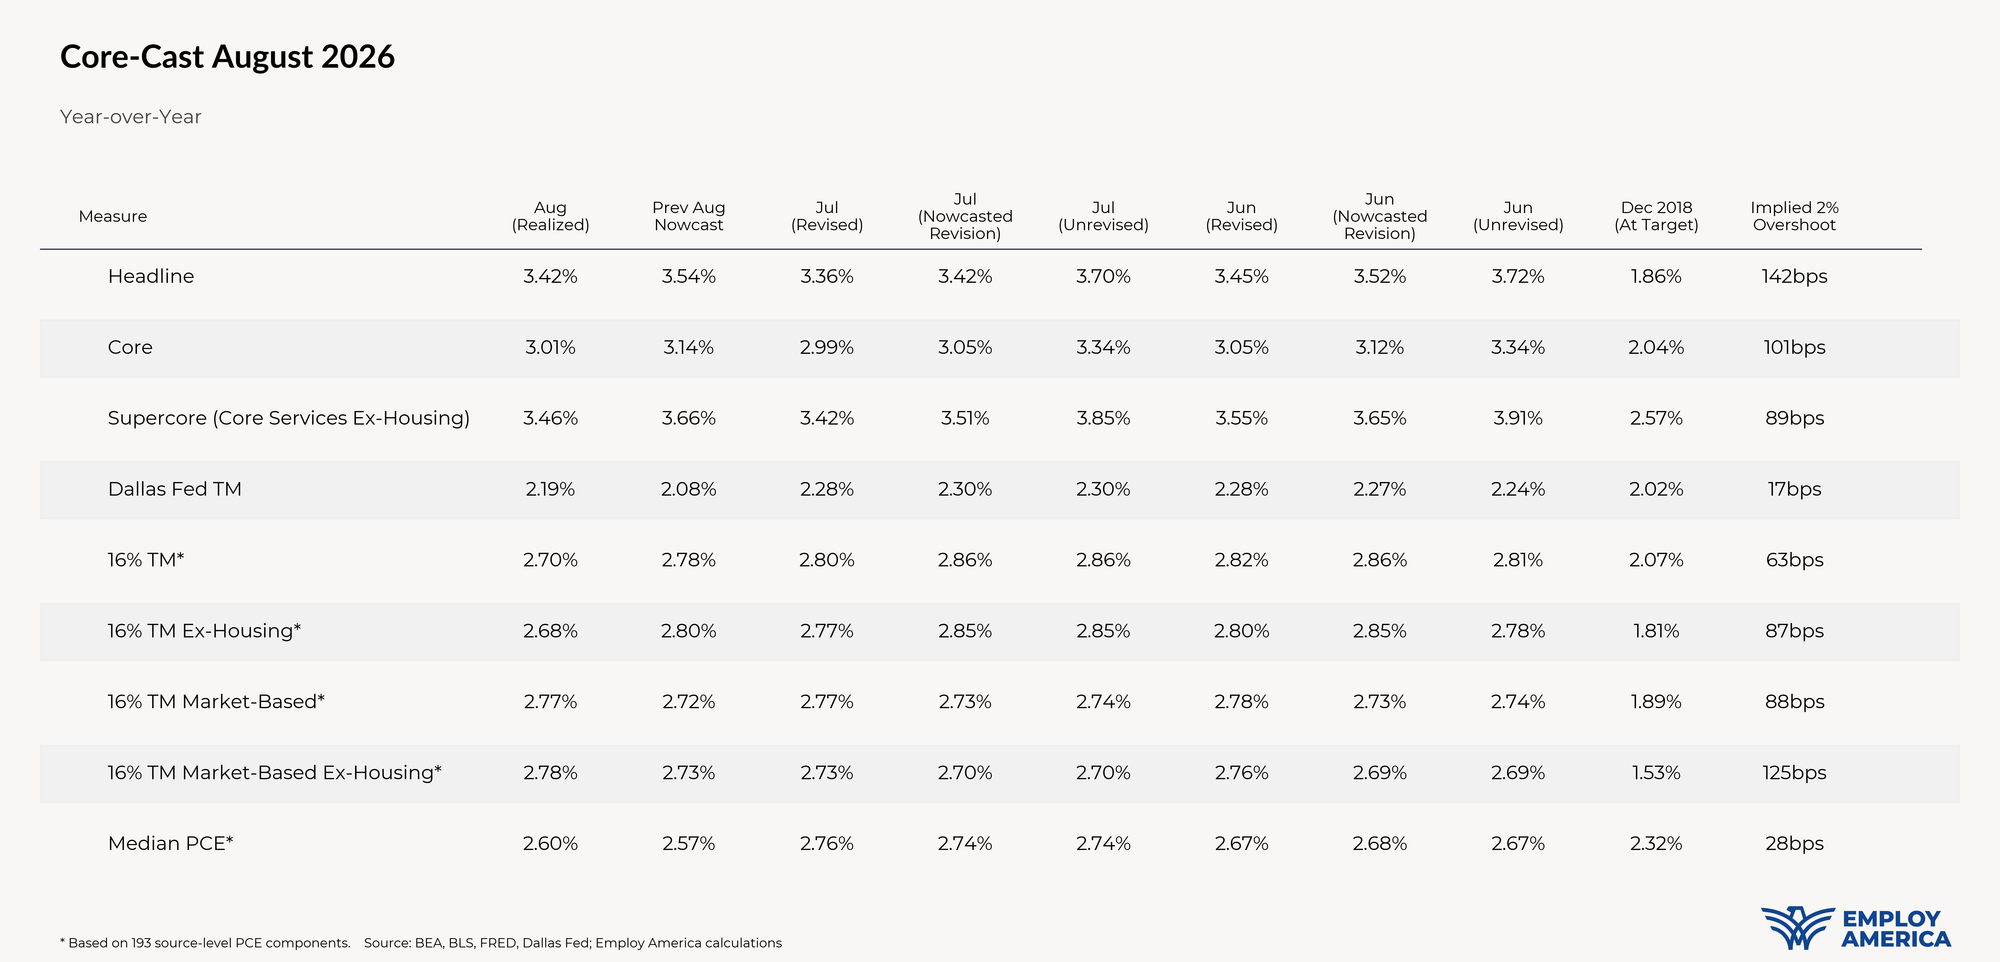
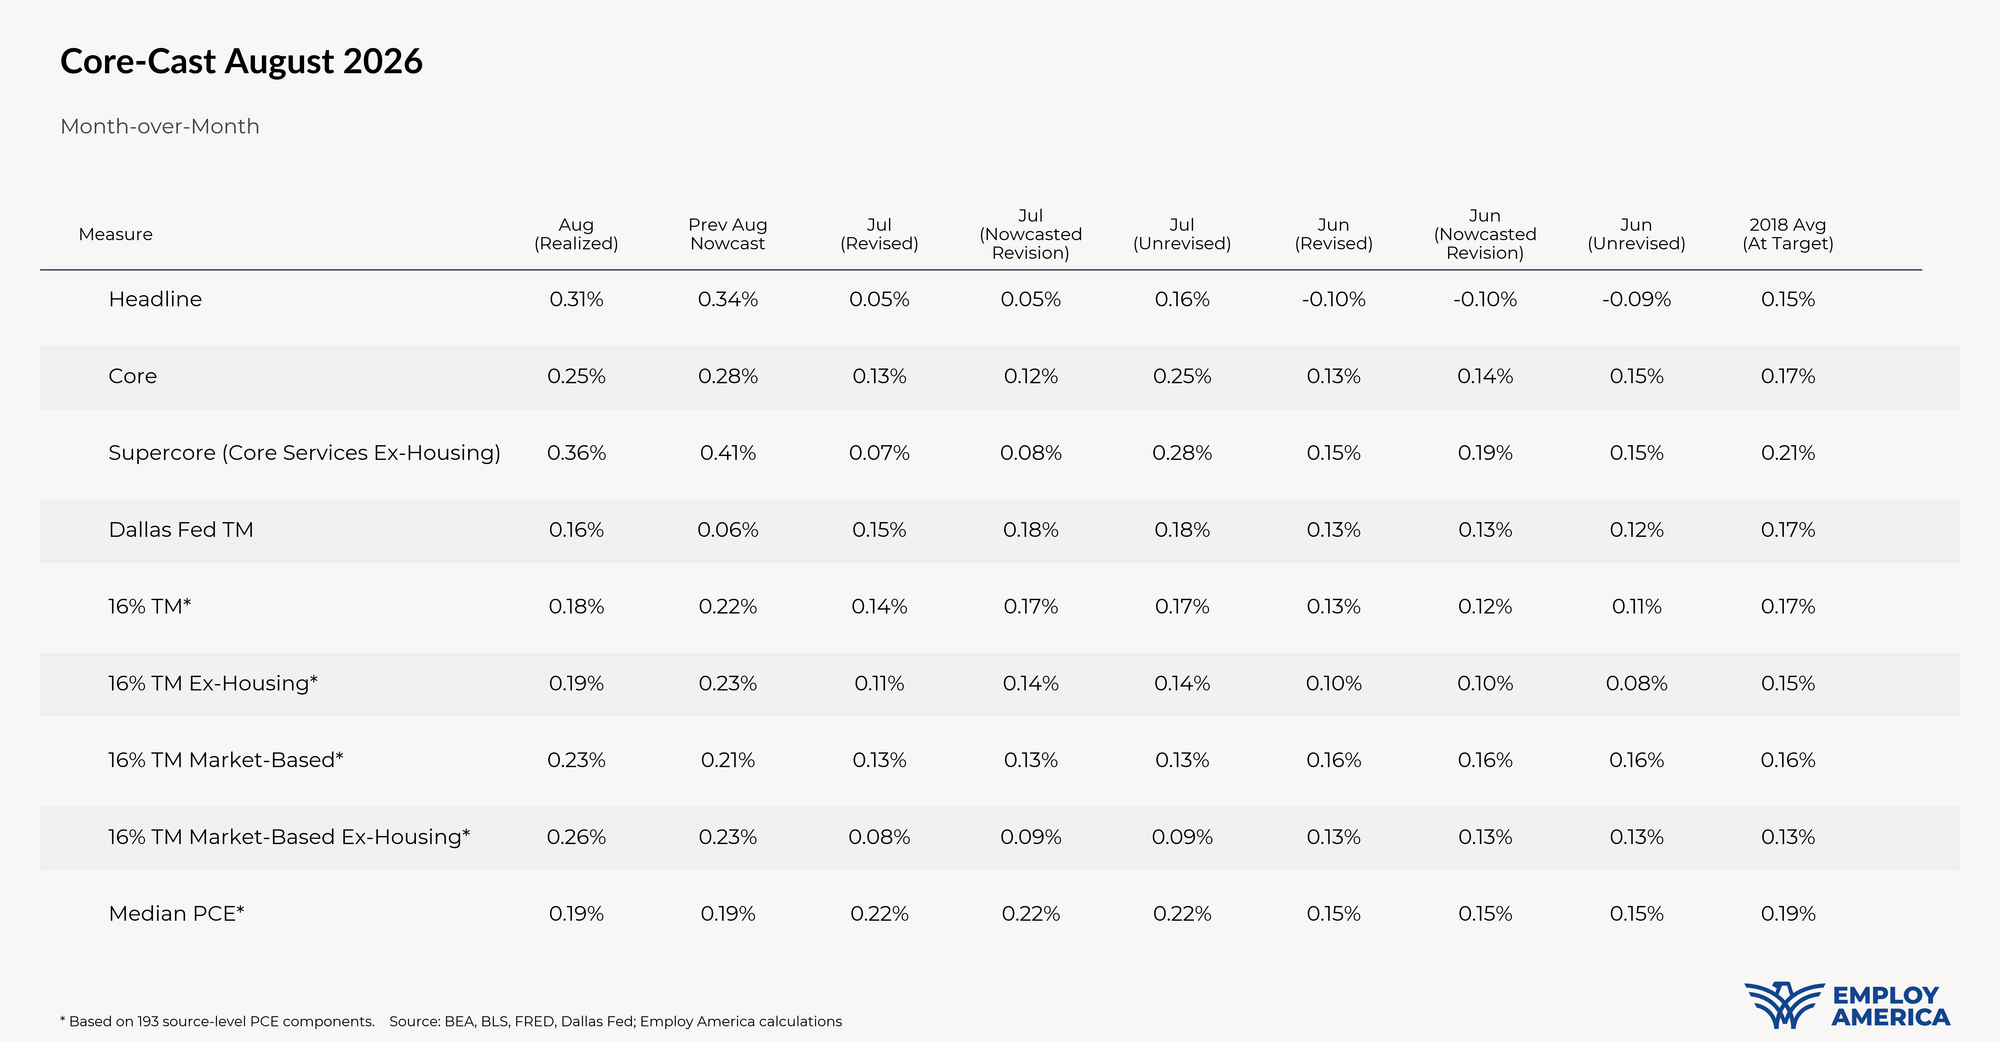
There was a lot of uncertainty on the details of the methodological changes for portfolio management and investment advice, computer software and accessories, and legal services. All things considered, our estimates for portfolio management and software were close – especially for the m/m readings; our miss on legal services was sizable for the category itself, though worth less than 1bp on core PCE. Now that we have more clarity on the methodology details and with the benchmark revisions behind us, we are confident that our nowcasts for these three categories will be considerably more accurate going forward.
Month-over-Month
Year-over-Year
There has been a great deal of focus on the 3-month annualized rate of core PCE inflation, with Governor Waller and others heavily indexing their reaction functions to the measure. The 3m annualized rate is currently running at 2%, though that figure leans on very soft June and July readings. June rotates out of the measure with the September data, and September CPI and PPI will be in hand ahead of the October FOMC meeting. The 3m annualized rate is a noisy gauge of underlying inflation, since a single month can swing it in either direction. For context, here is how the September reading (assuming no revisions to July and August) would move the measure: 5bps → 1.73%; 10bps → 1.94%; 15bps → 2.14%; 20bps → 2.34%; 25bps → 2.55%; 30bps → 2.75%; 35bps → 2.96%; 40bps → 3.16%.
Fedspeak since the September FOMC has been quite hawkish, but NY Fed President John Williams's dovish speech yesterday and today's small downside surprise in August core PCE have moved October pricing to a coinflip. We see upside risk in the September data from (1) airfares, (2) food services, (3) wireless communication services, and (4) tech equipment and, (5) other core goods categories. MacroSuite subscribers will receive our September inflation preview next week with greater detail. Once again, data-point dependence will determine whether the Fed hikes in October.

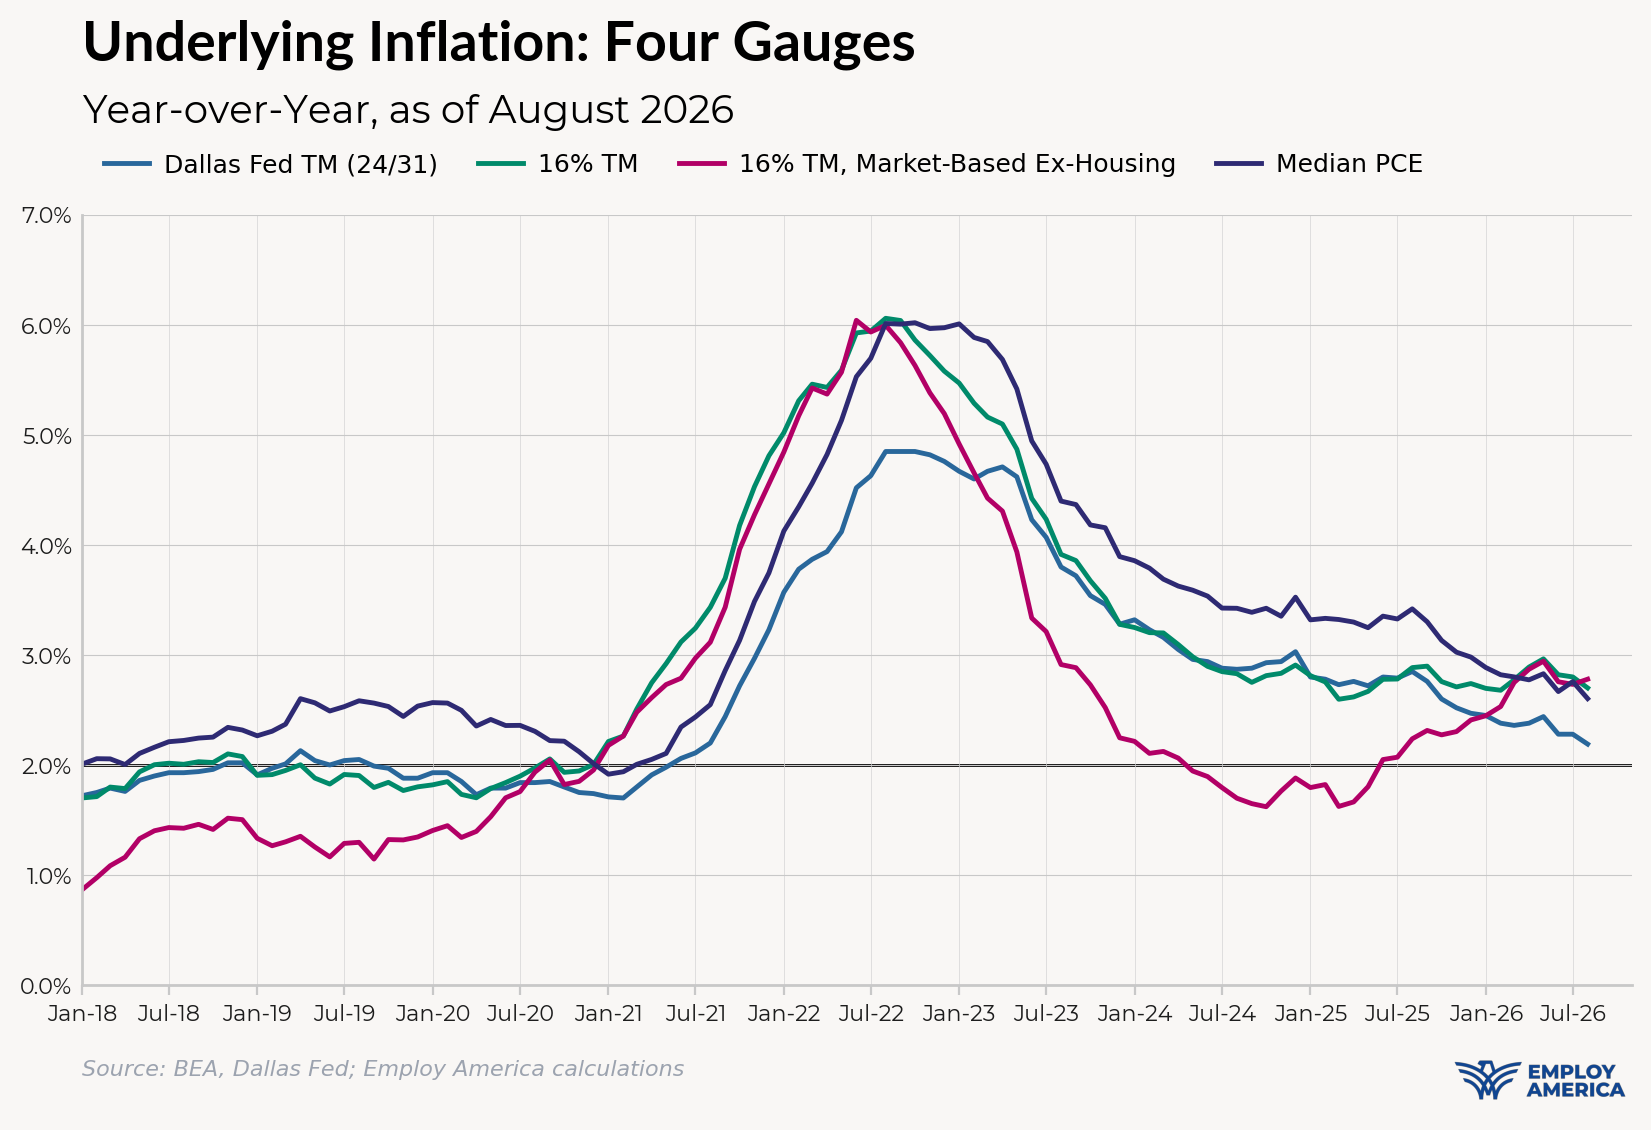
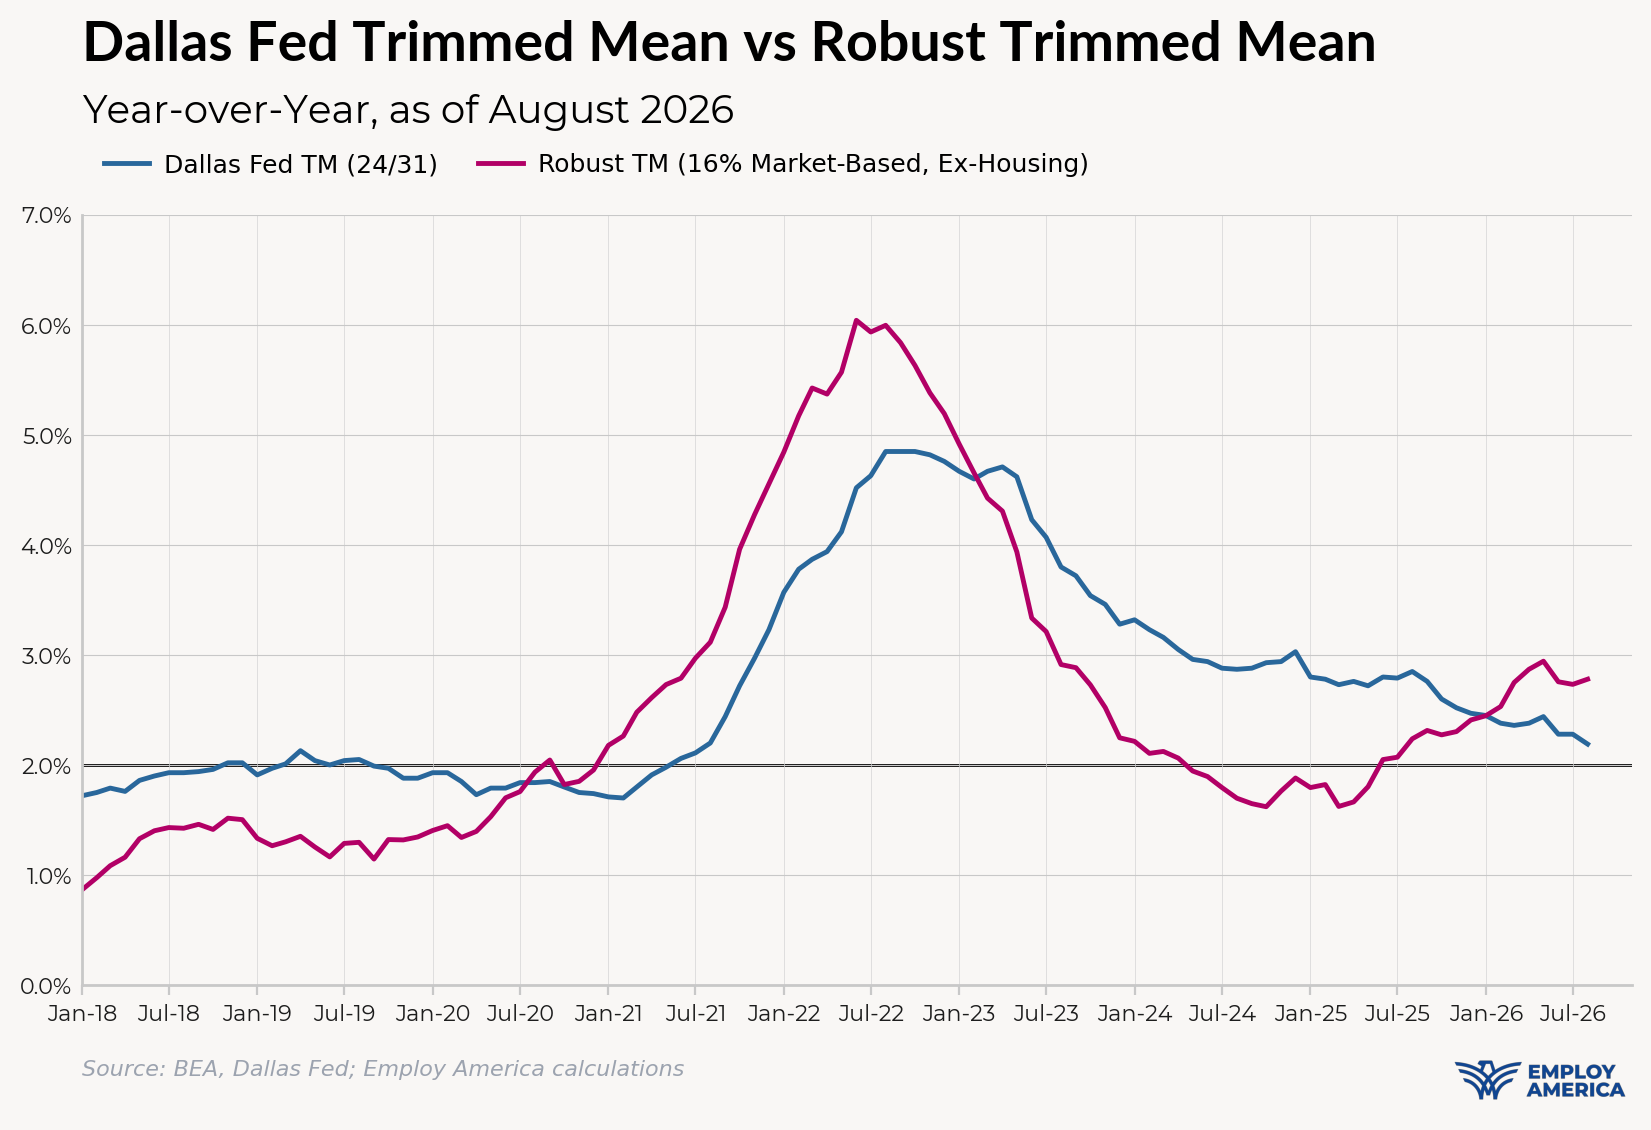

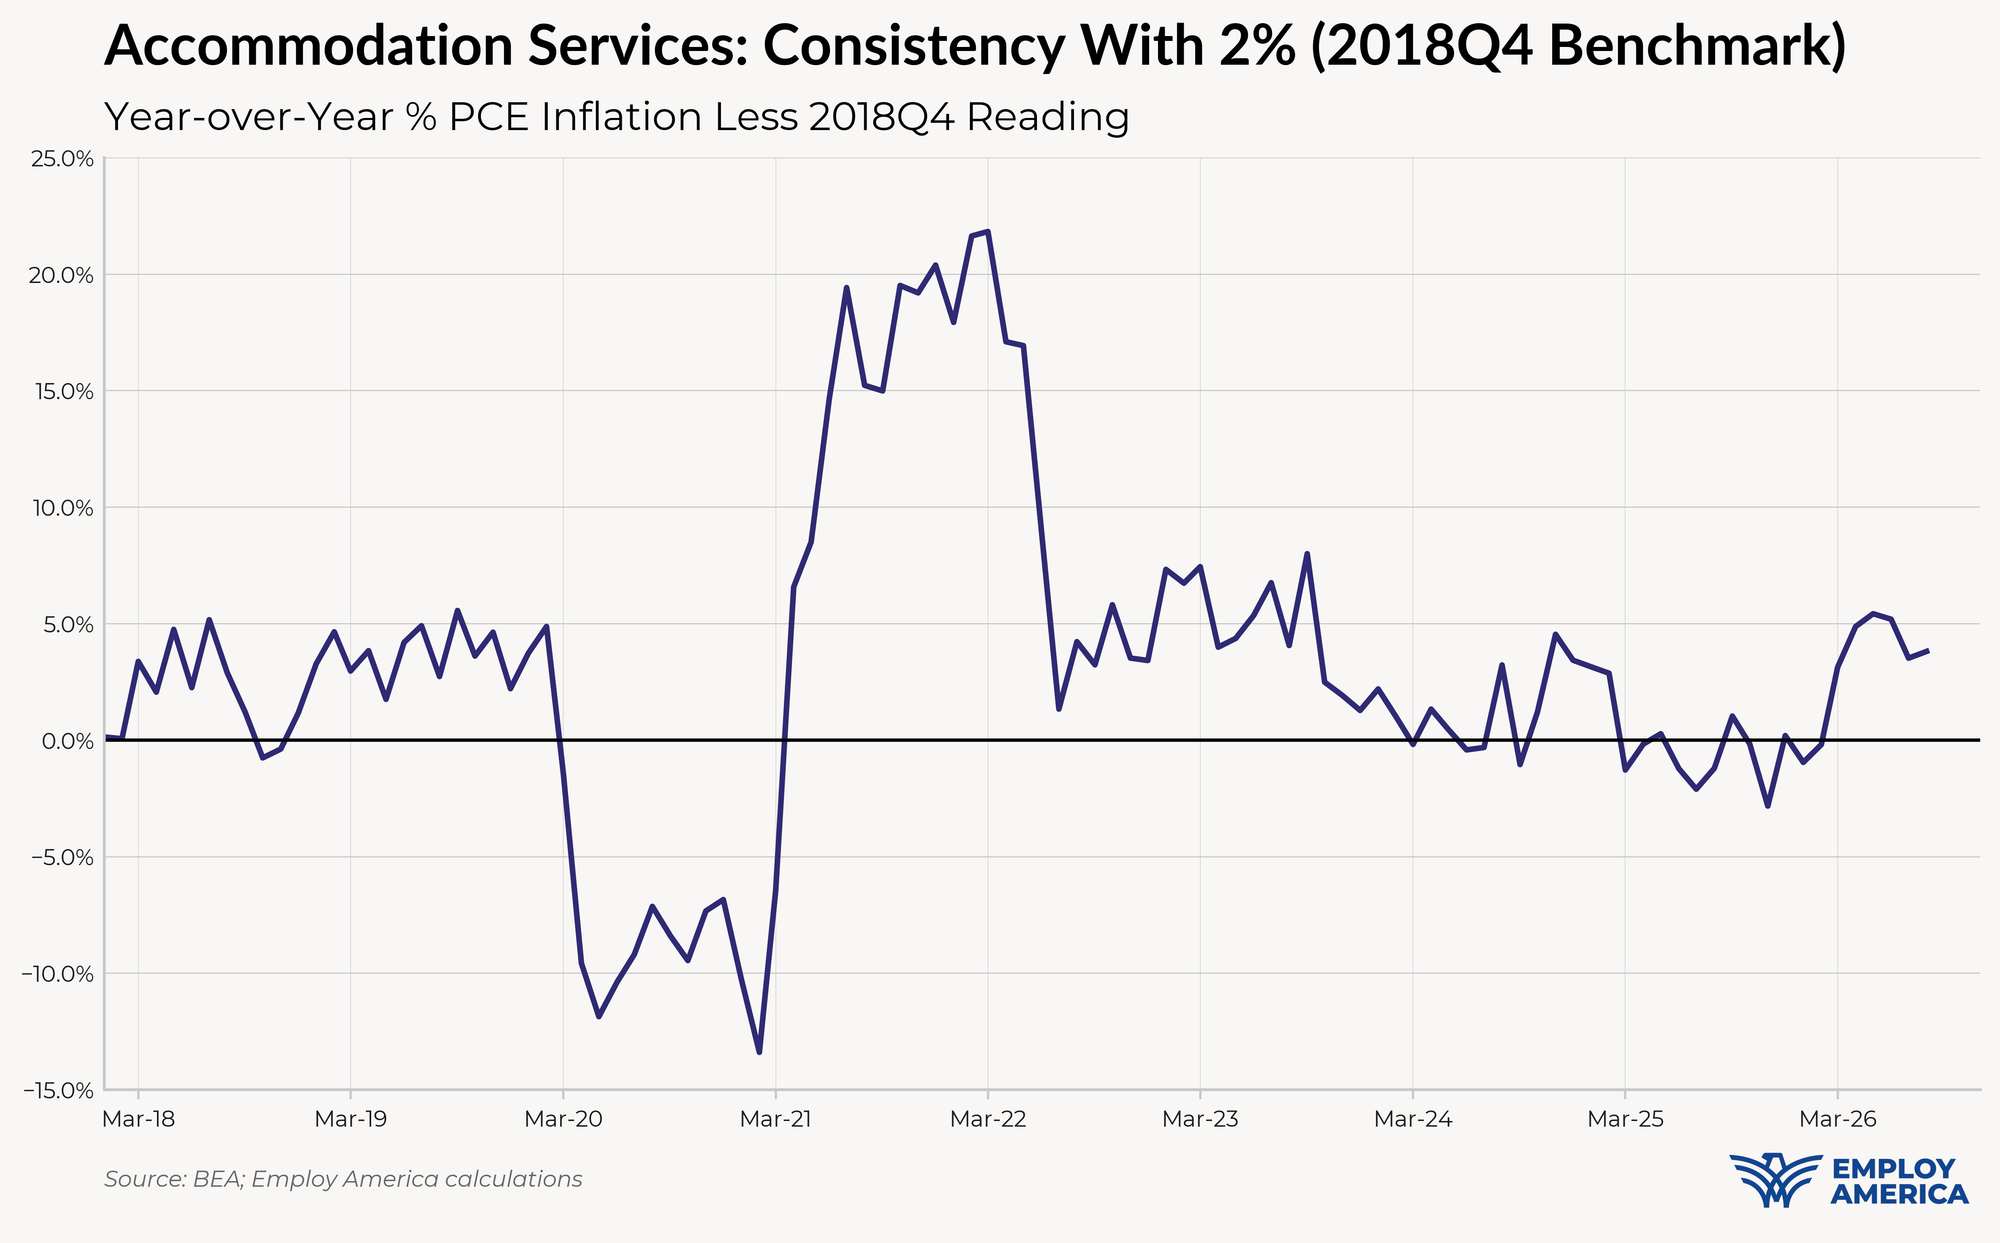
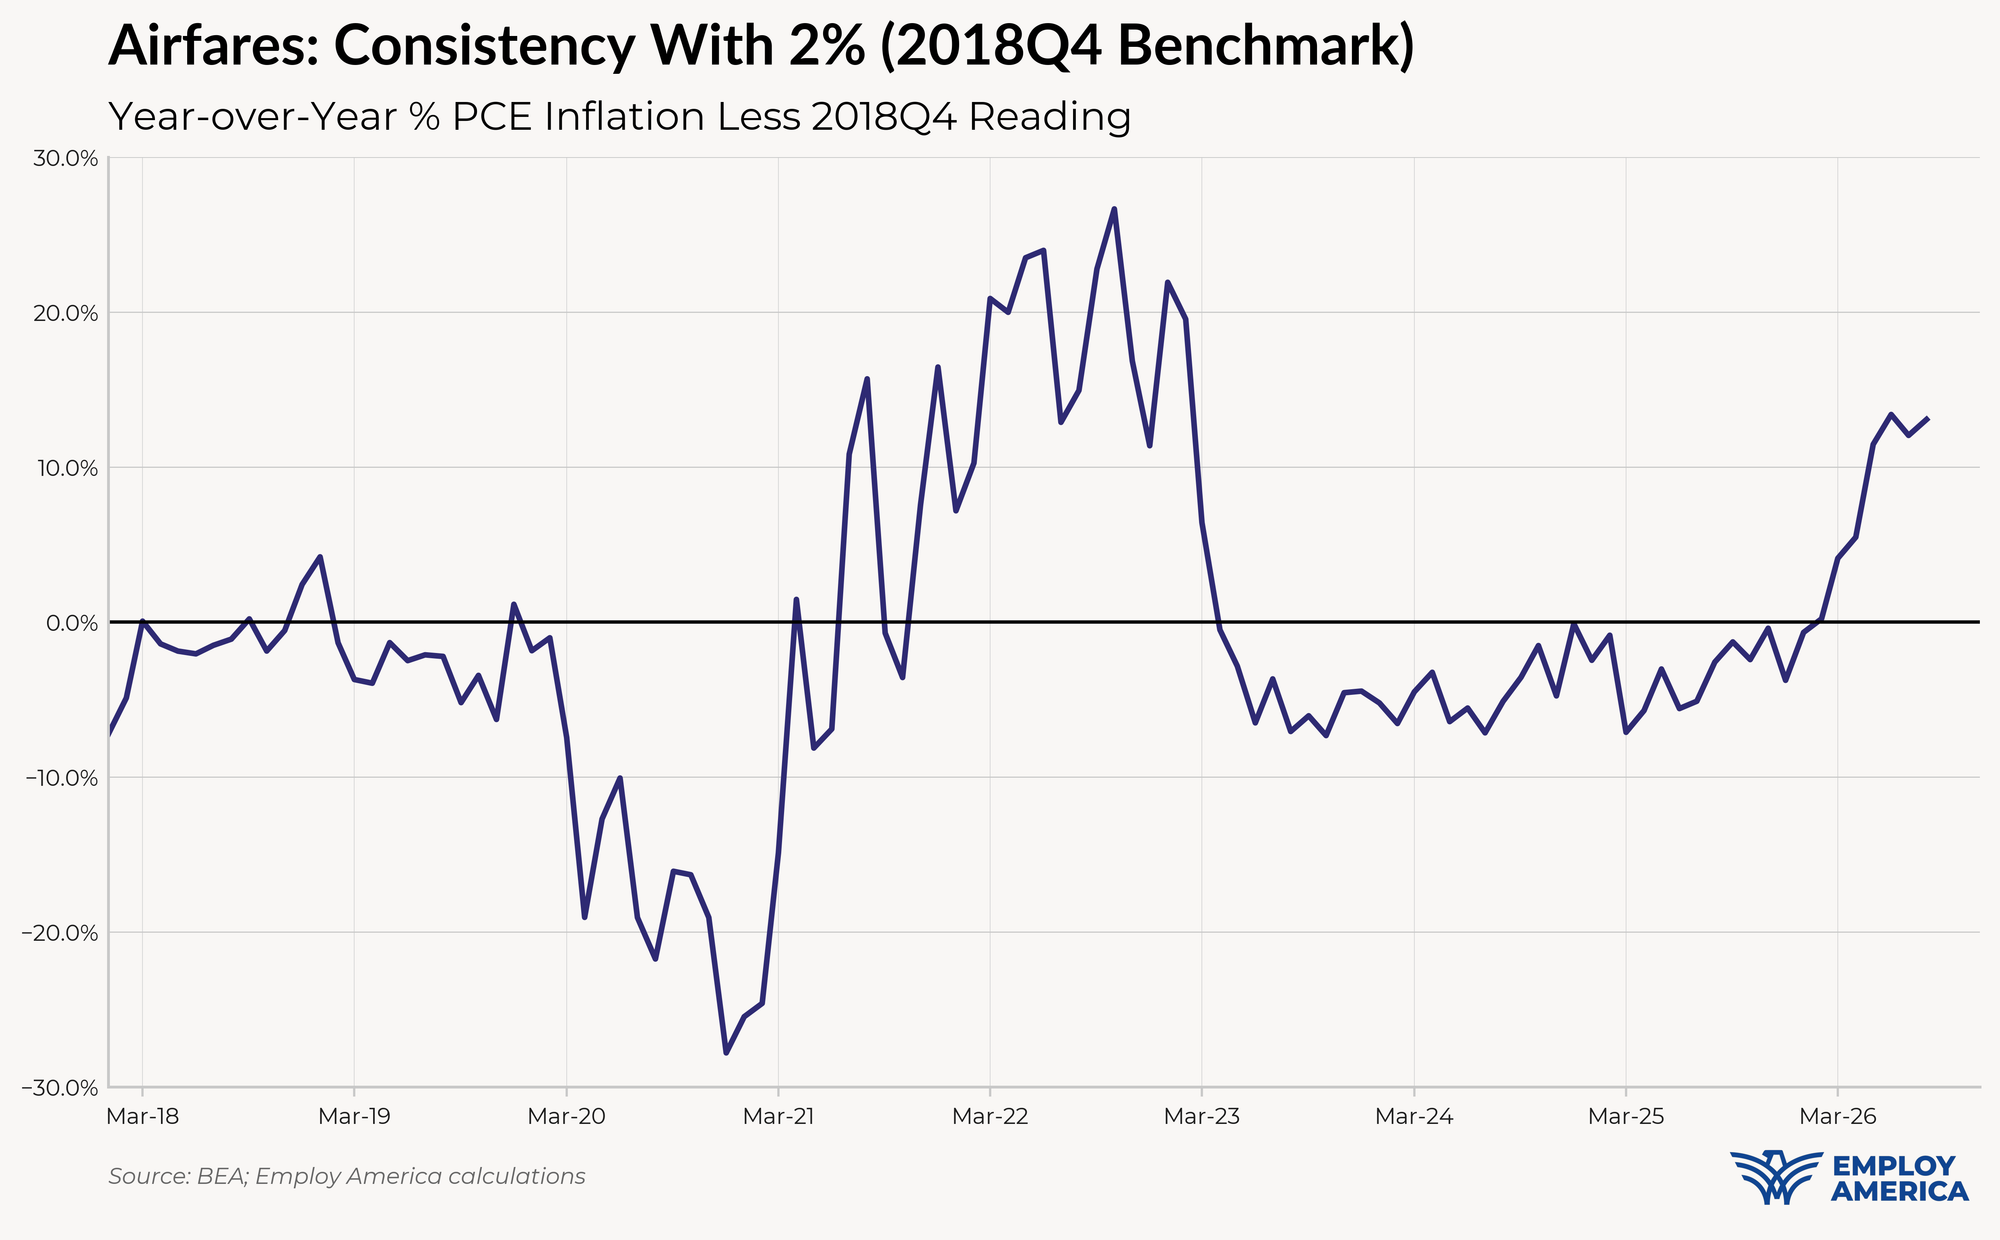
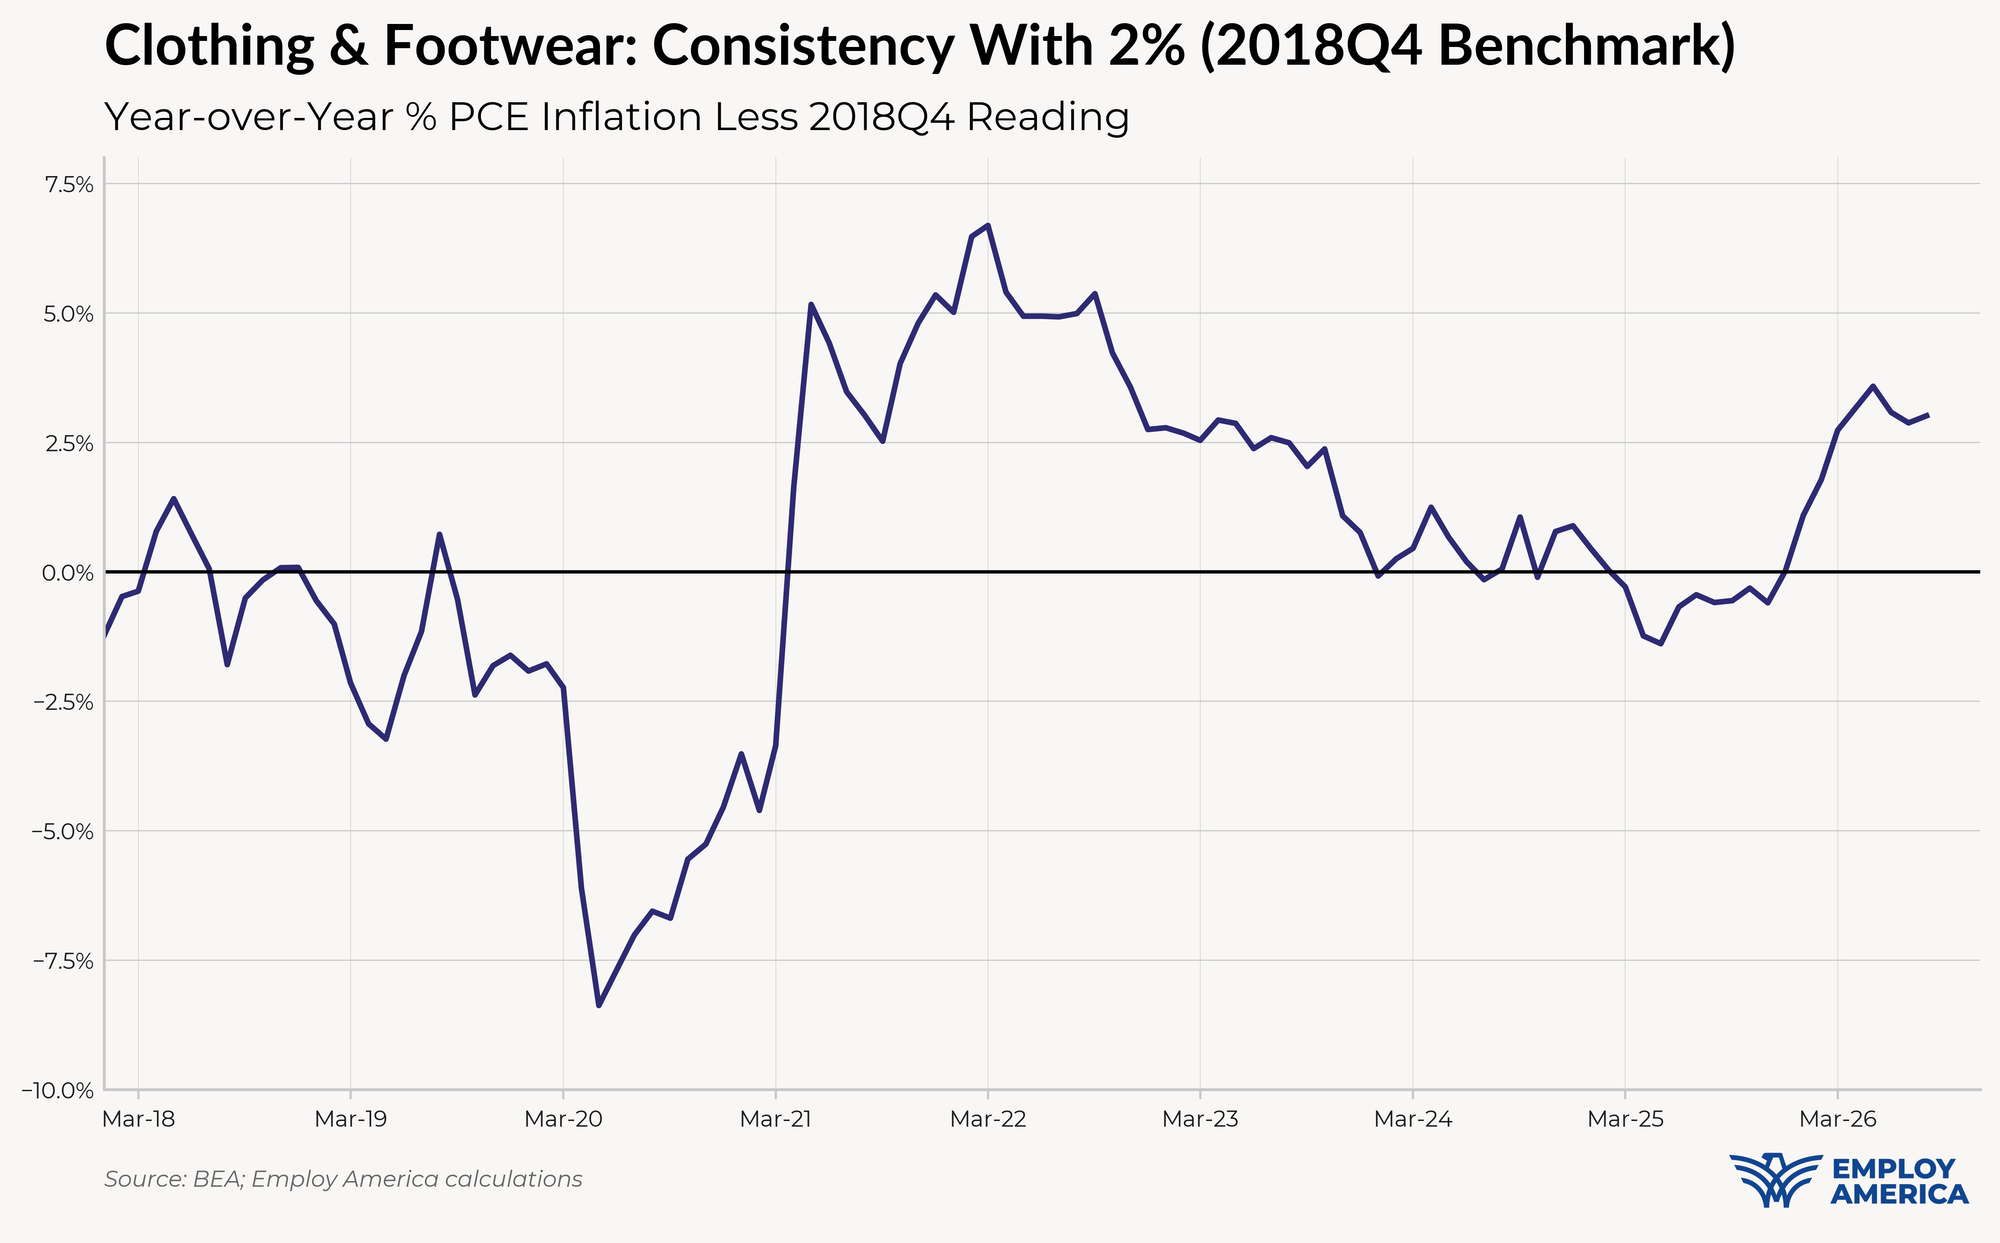
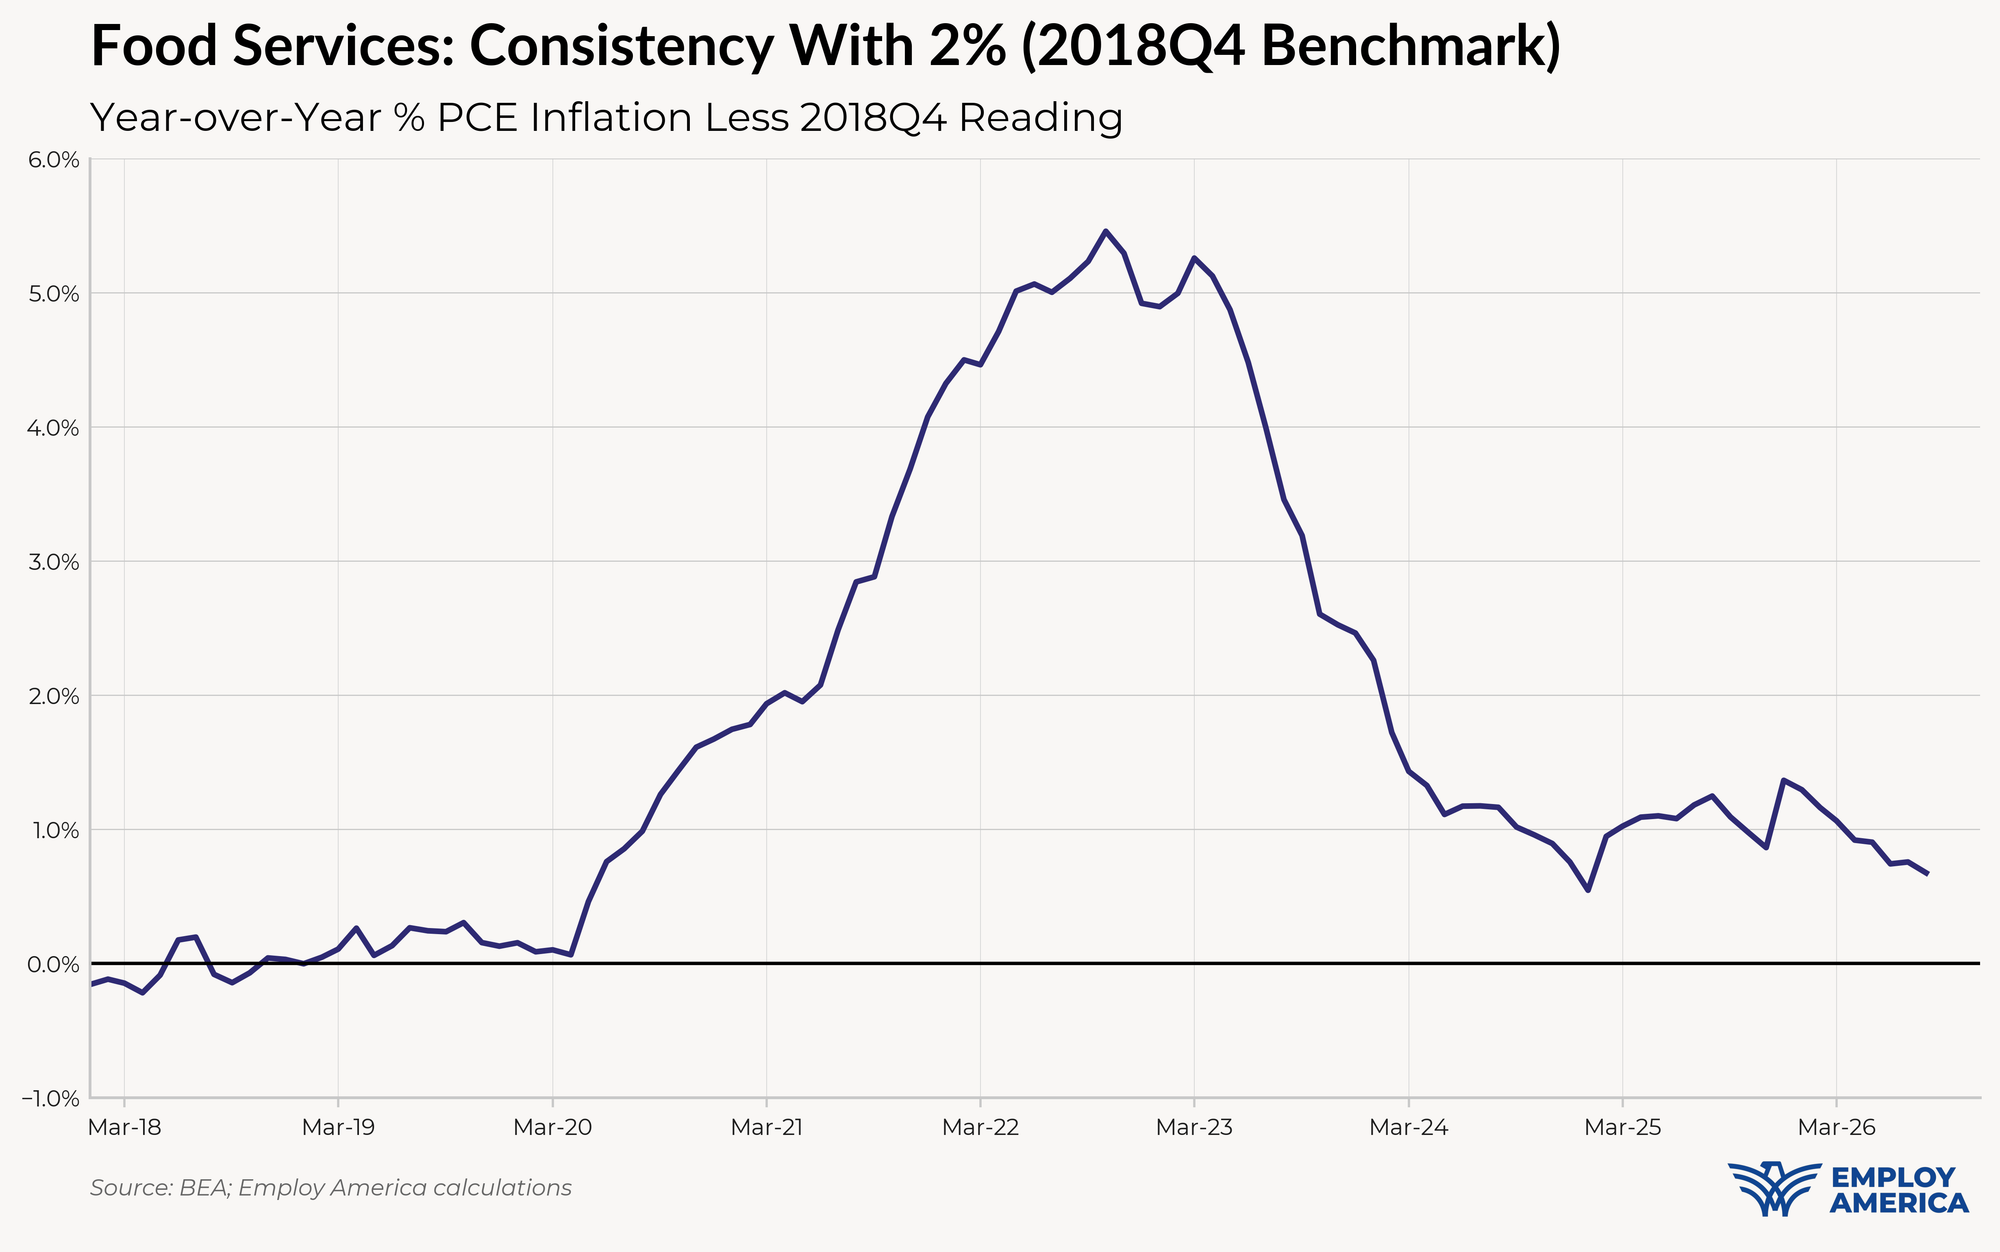
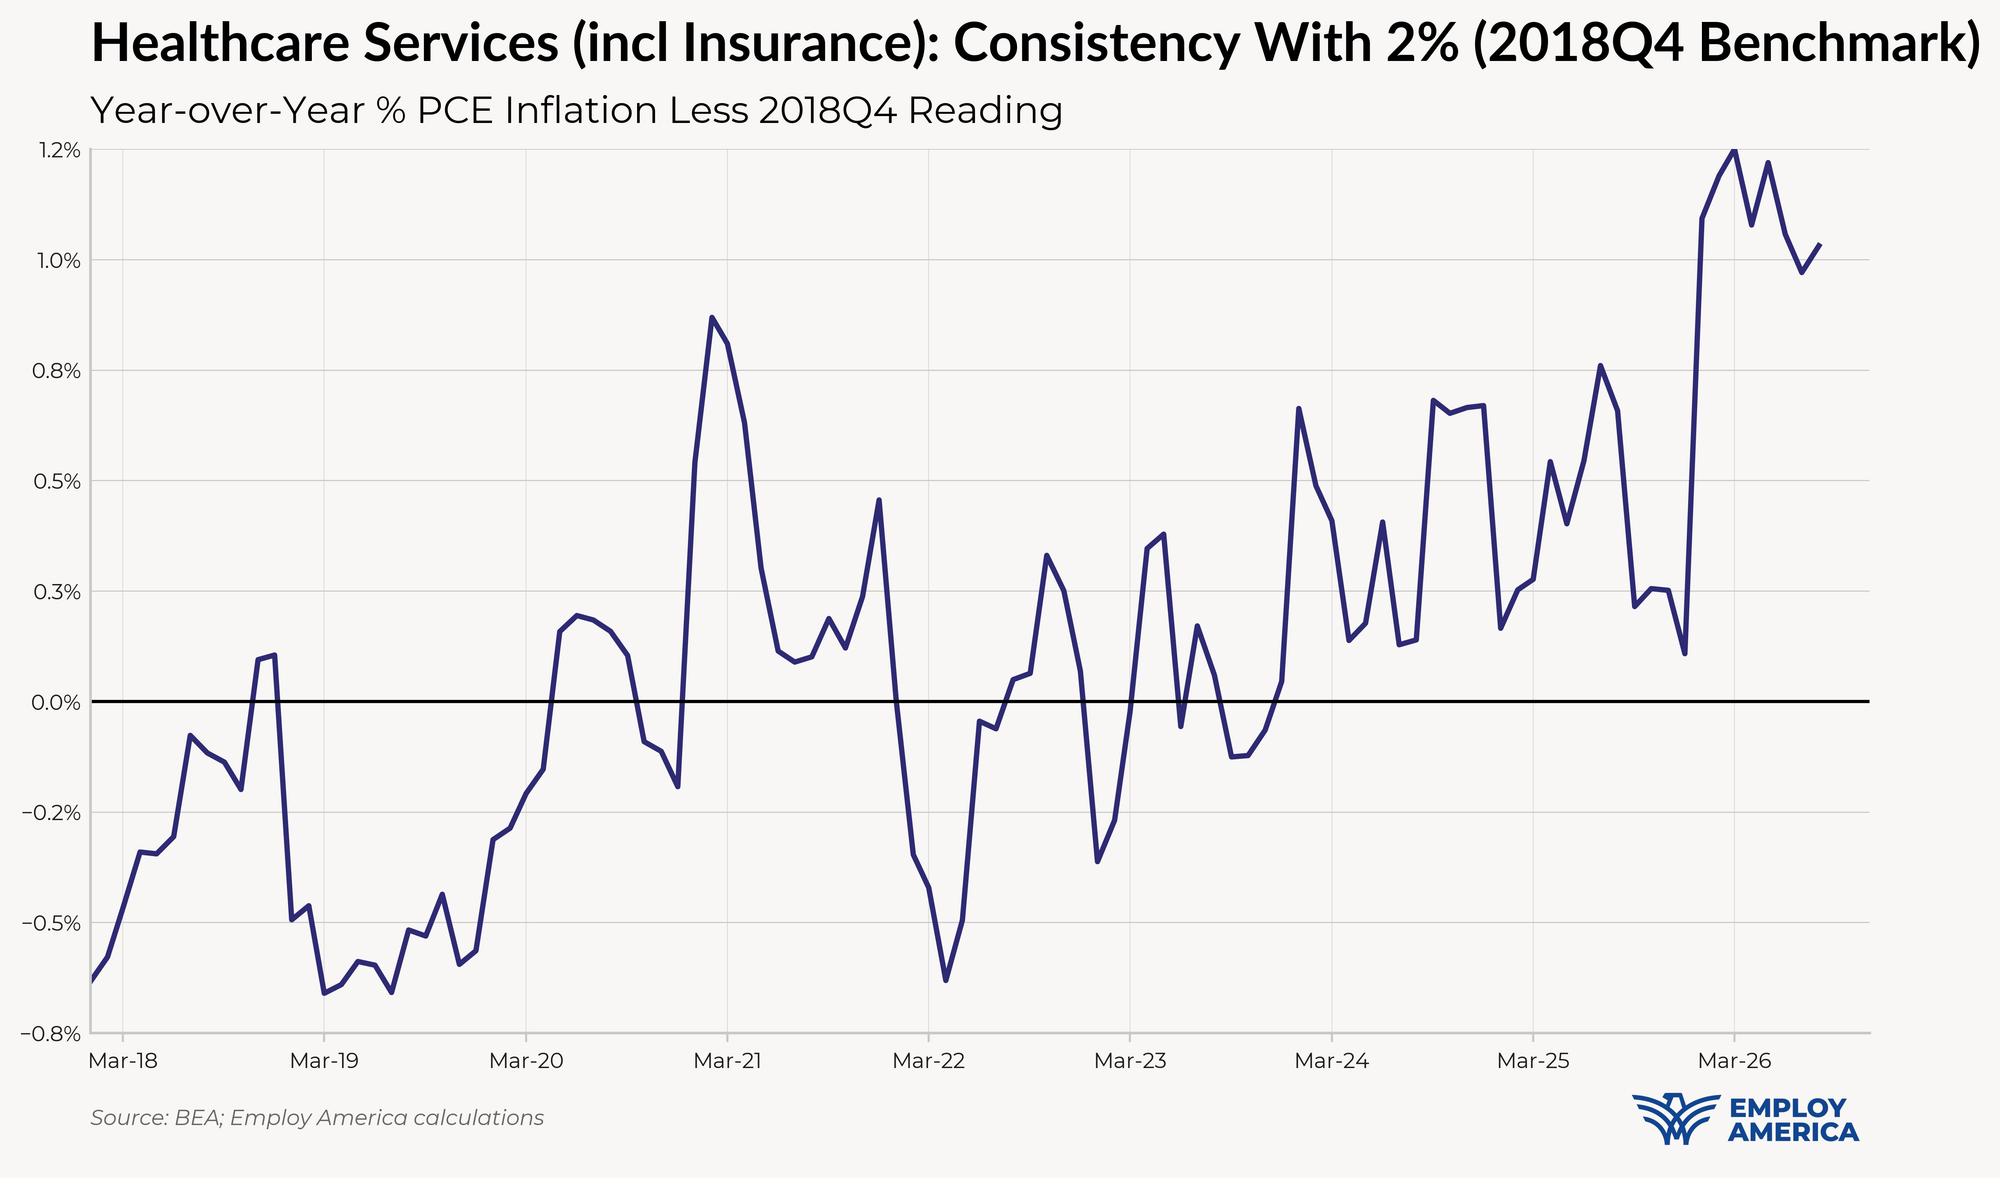
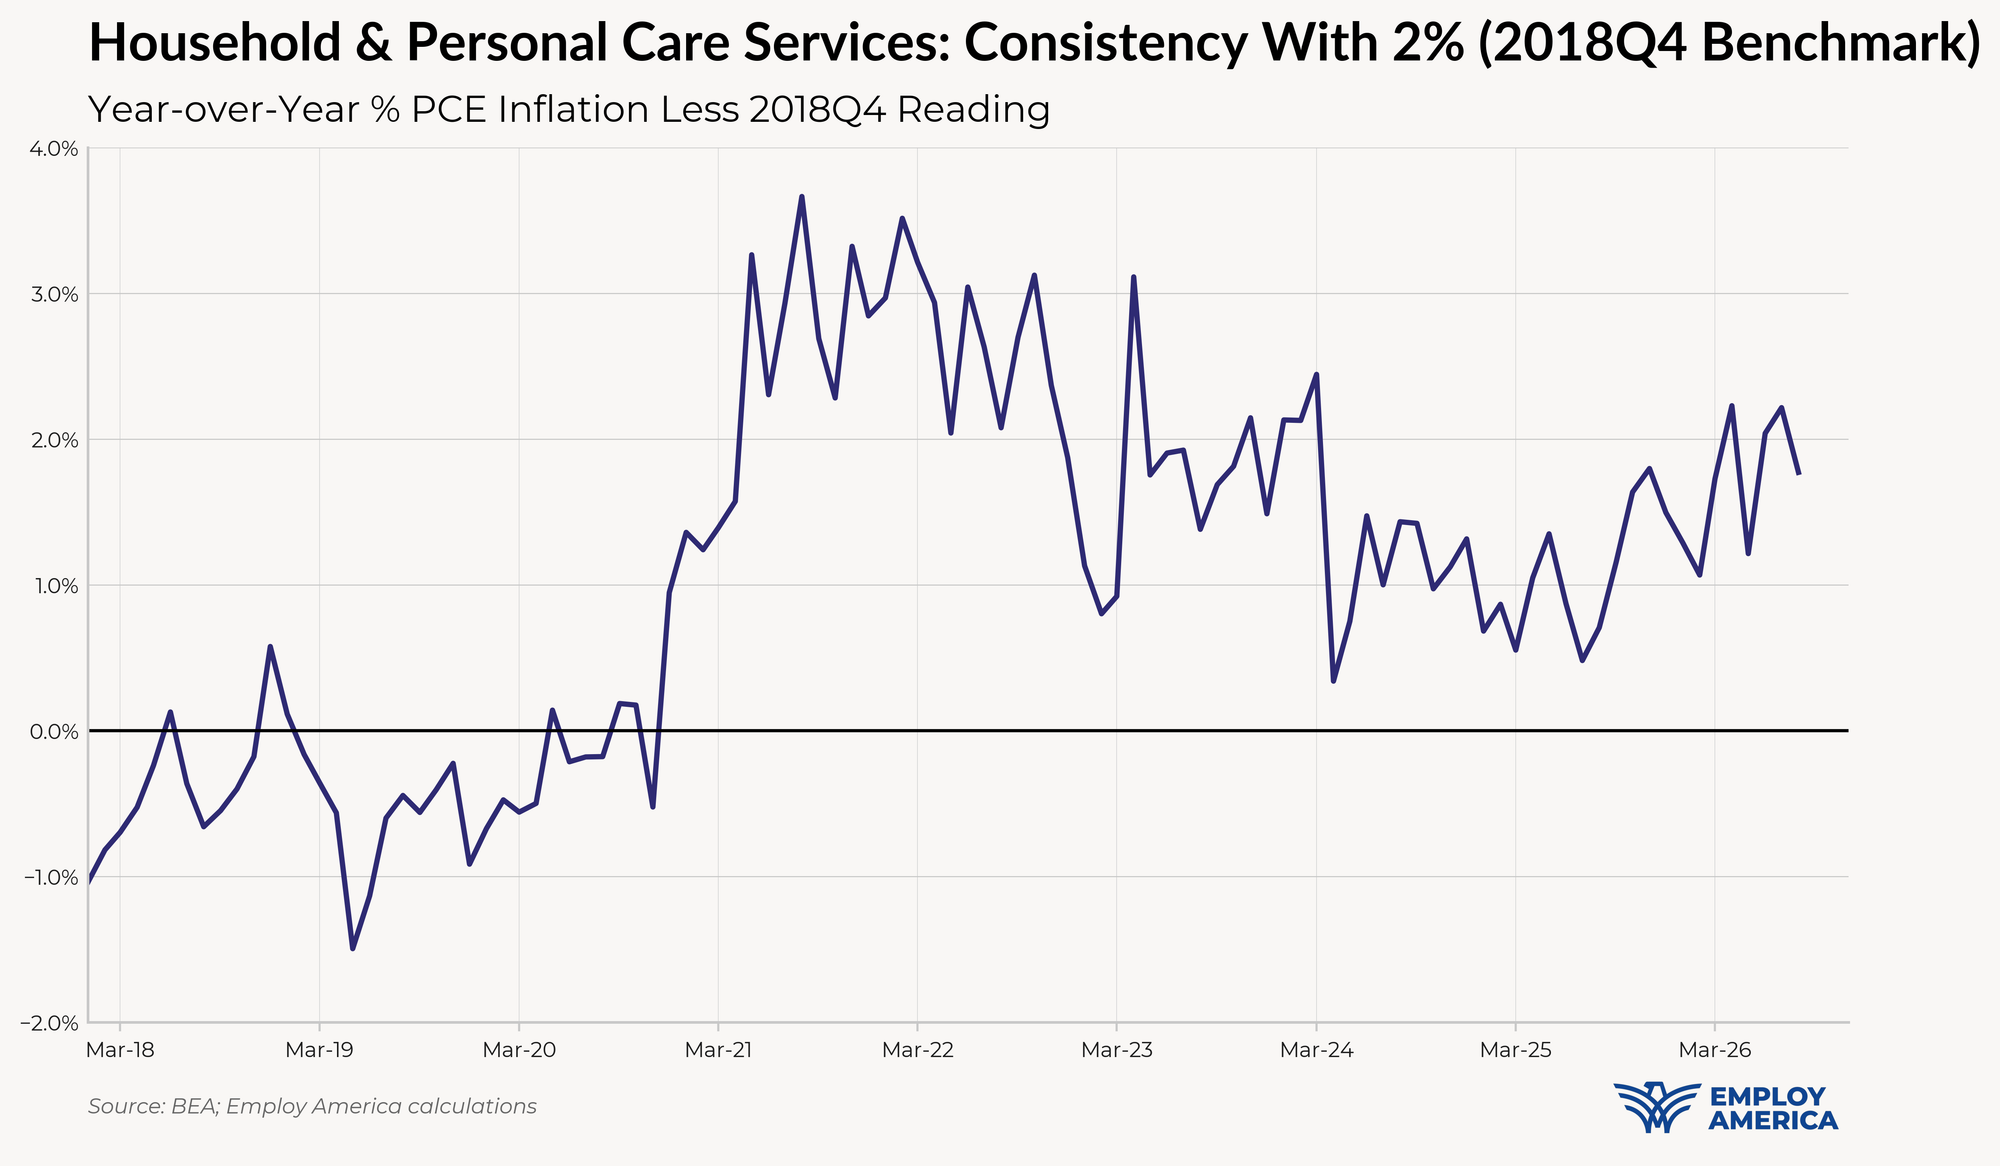
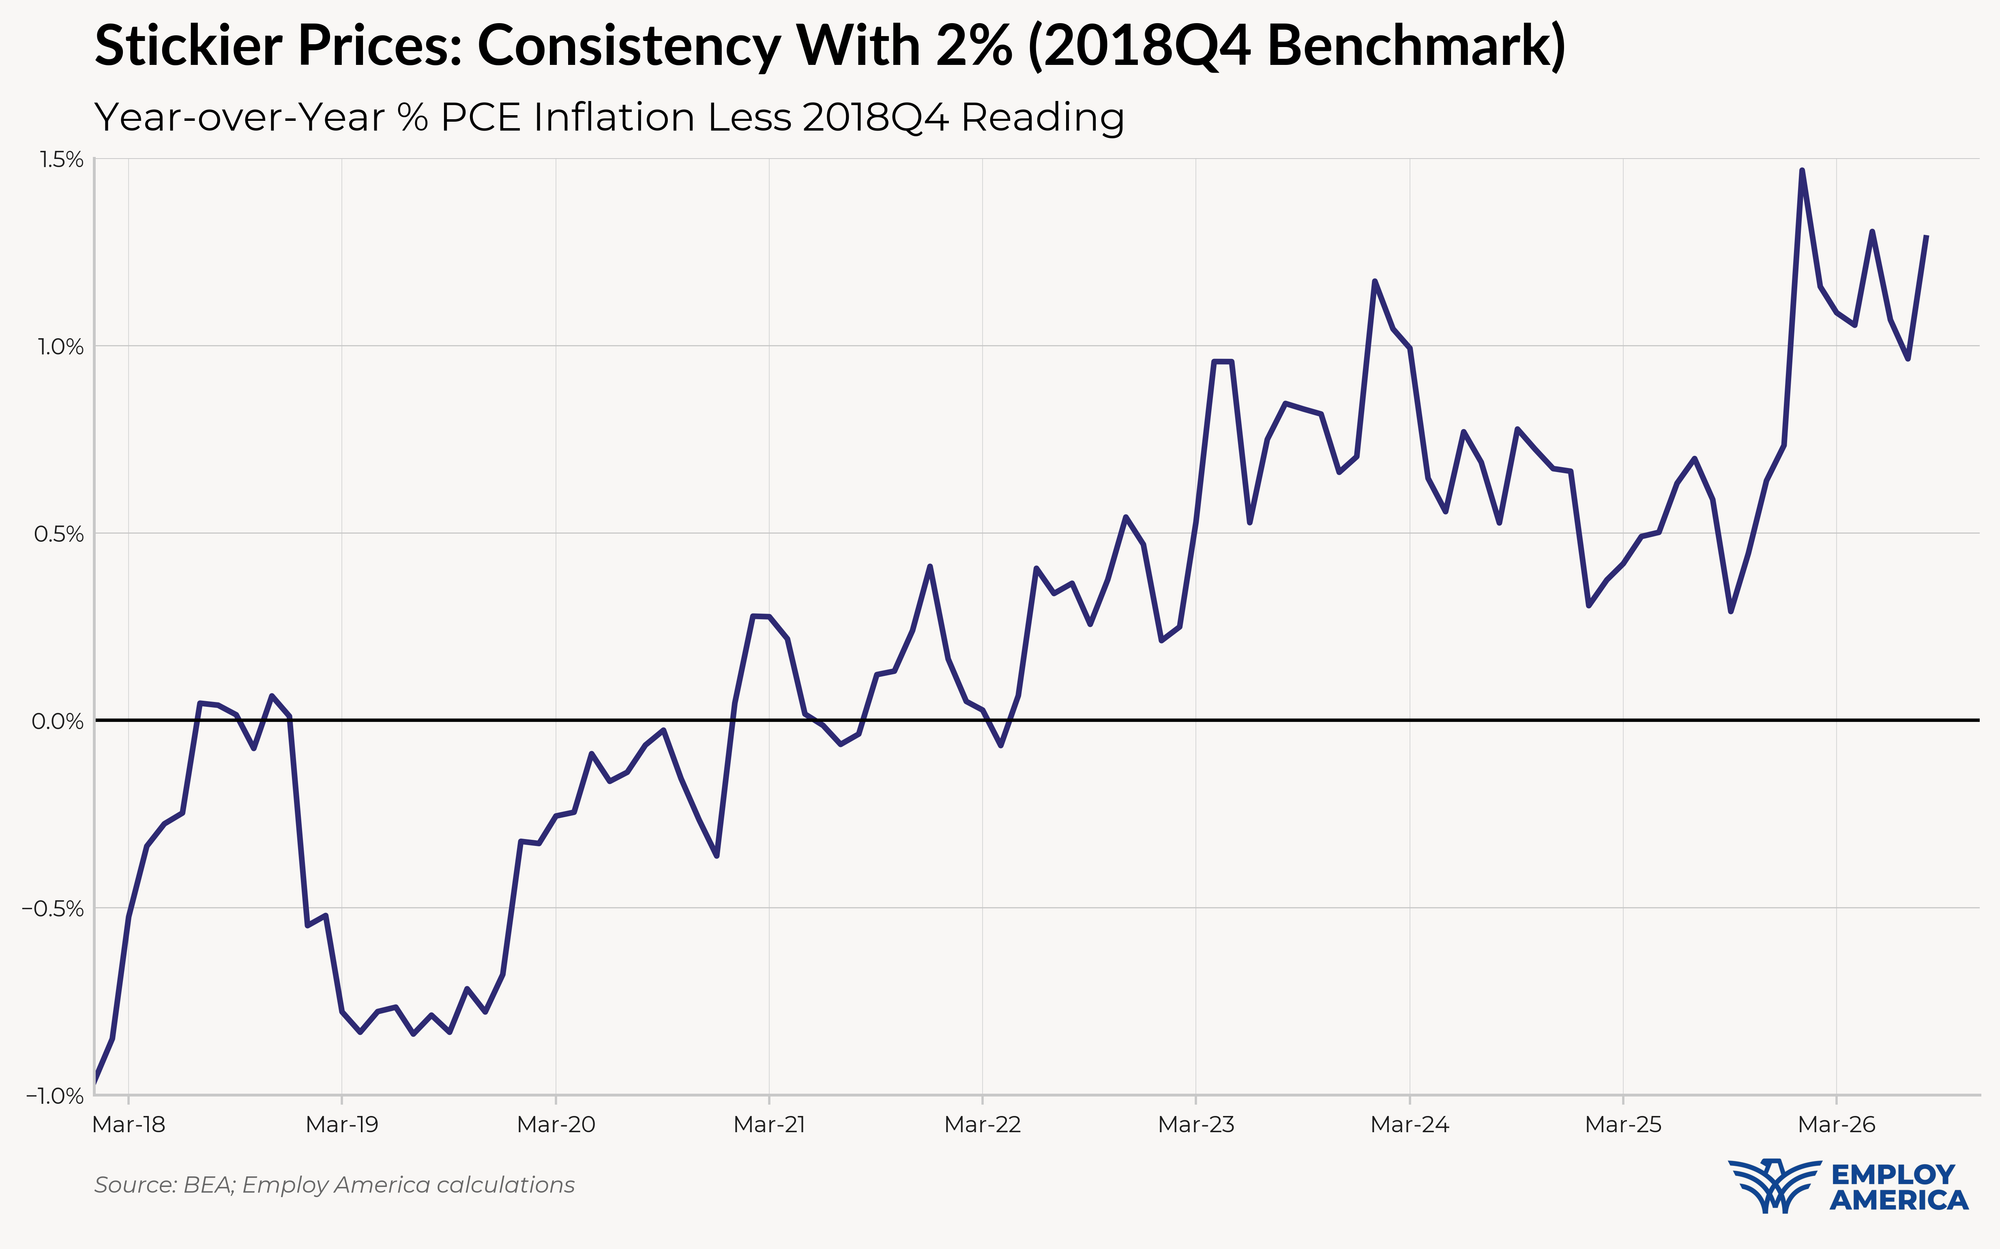
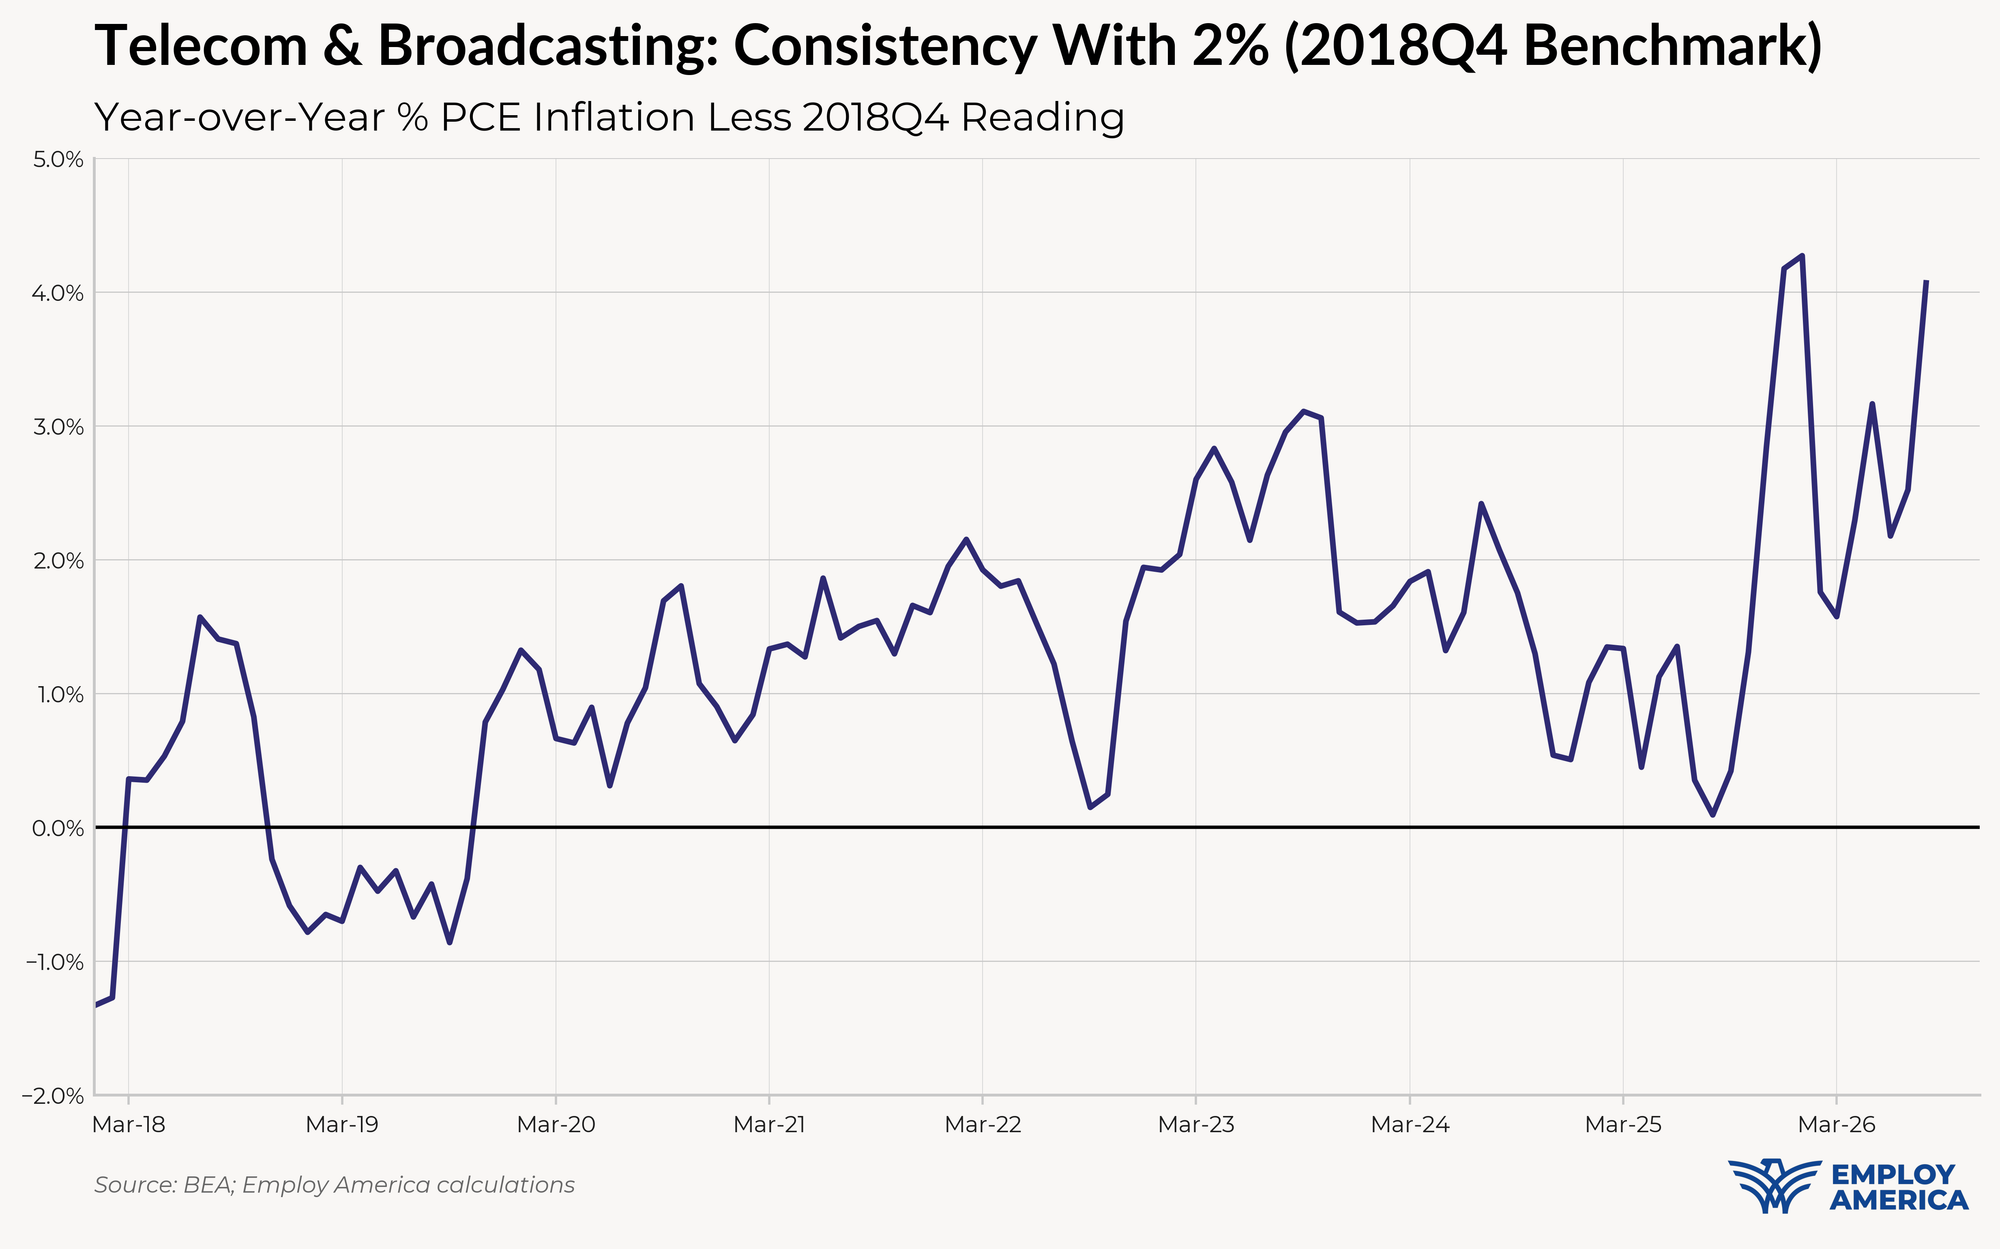
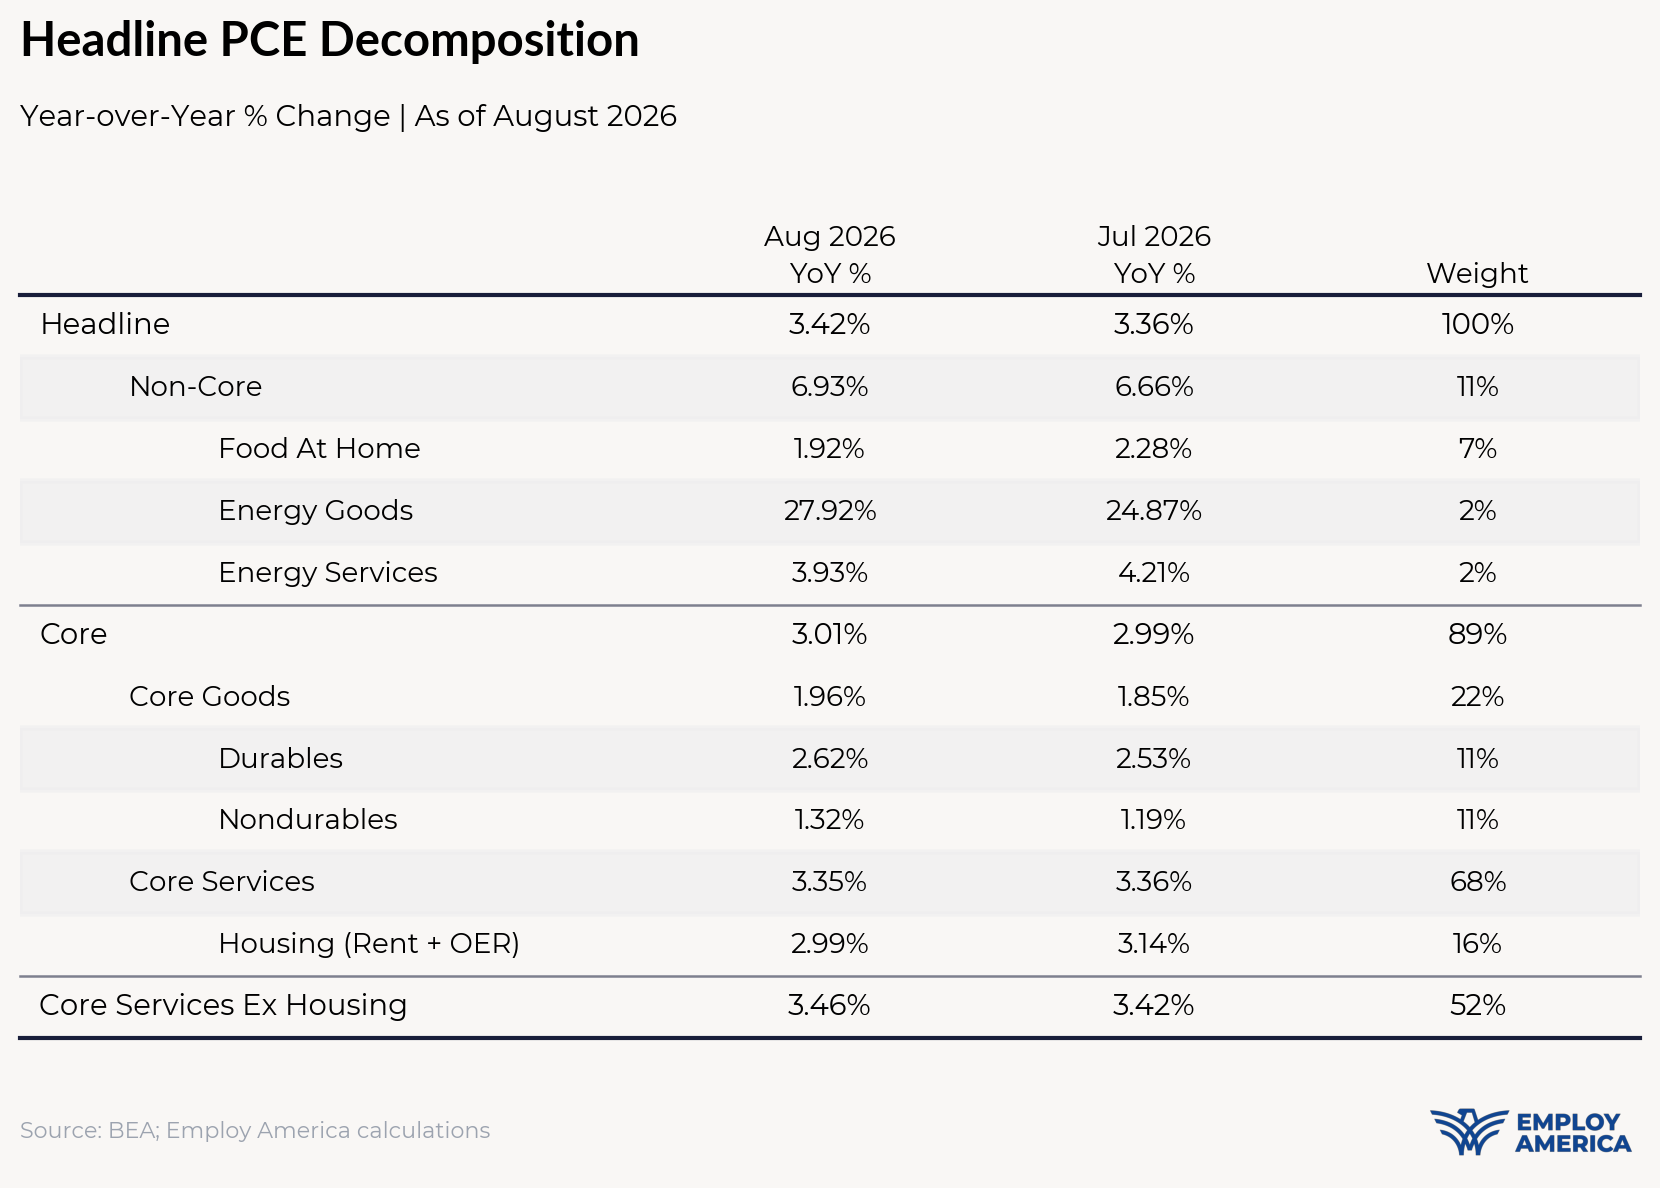
Right now Core PCE (PCE less food products and energy) is on track to run at a 3.01% year-over-year pace as of July, 101 basis points above the Fed's 2% inflation target for PCE.
Contributors to the overshoot:
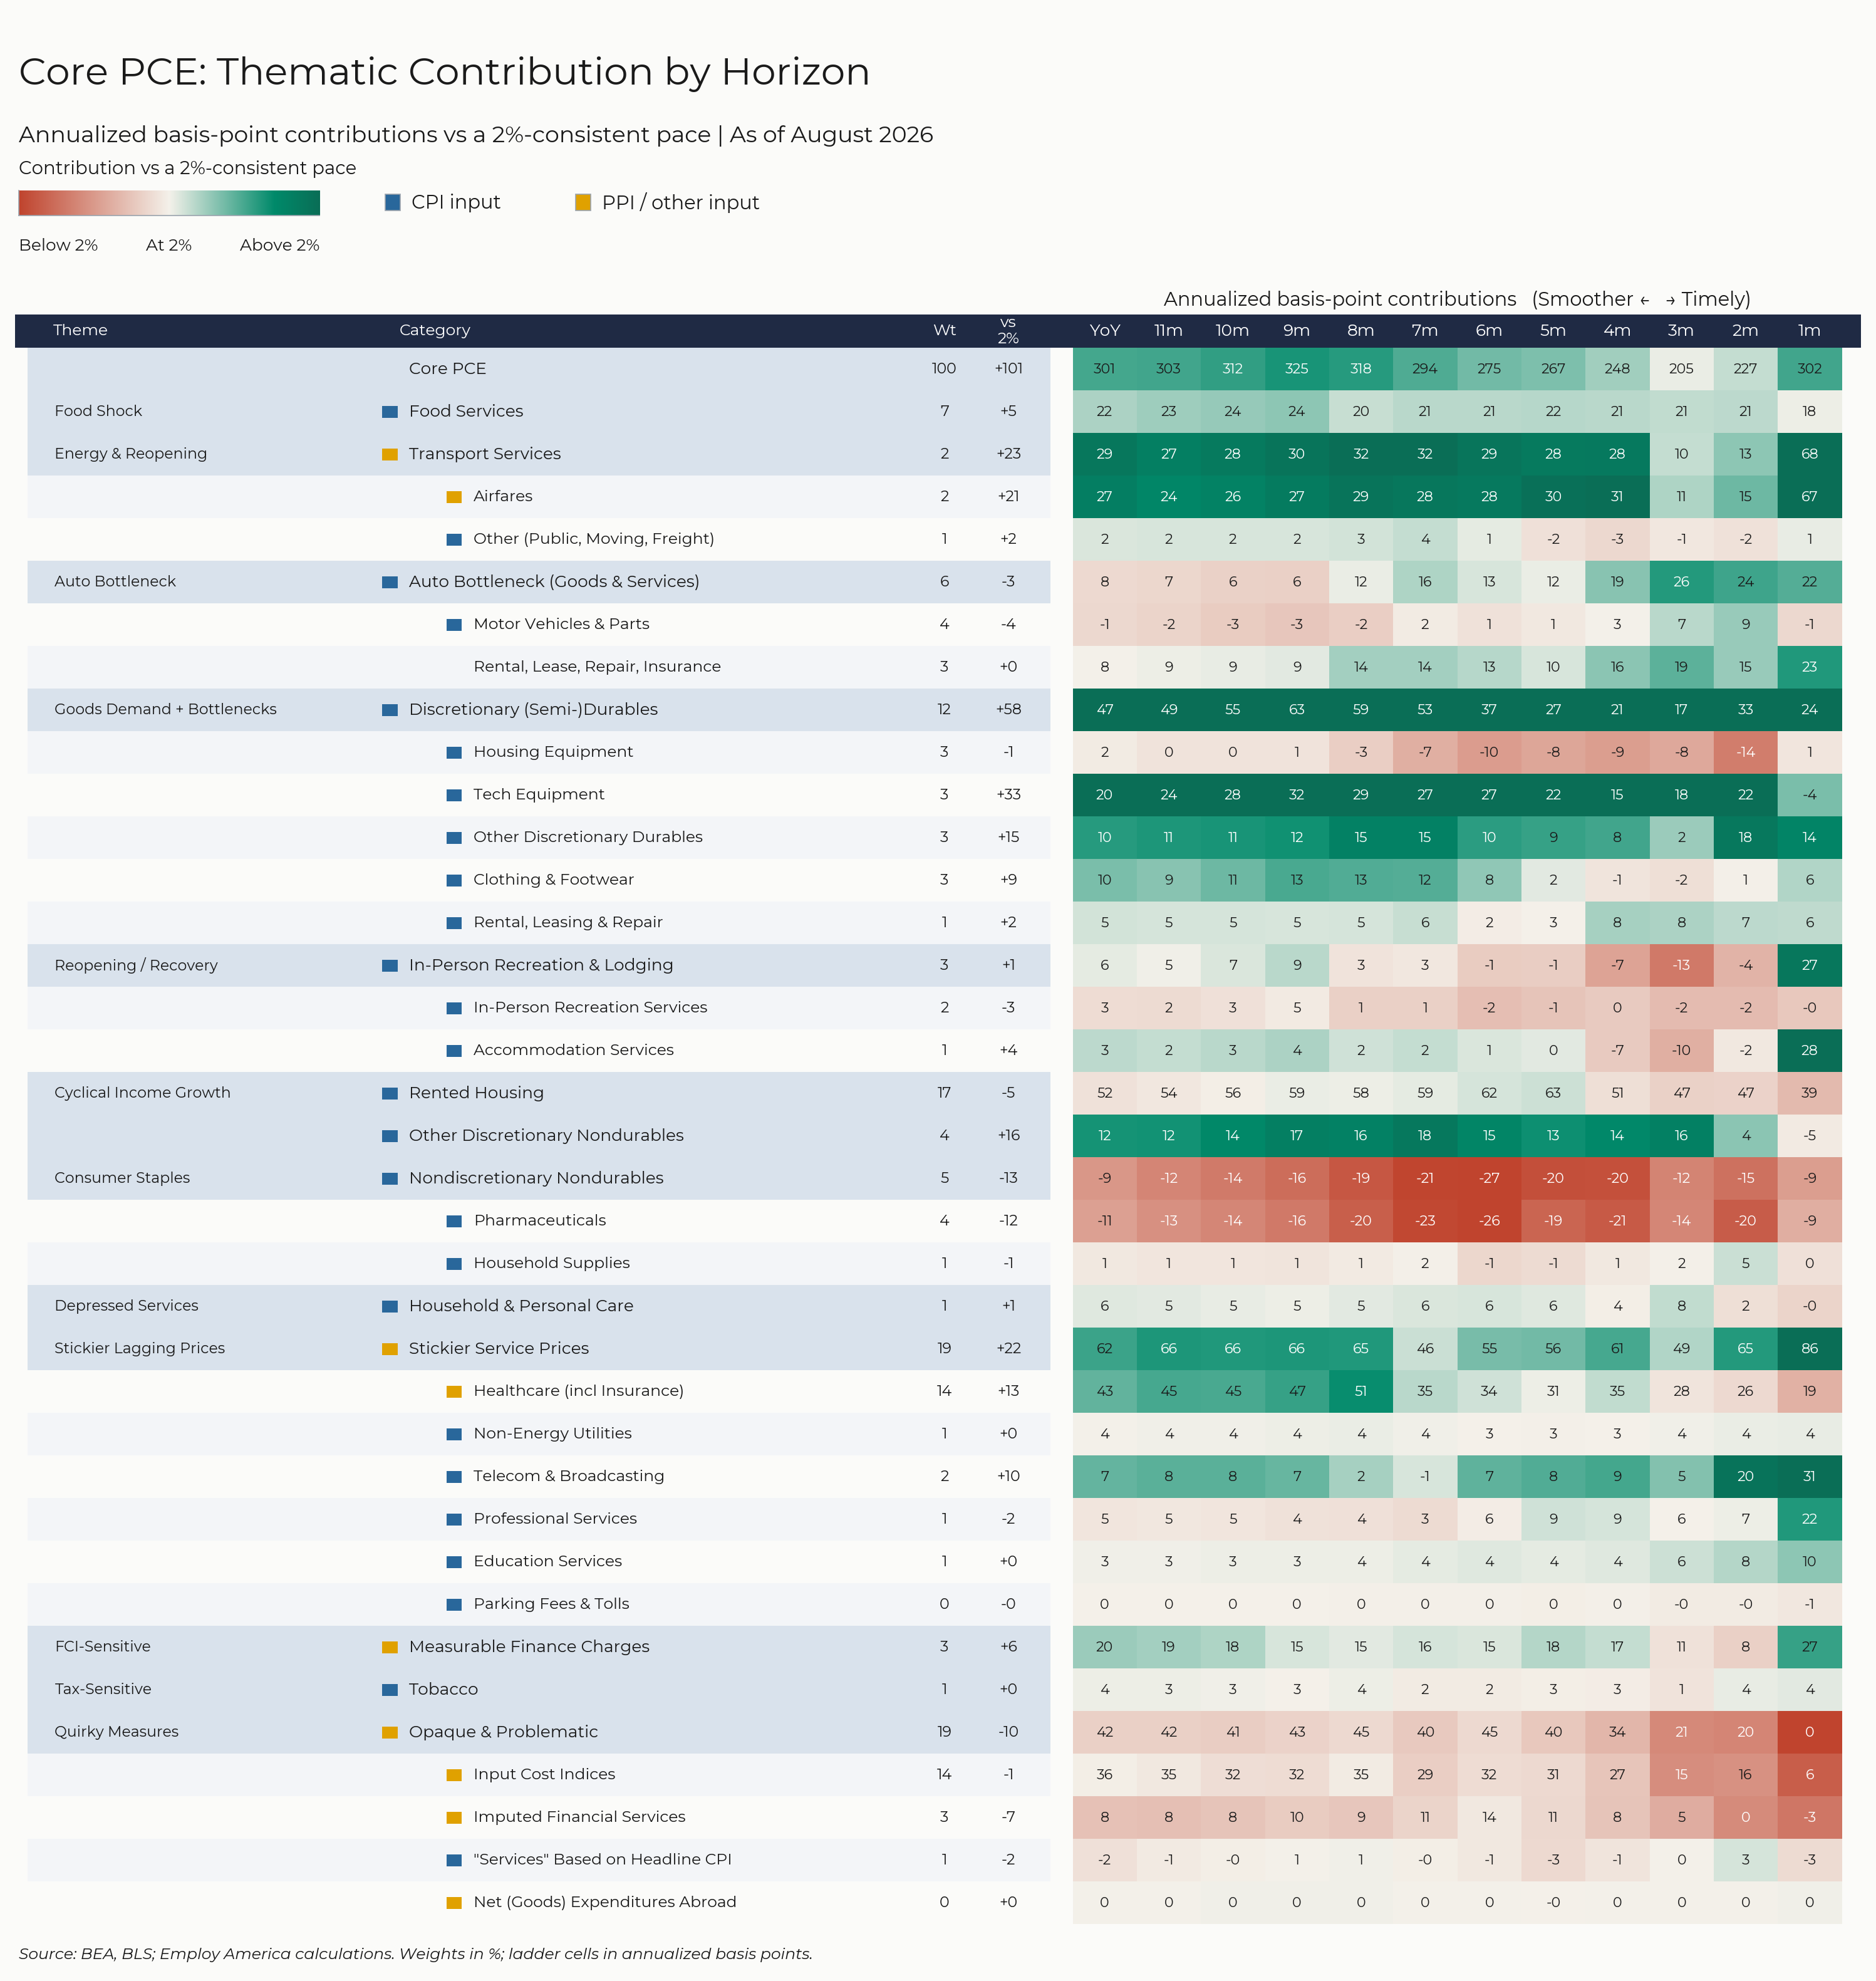
The final heatmap below gives you a sense of the overshoot on shorter annualized run-rates. August monthly annualized Core PCE is running at a 3.02% annualized pace, a 102 basis point overshoot vs 2% target inflation.

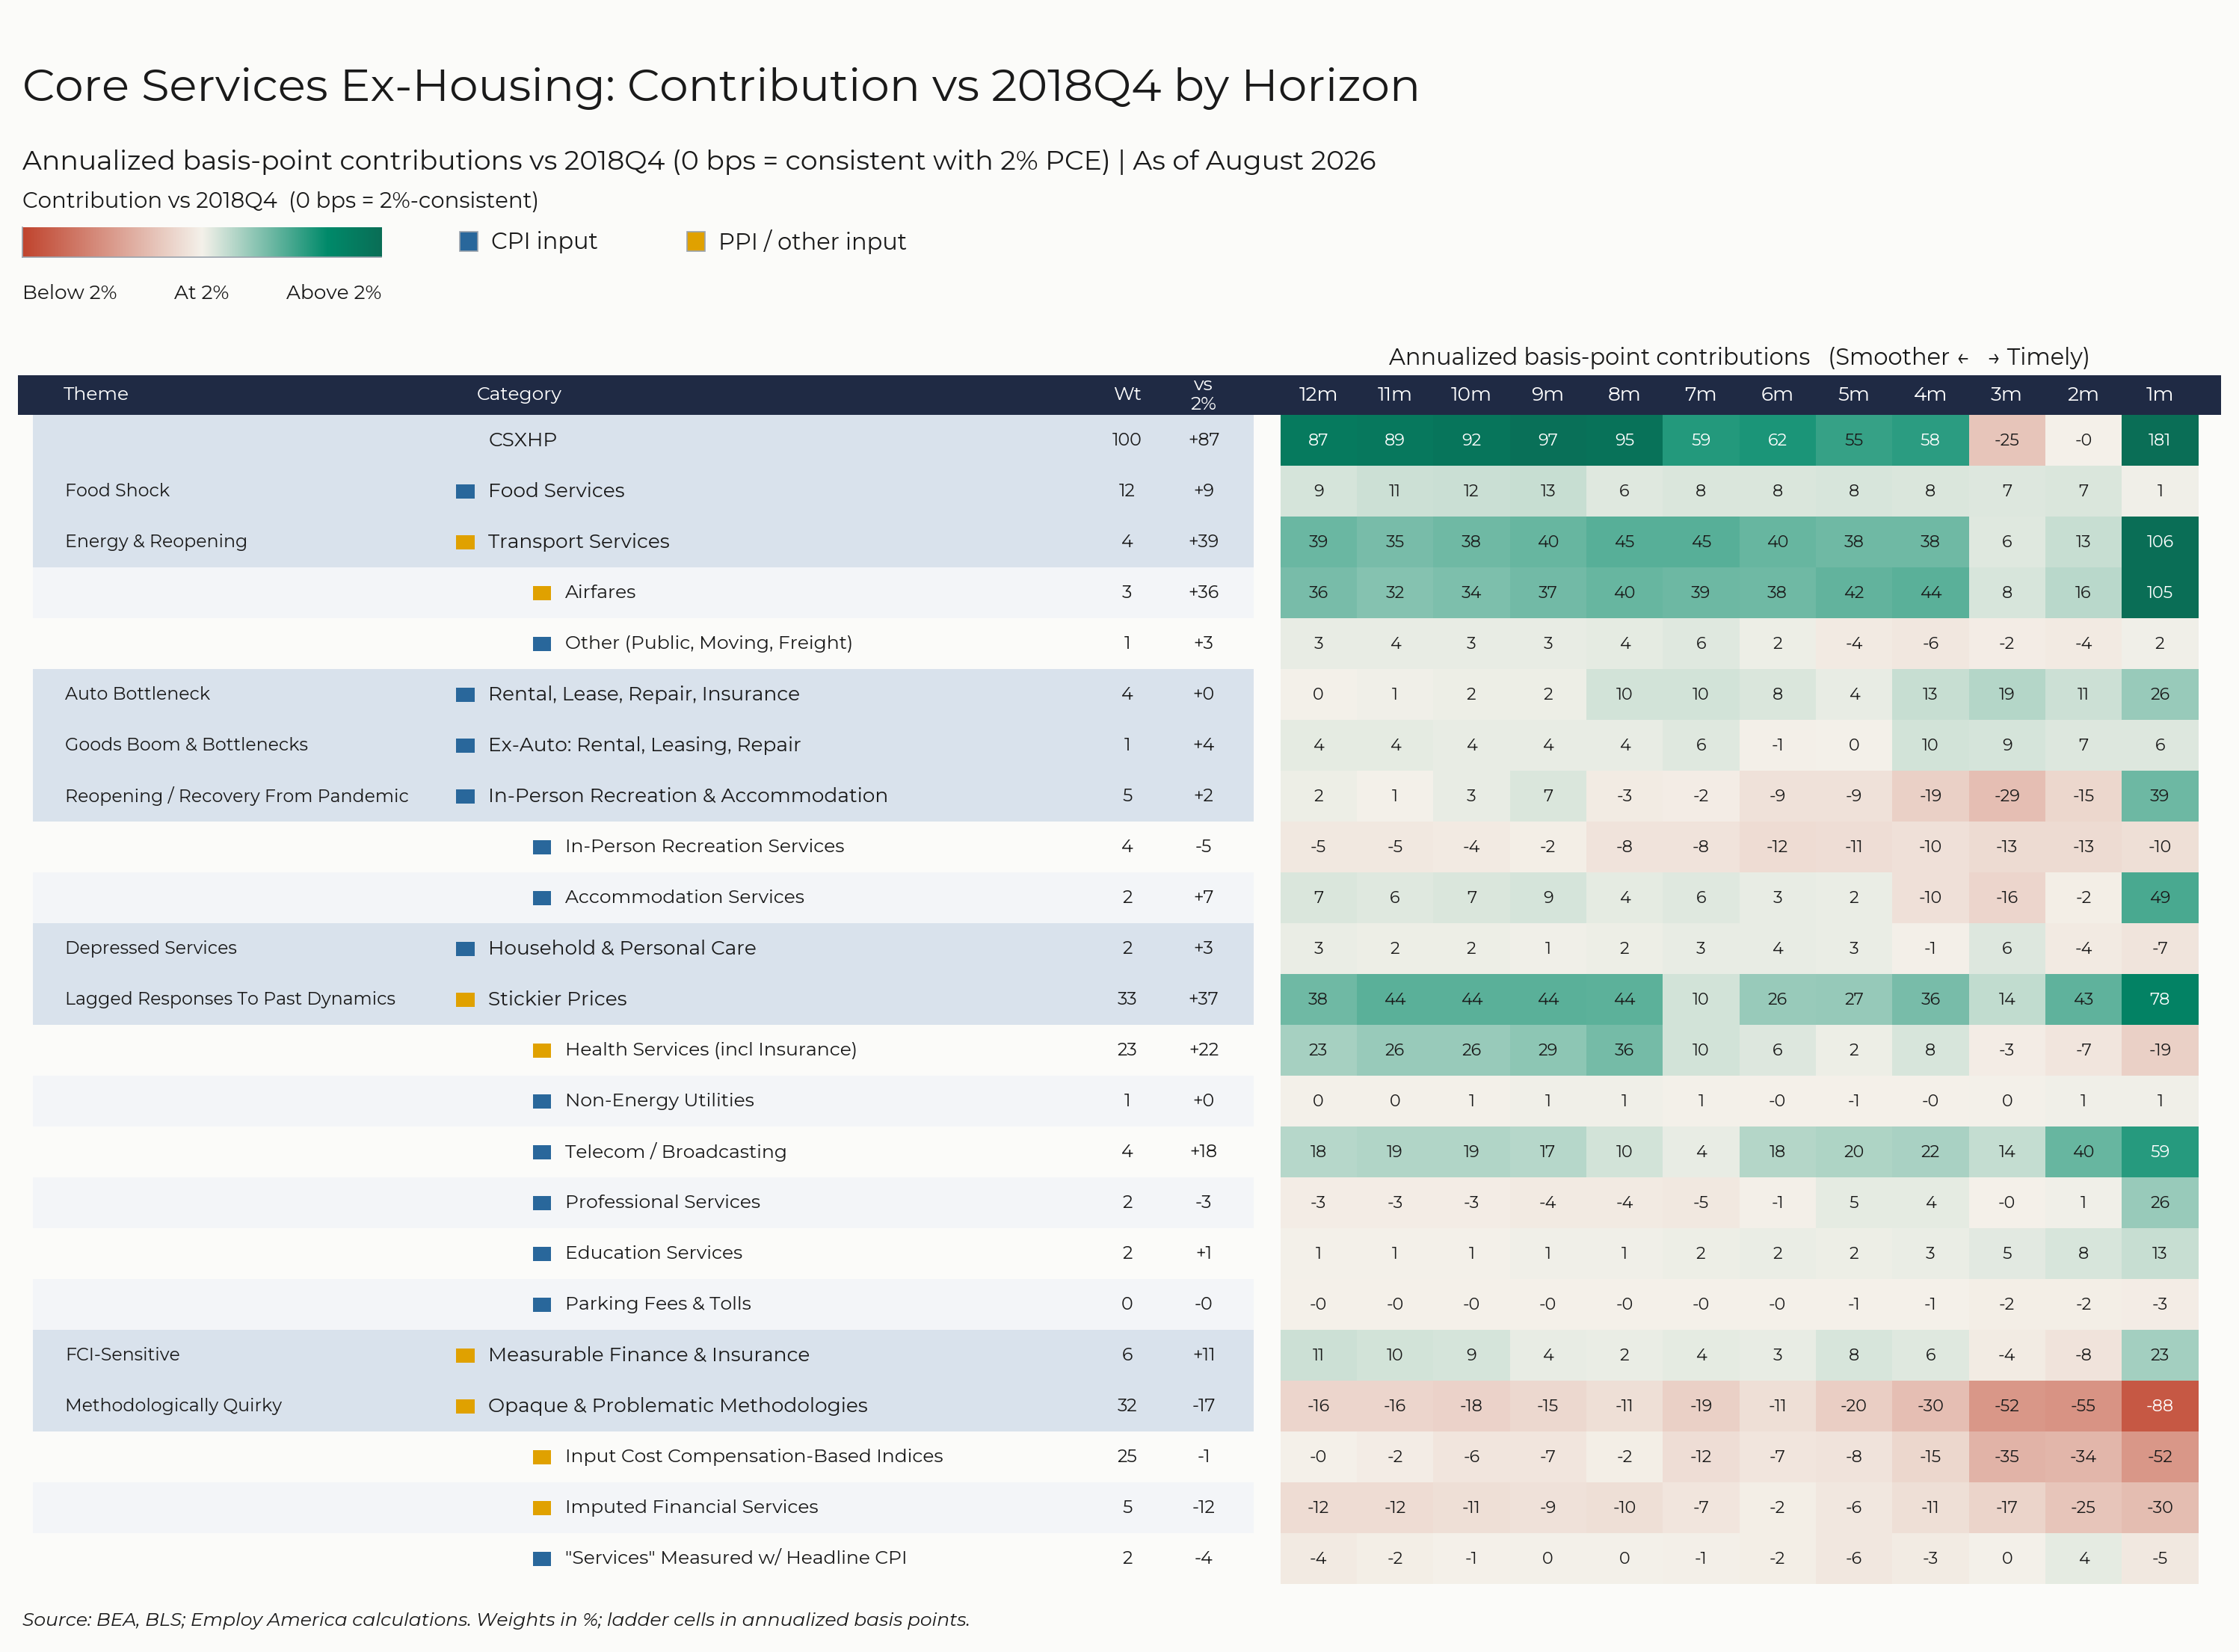
The August growth rate in "Core Services Ex-Housing" ('Supercore') PCE ran at a 3.46% year-over-year pace, an 87 basis point overshoot versus the ~2.59% run rate that coincided with ~2% Headline and Core PCE inflation.
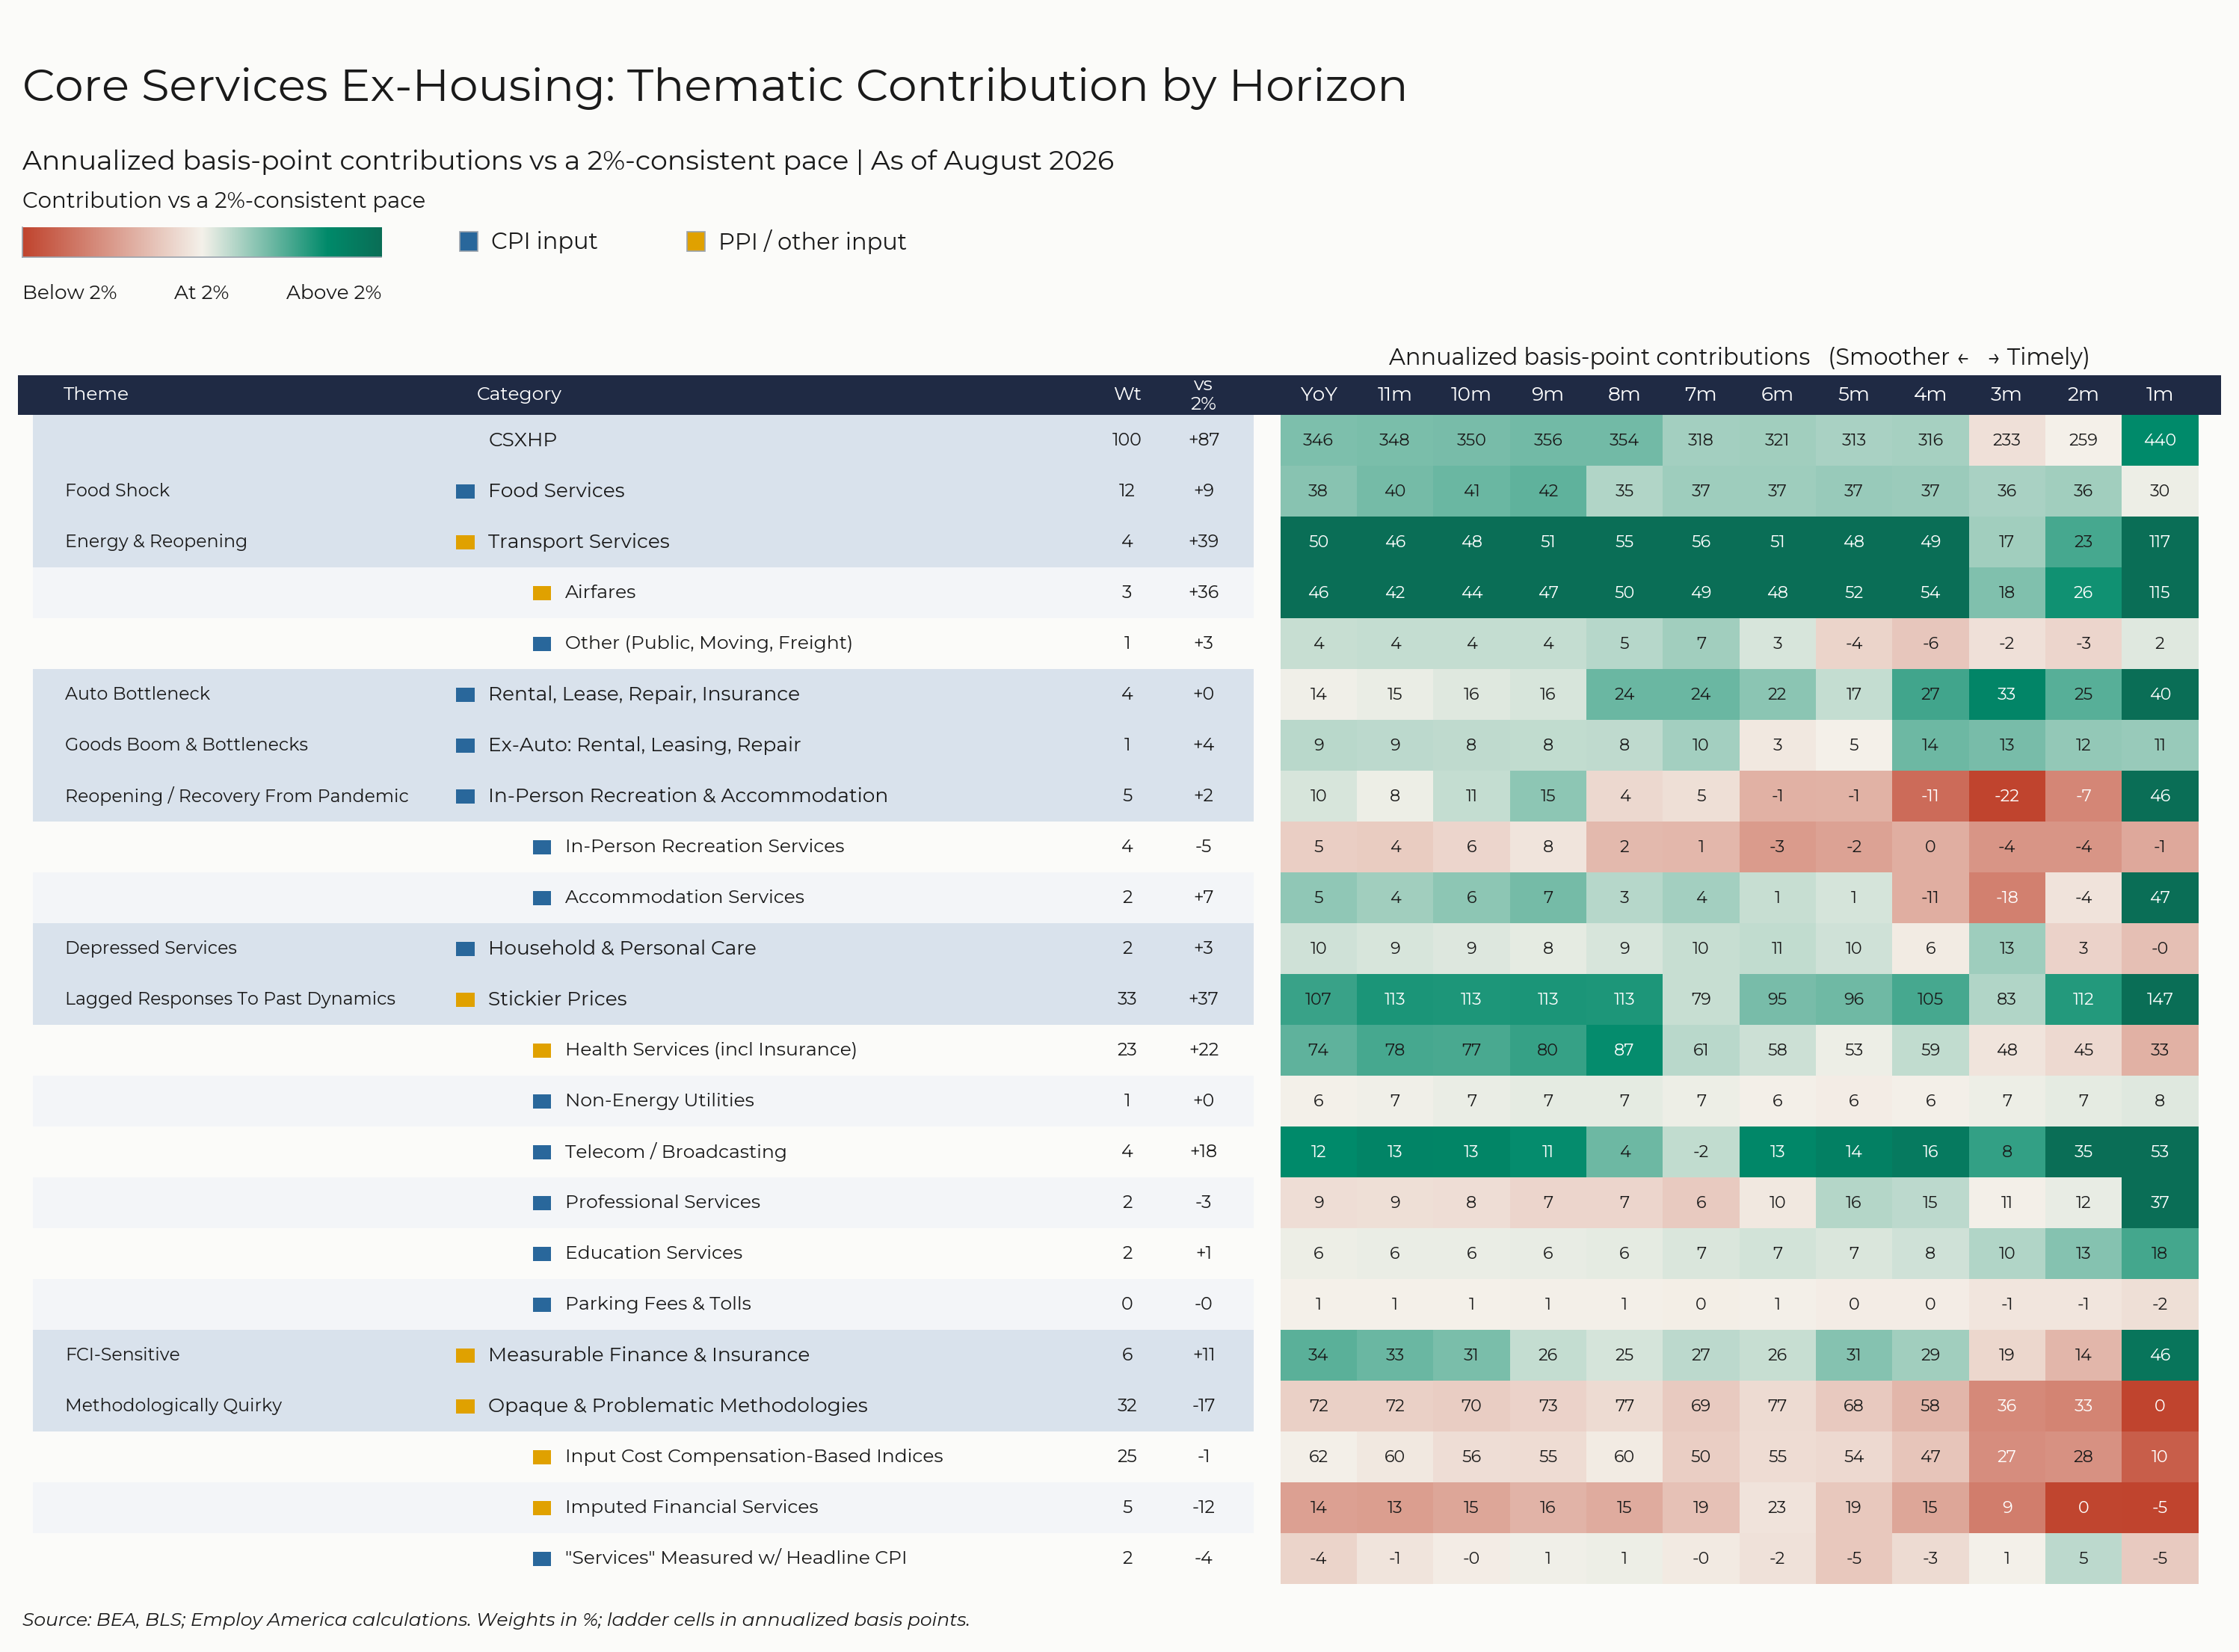
August monthly Supercore is running at a 4.40% annualized rate, a 181 basis point annualized overshoot of what would be consistent with 2% Headline and Core PCE.