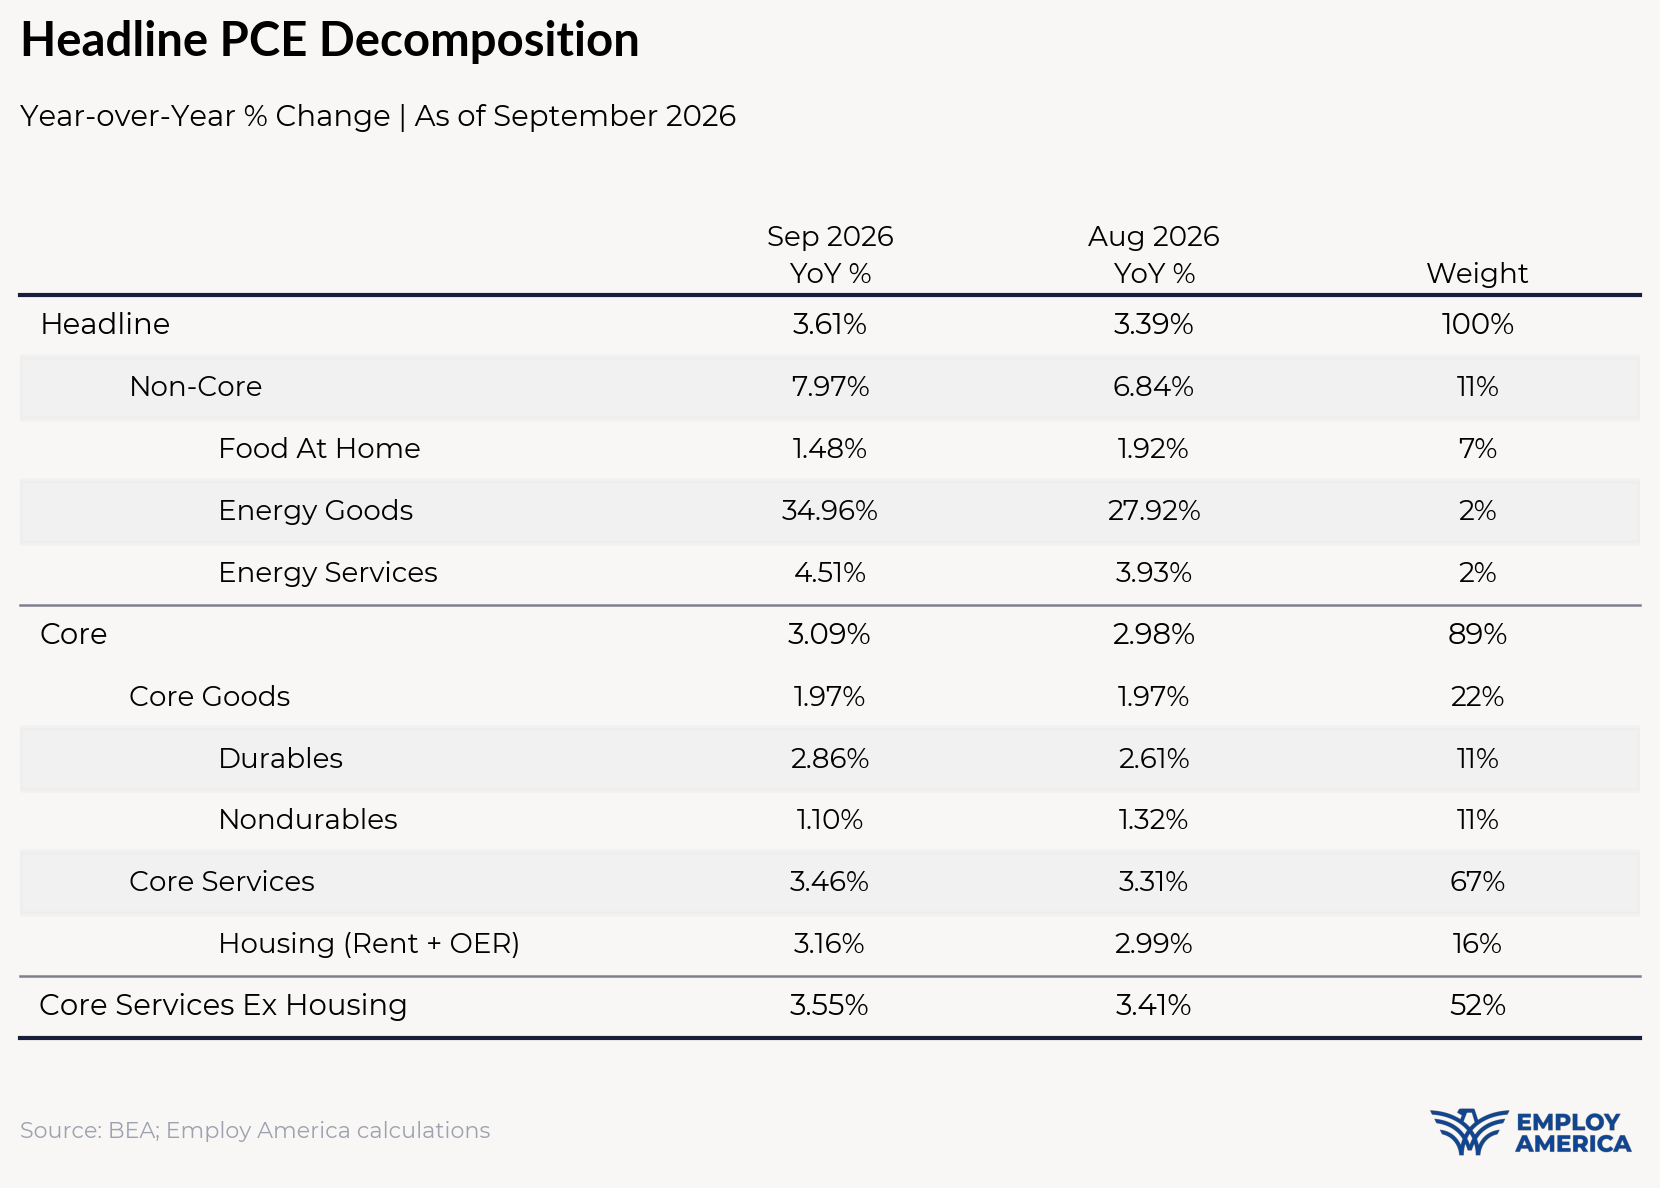
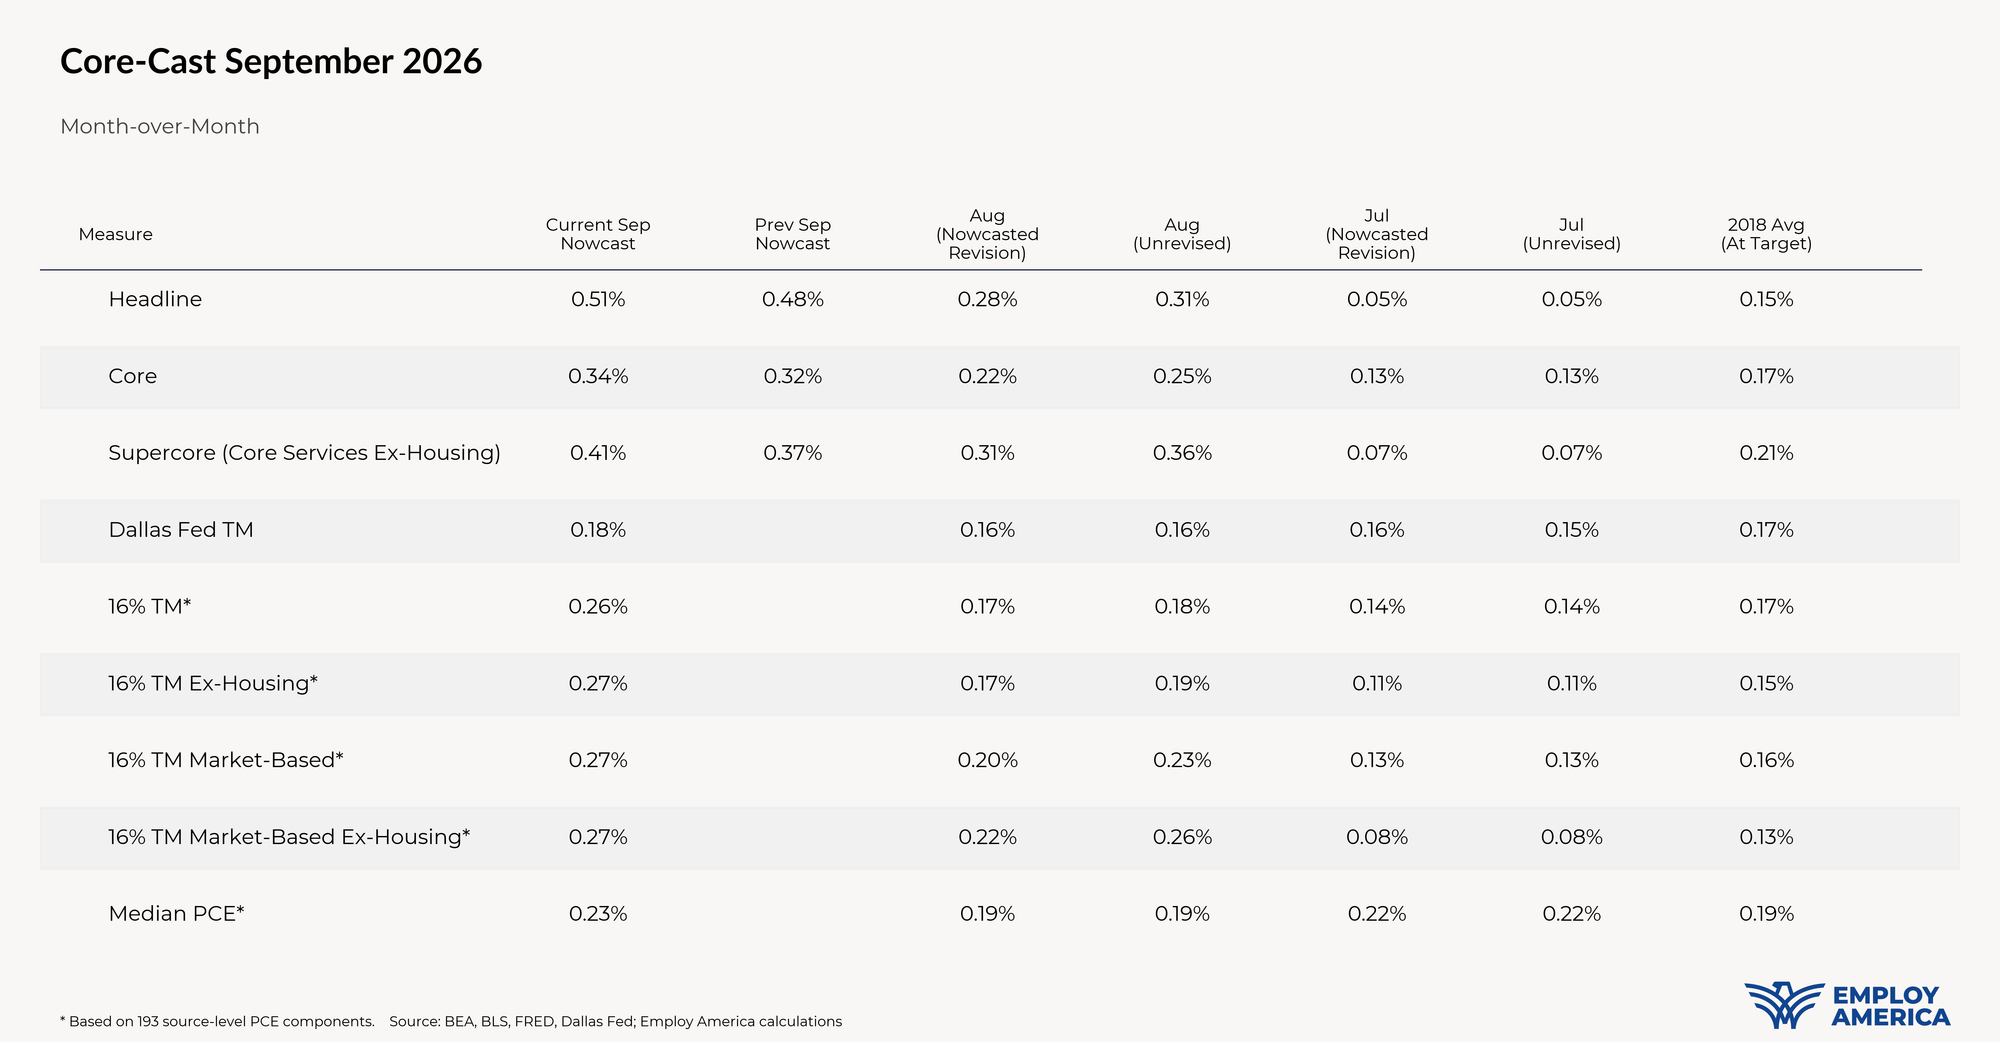
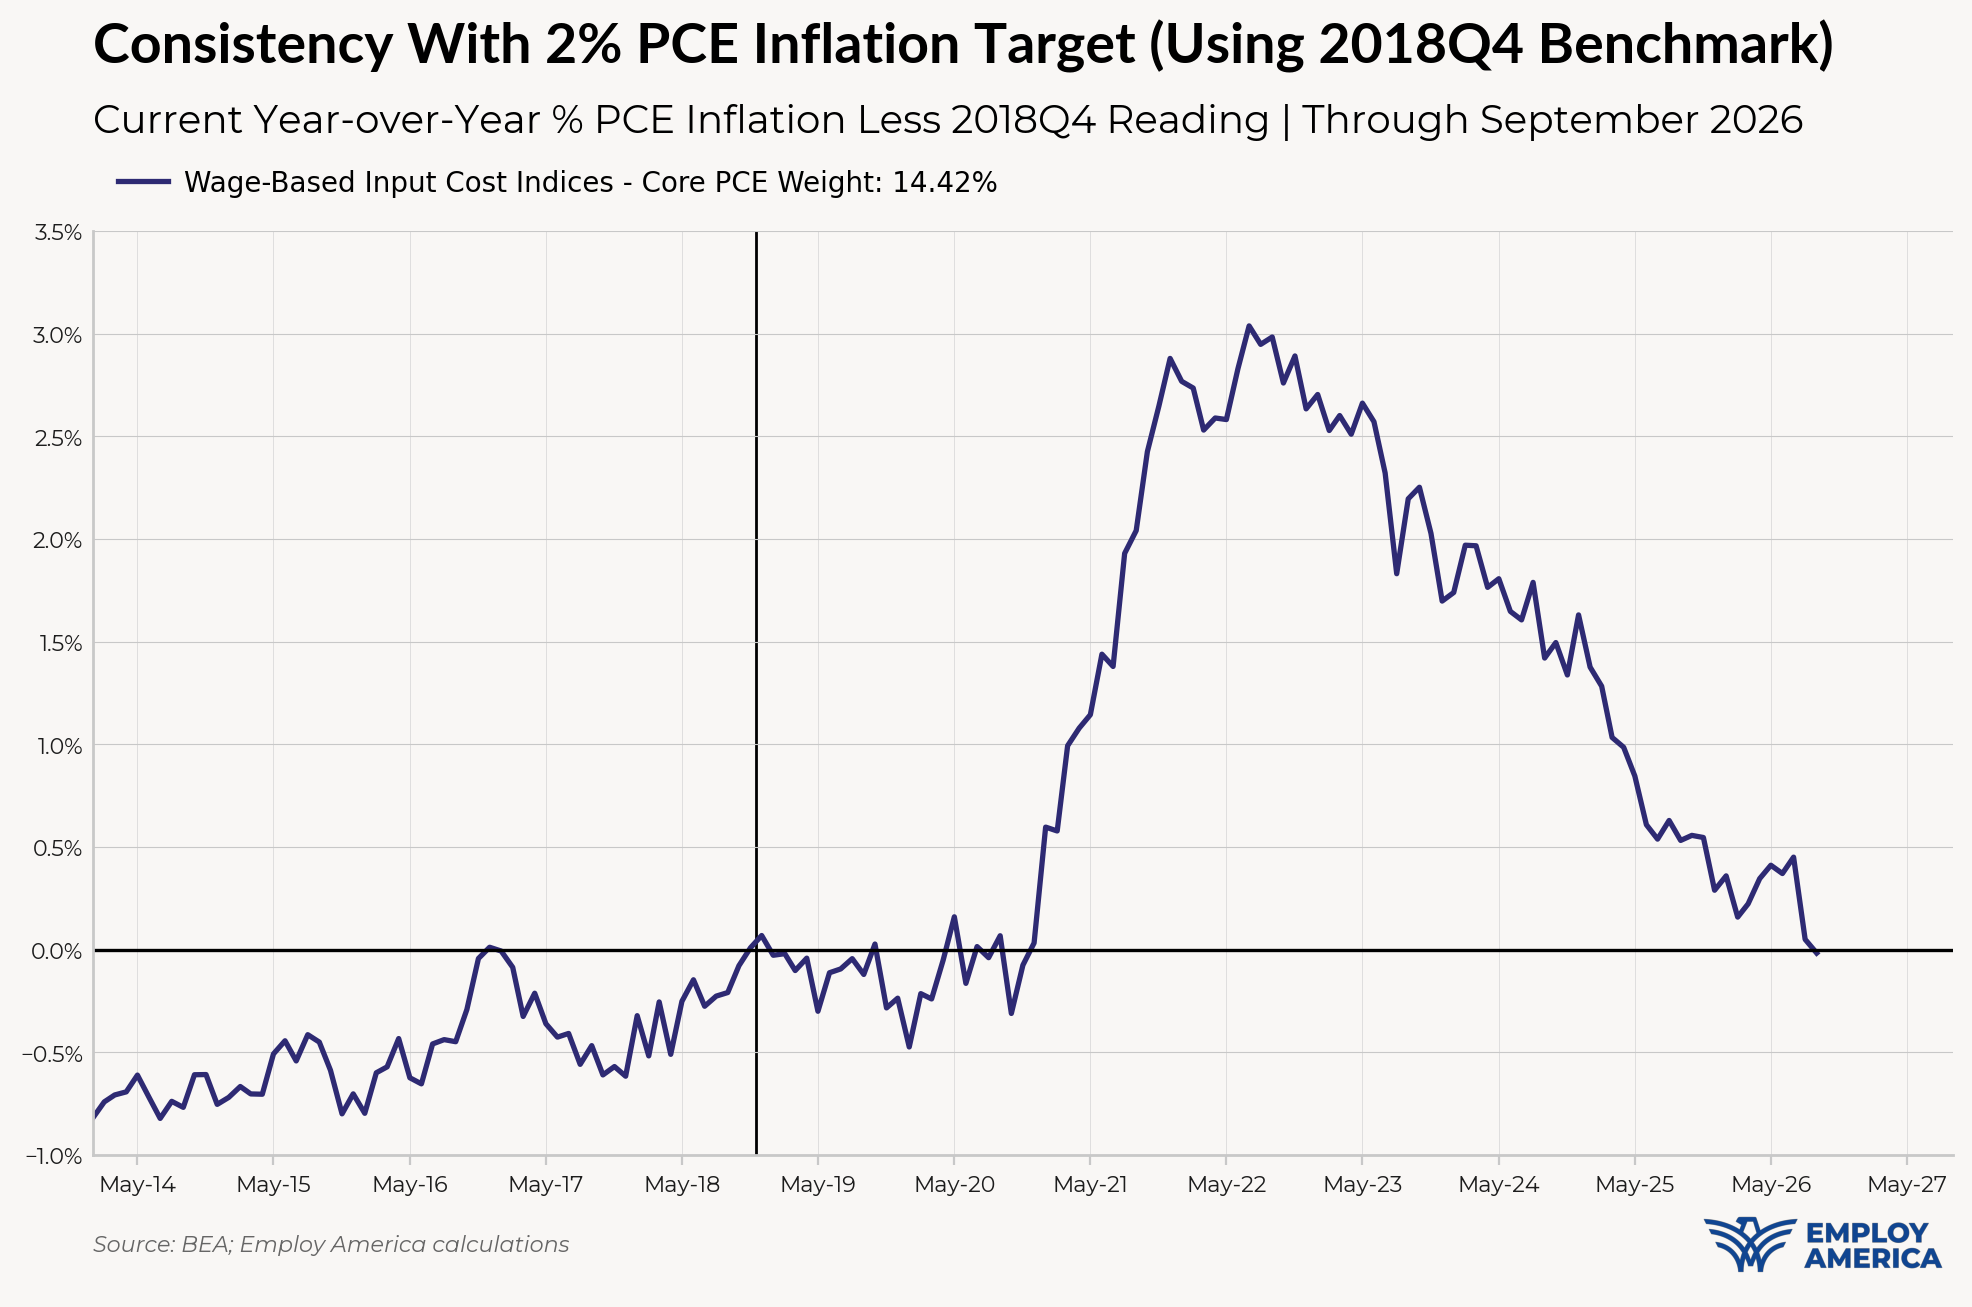
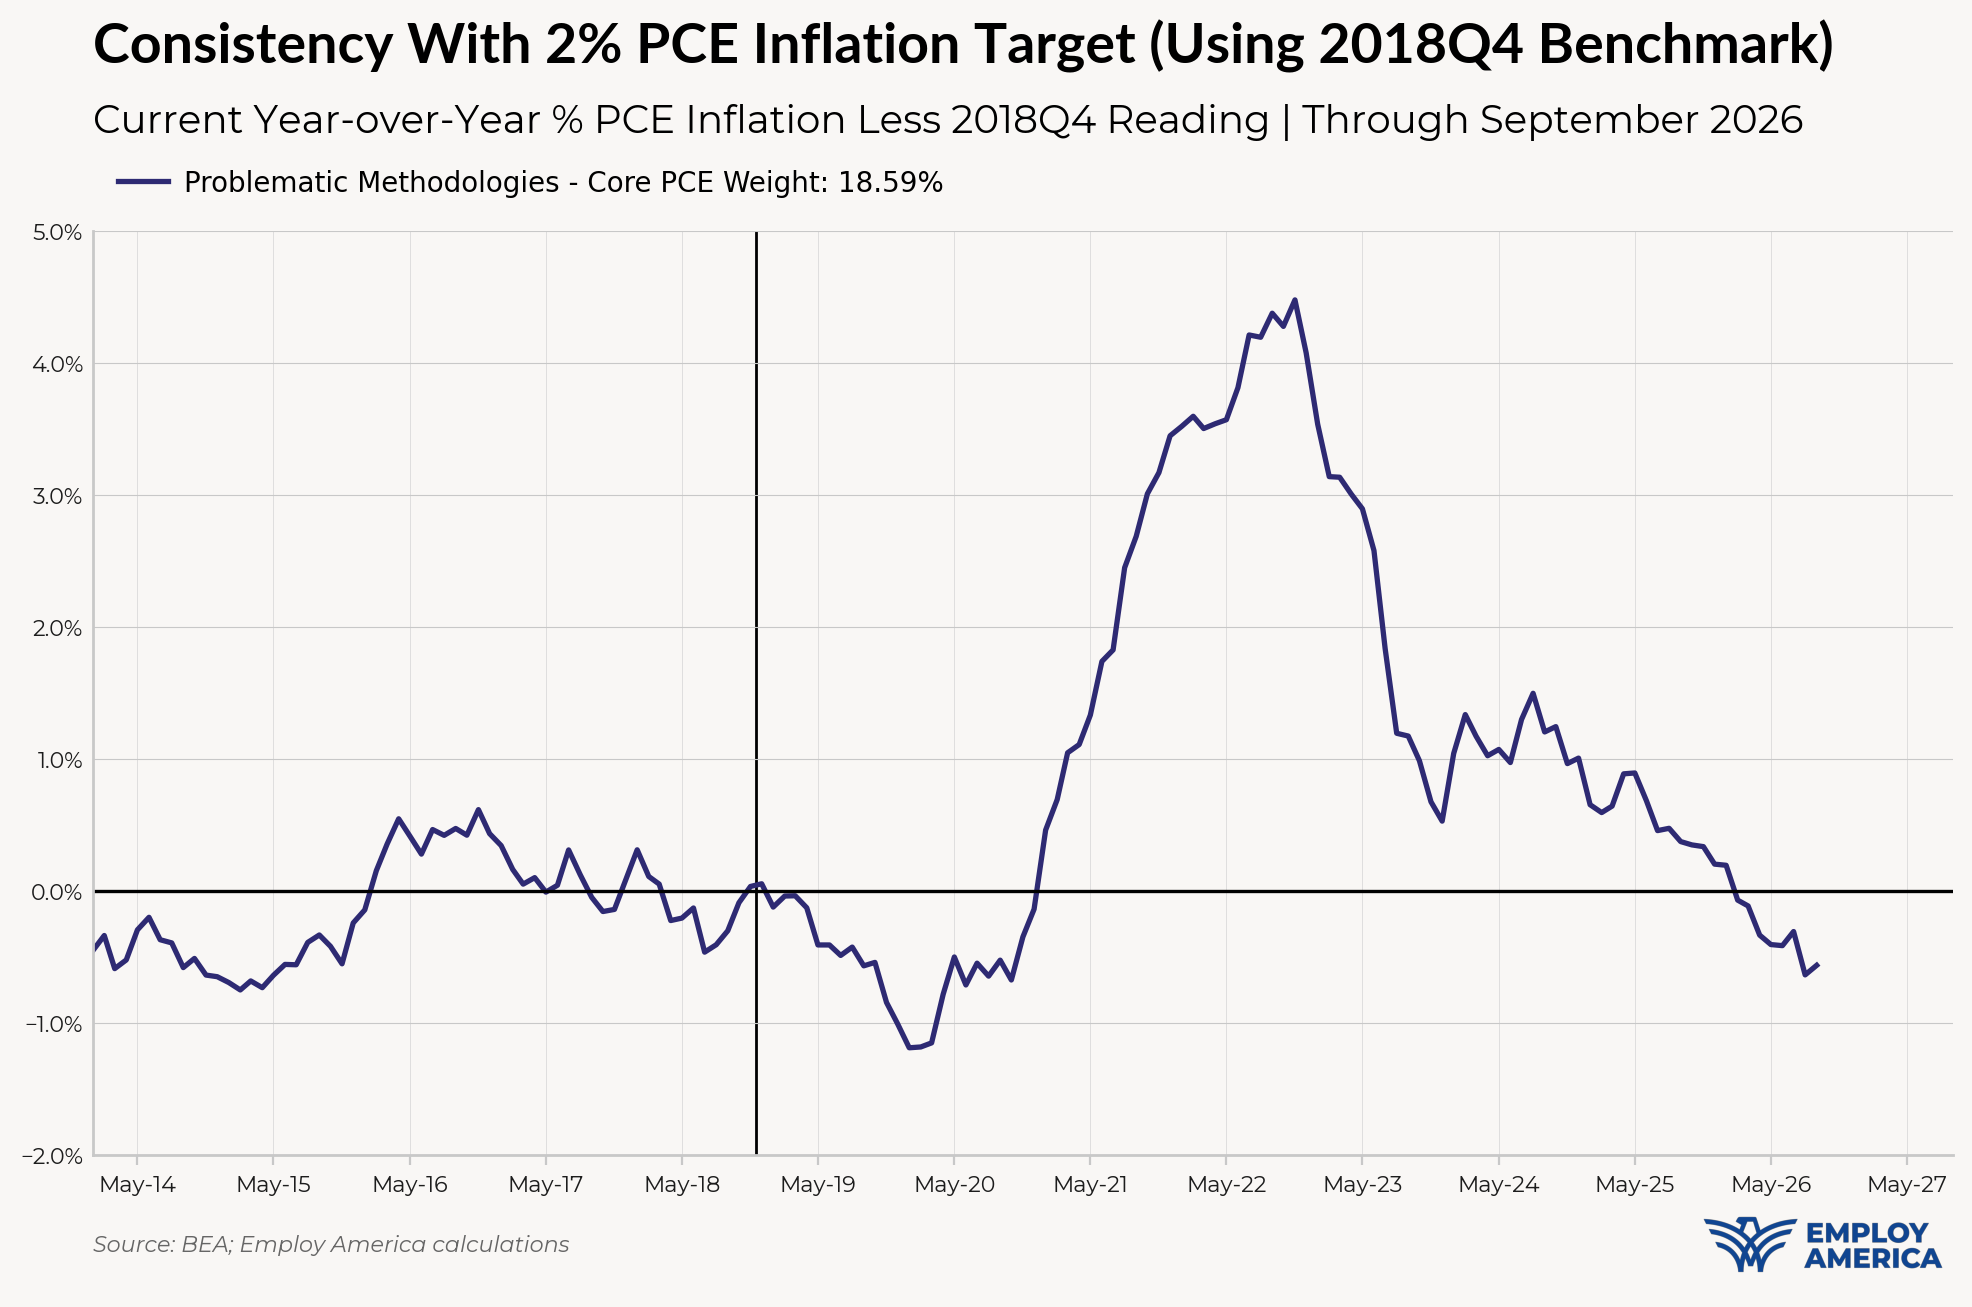
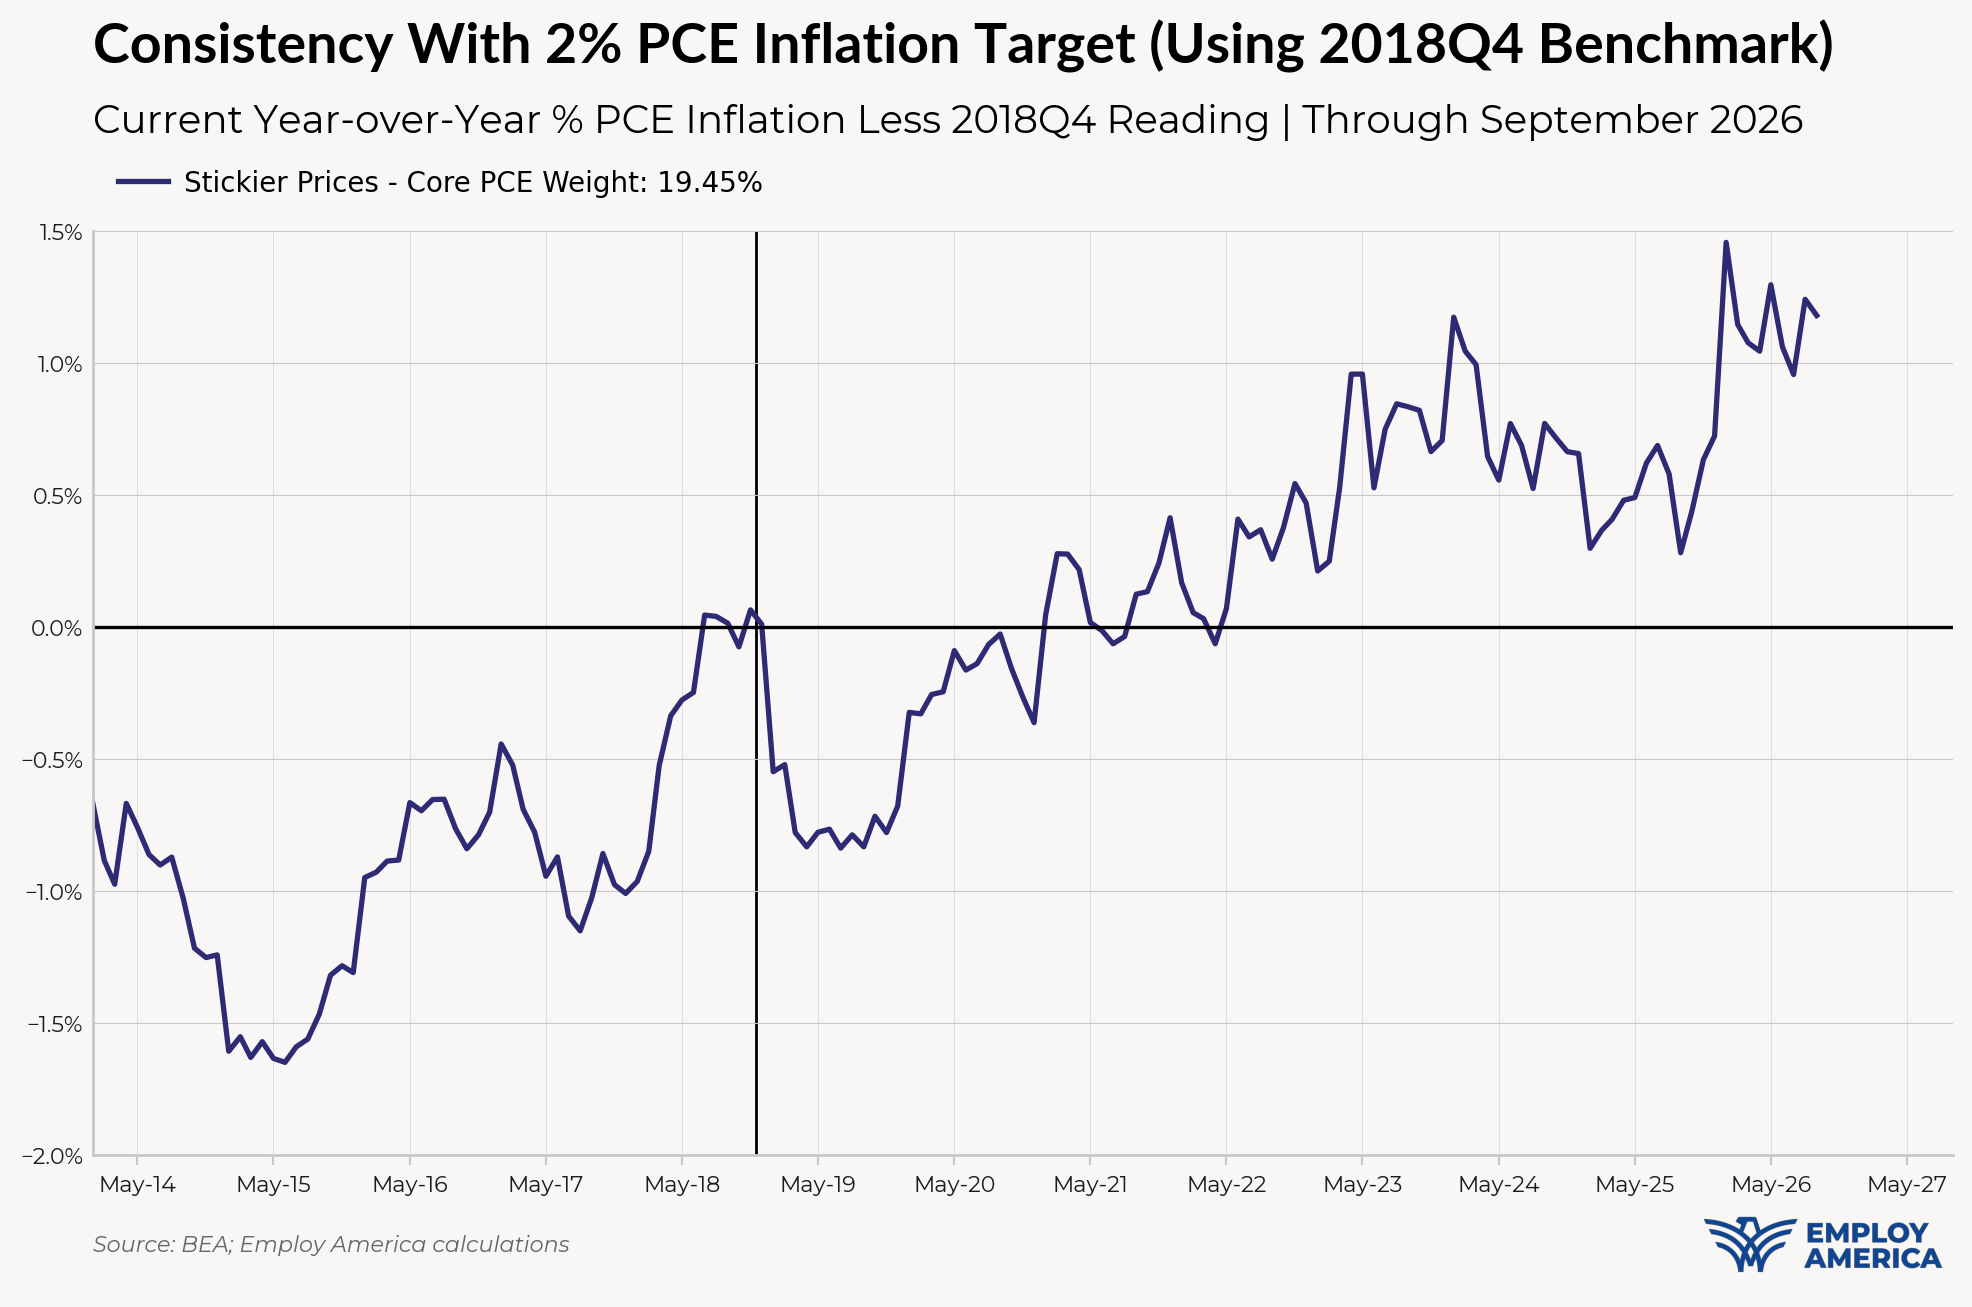
Following today’s PPI release, we are updating our nowcast by +2bps to +34bps m/m and by −1bp to 3.09% for the y/y September core PCE reading (a correction to the 3.12% y/y figure in our earlier email). We maintain our base case that the FOMC will hold rates steady at the October meeting and hike at the December meeting.
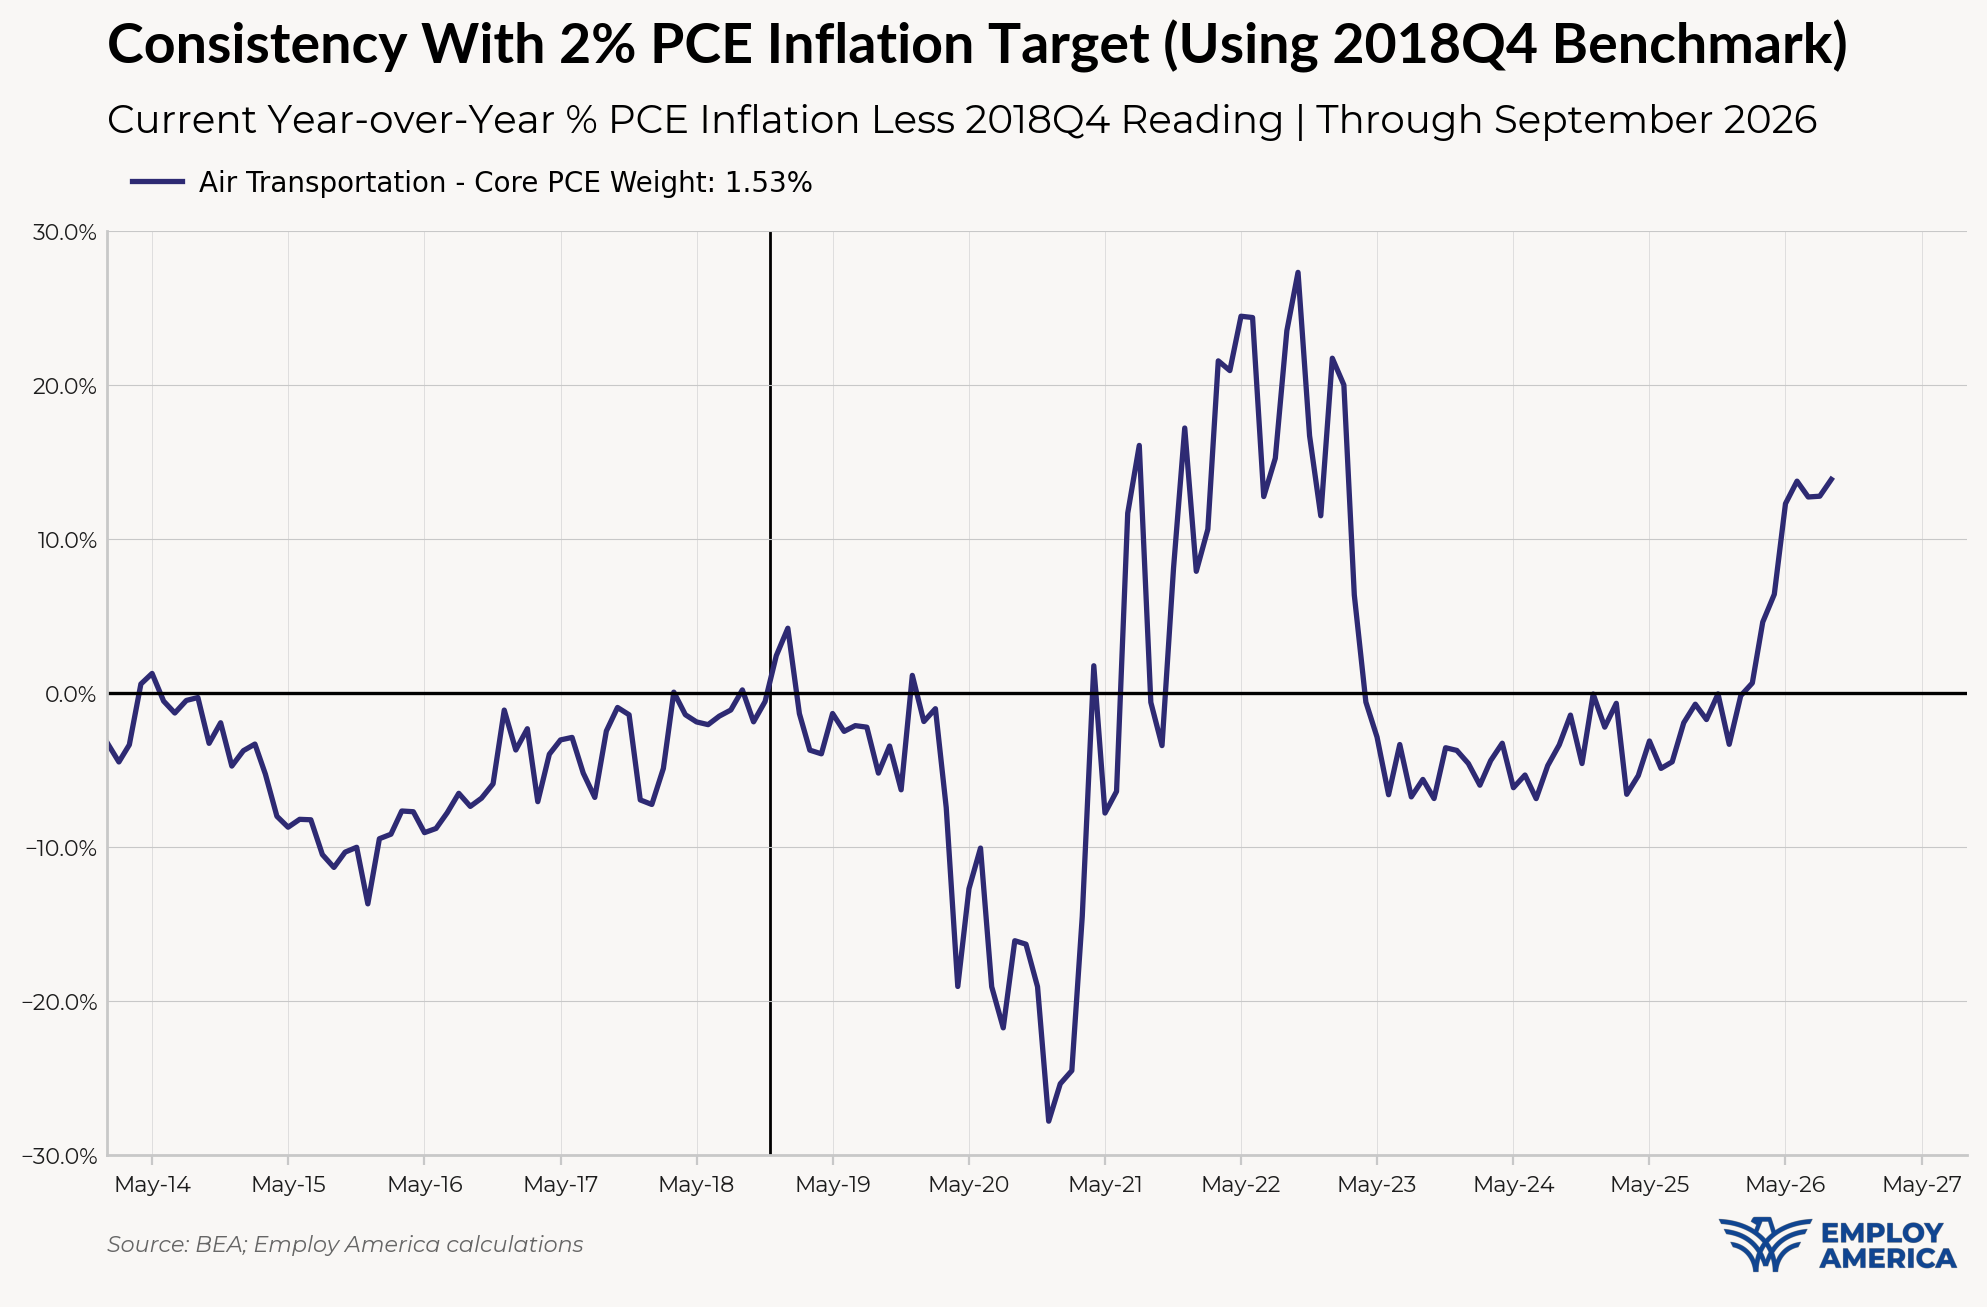
Today's upside stemmed from the airfares, while the rest of the PPI inputs into PCE were more benign. Today's release came with sizable downward revisions to the August airfares and hospitals data. We now anticipate the m/m August core PCE to be revised down by roughly 2bps to +23bps.
PCE Inflation Overshoots by PPI Component
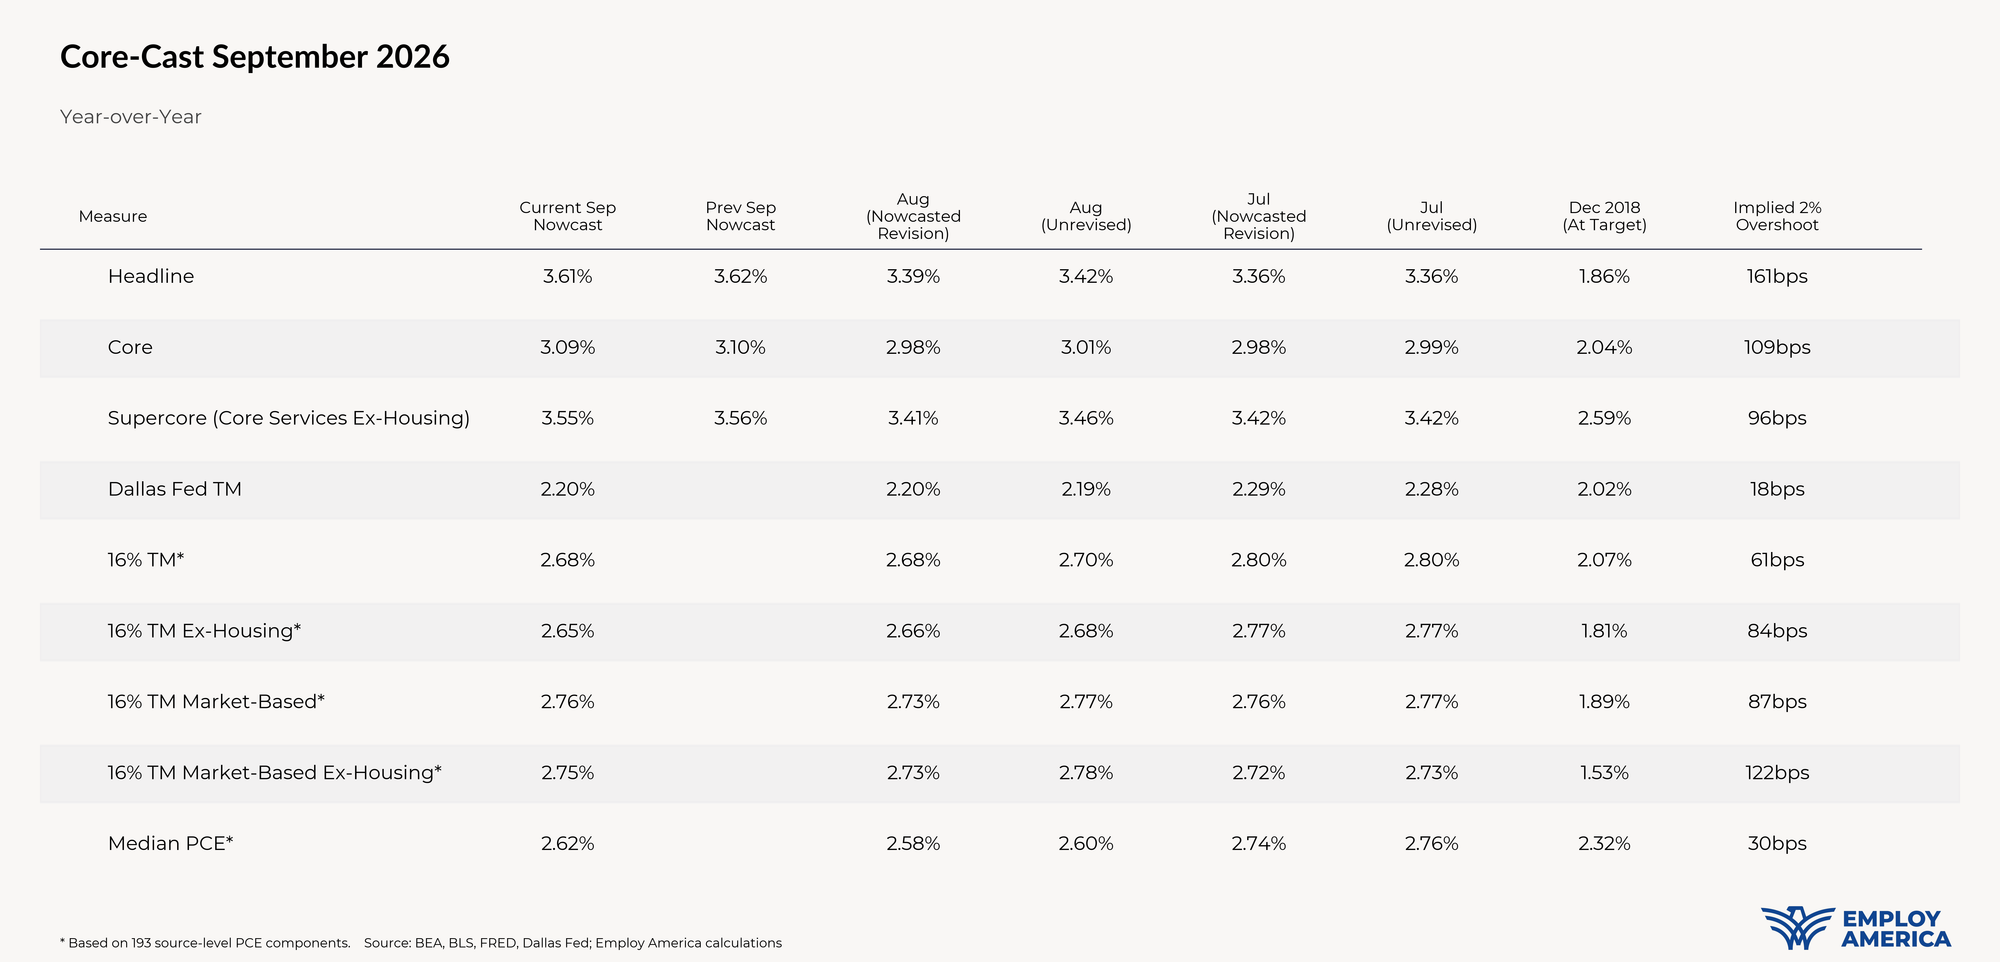
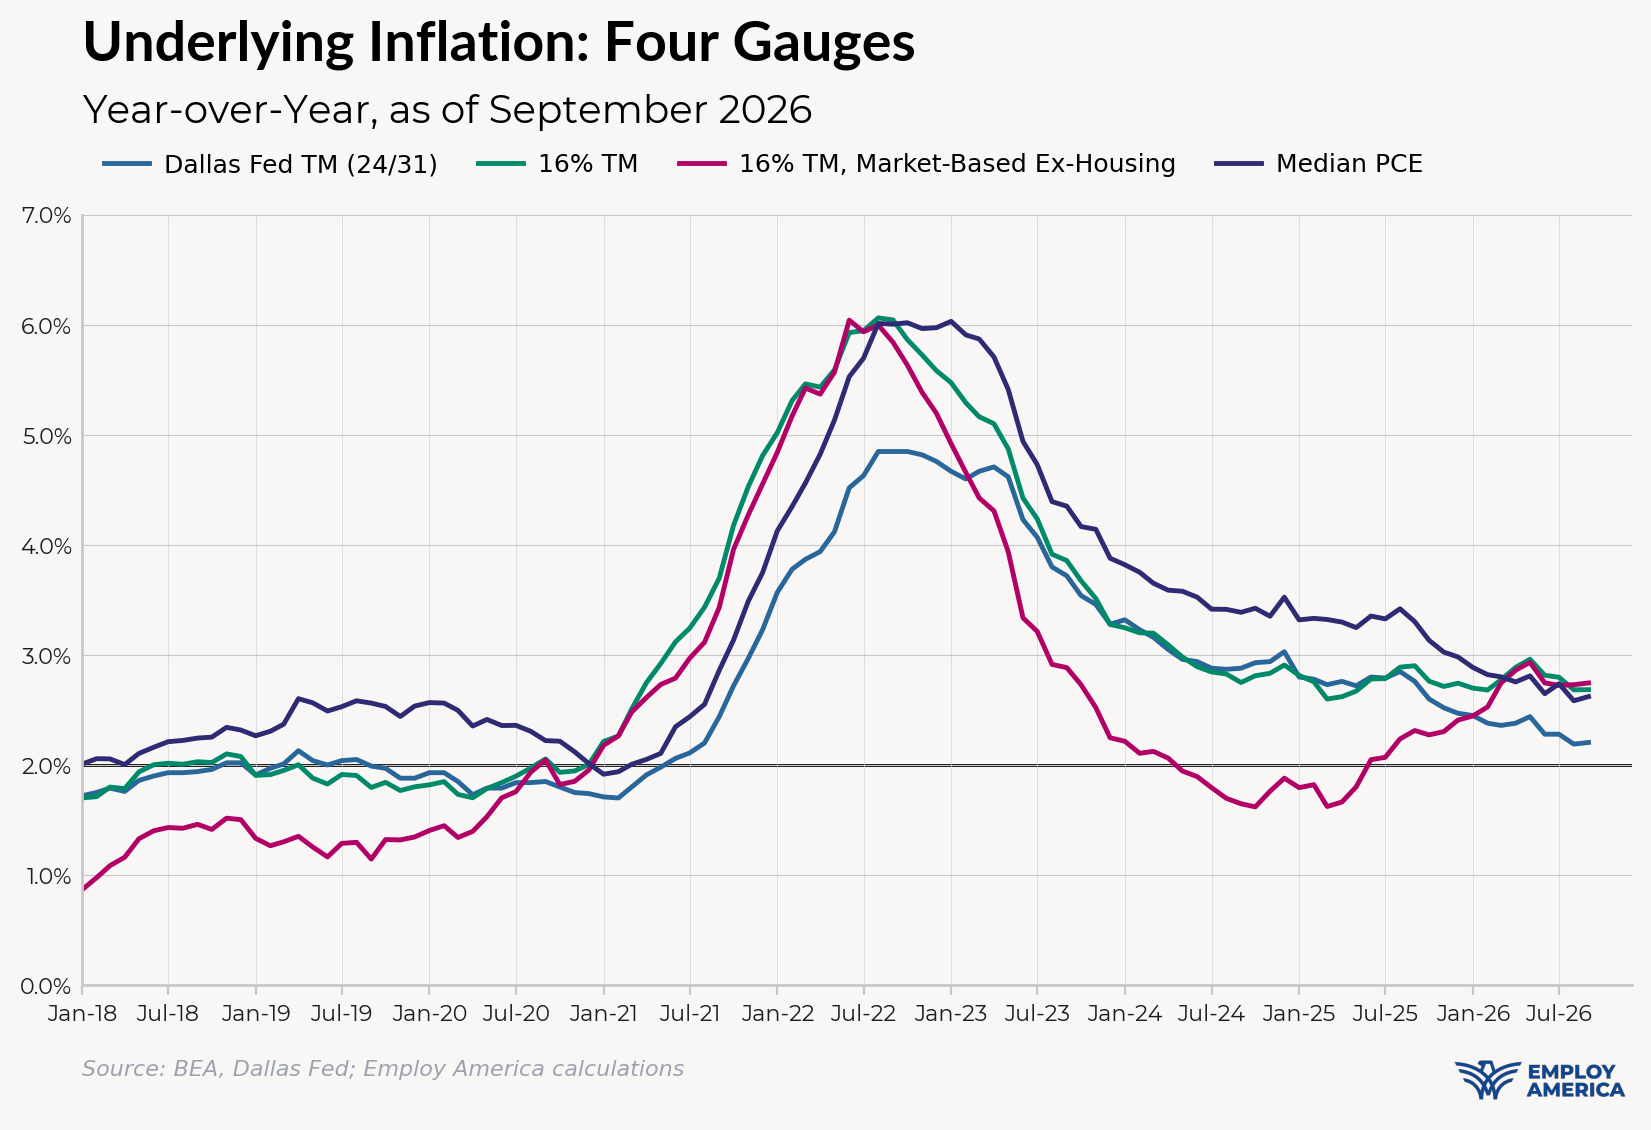
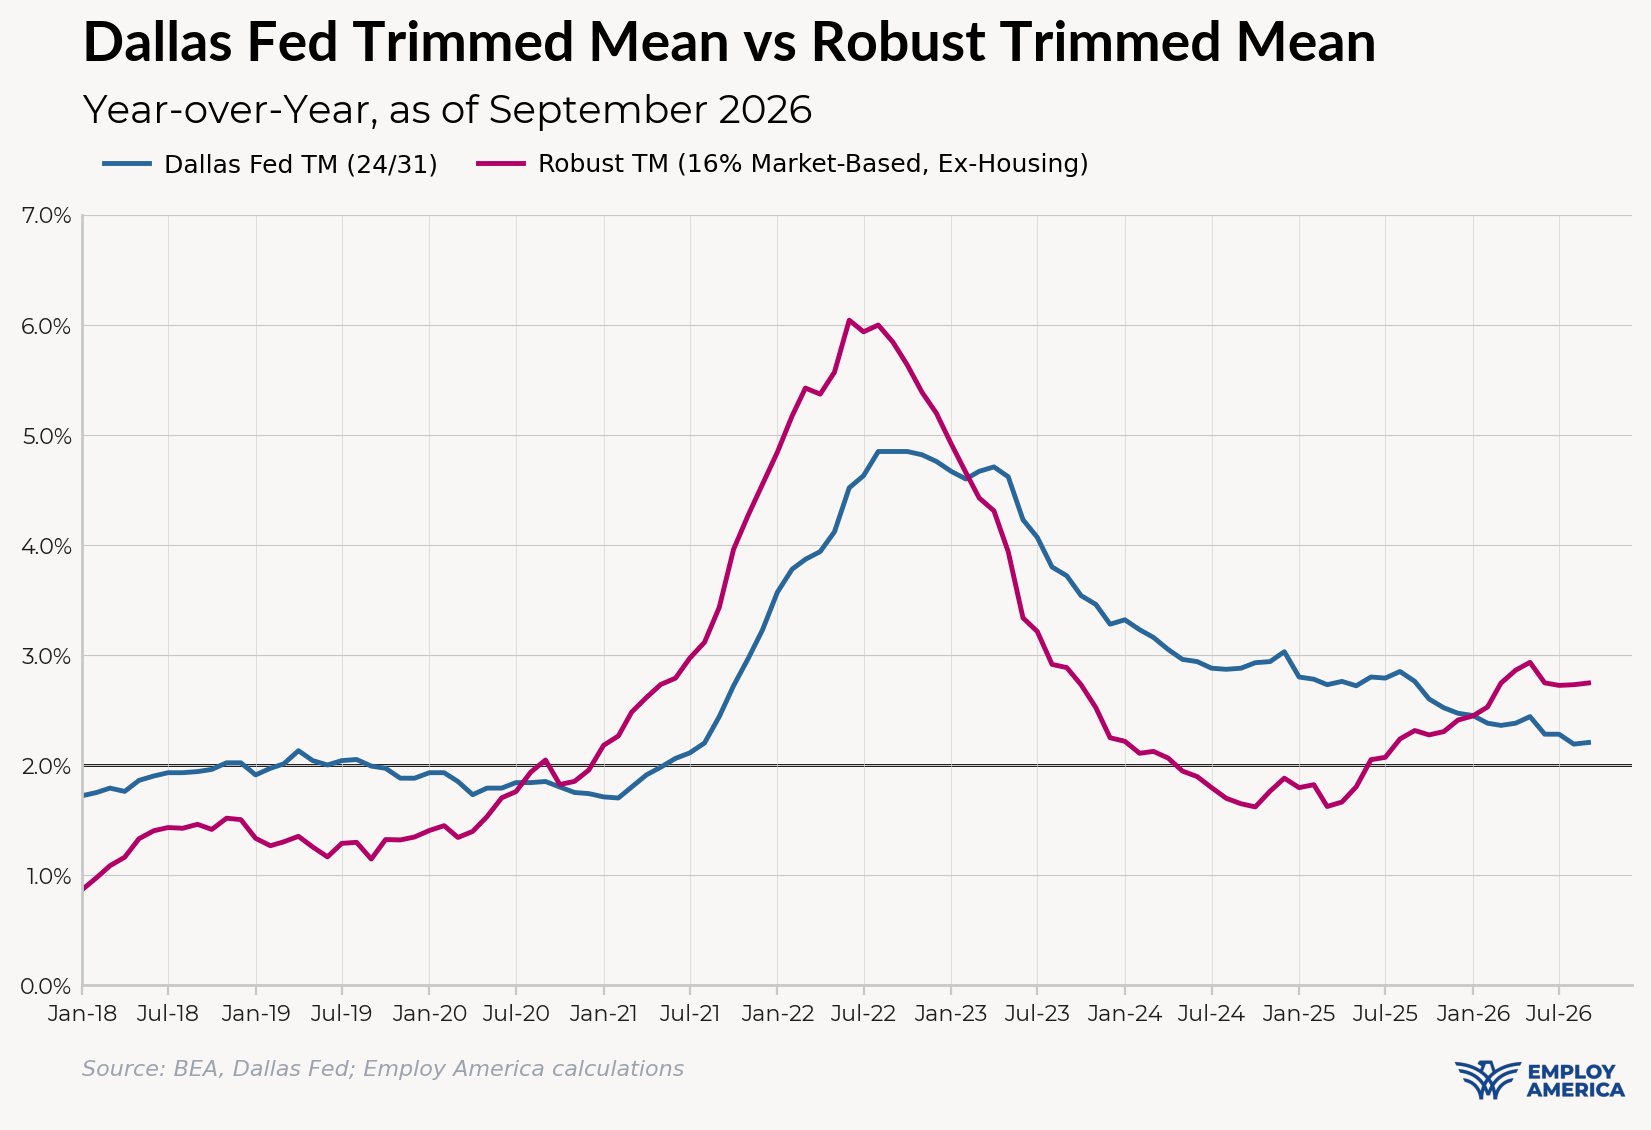
Trimmed Mean & Other Summary Gauges
With the exception of the Dallas Fed's gauge, trimmed mean measures are running below core PCE (2.65–2.76% vs 3.09%), but still above the Fed's 2% target. Our Robust Trimmed Mean gauge, which excludes housing (which lags market rents) and imputed prices not observed in market transactions, is projected to come in at 2.75% for September. On a m/m basis, we see Robust TM coming in at 27bps, up from 22bps (nowcasted revision) in August.
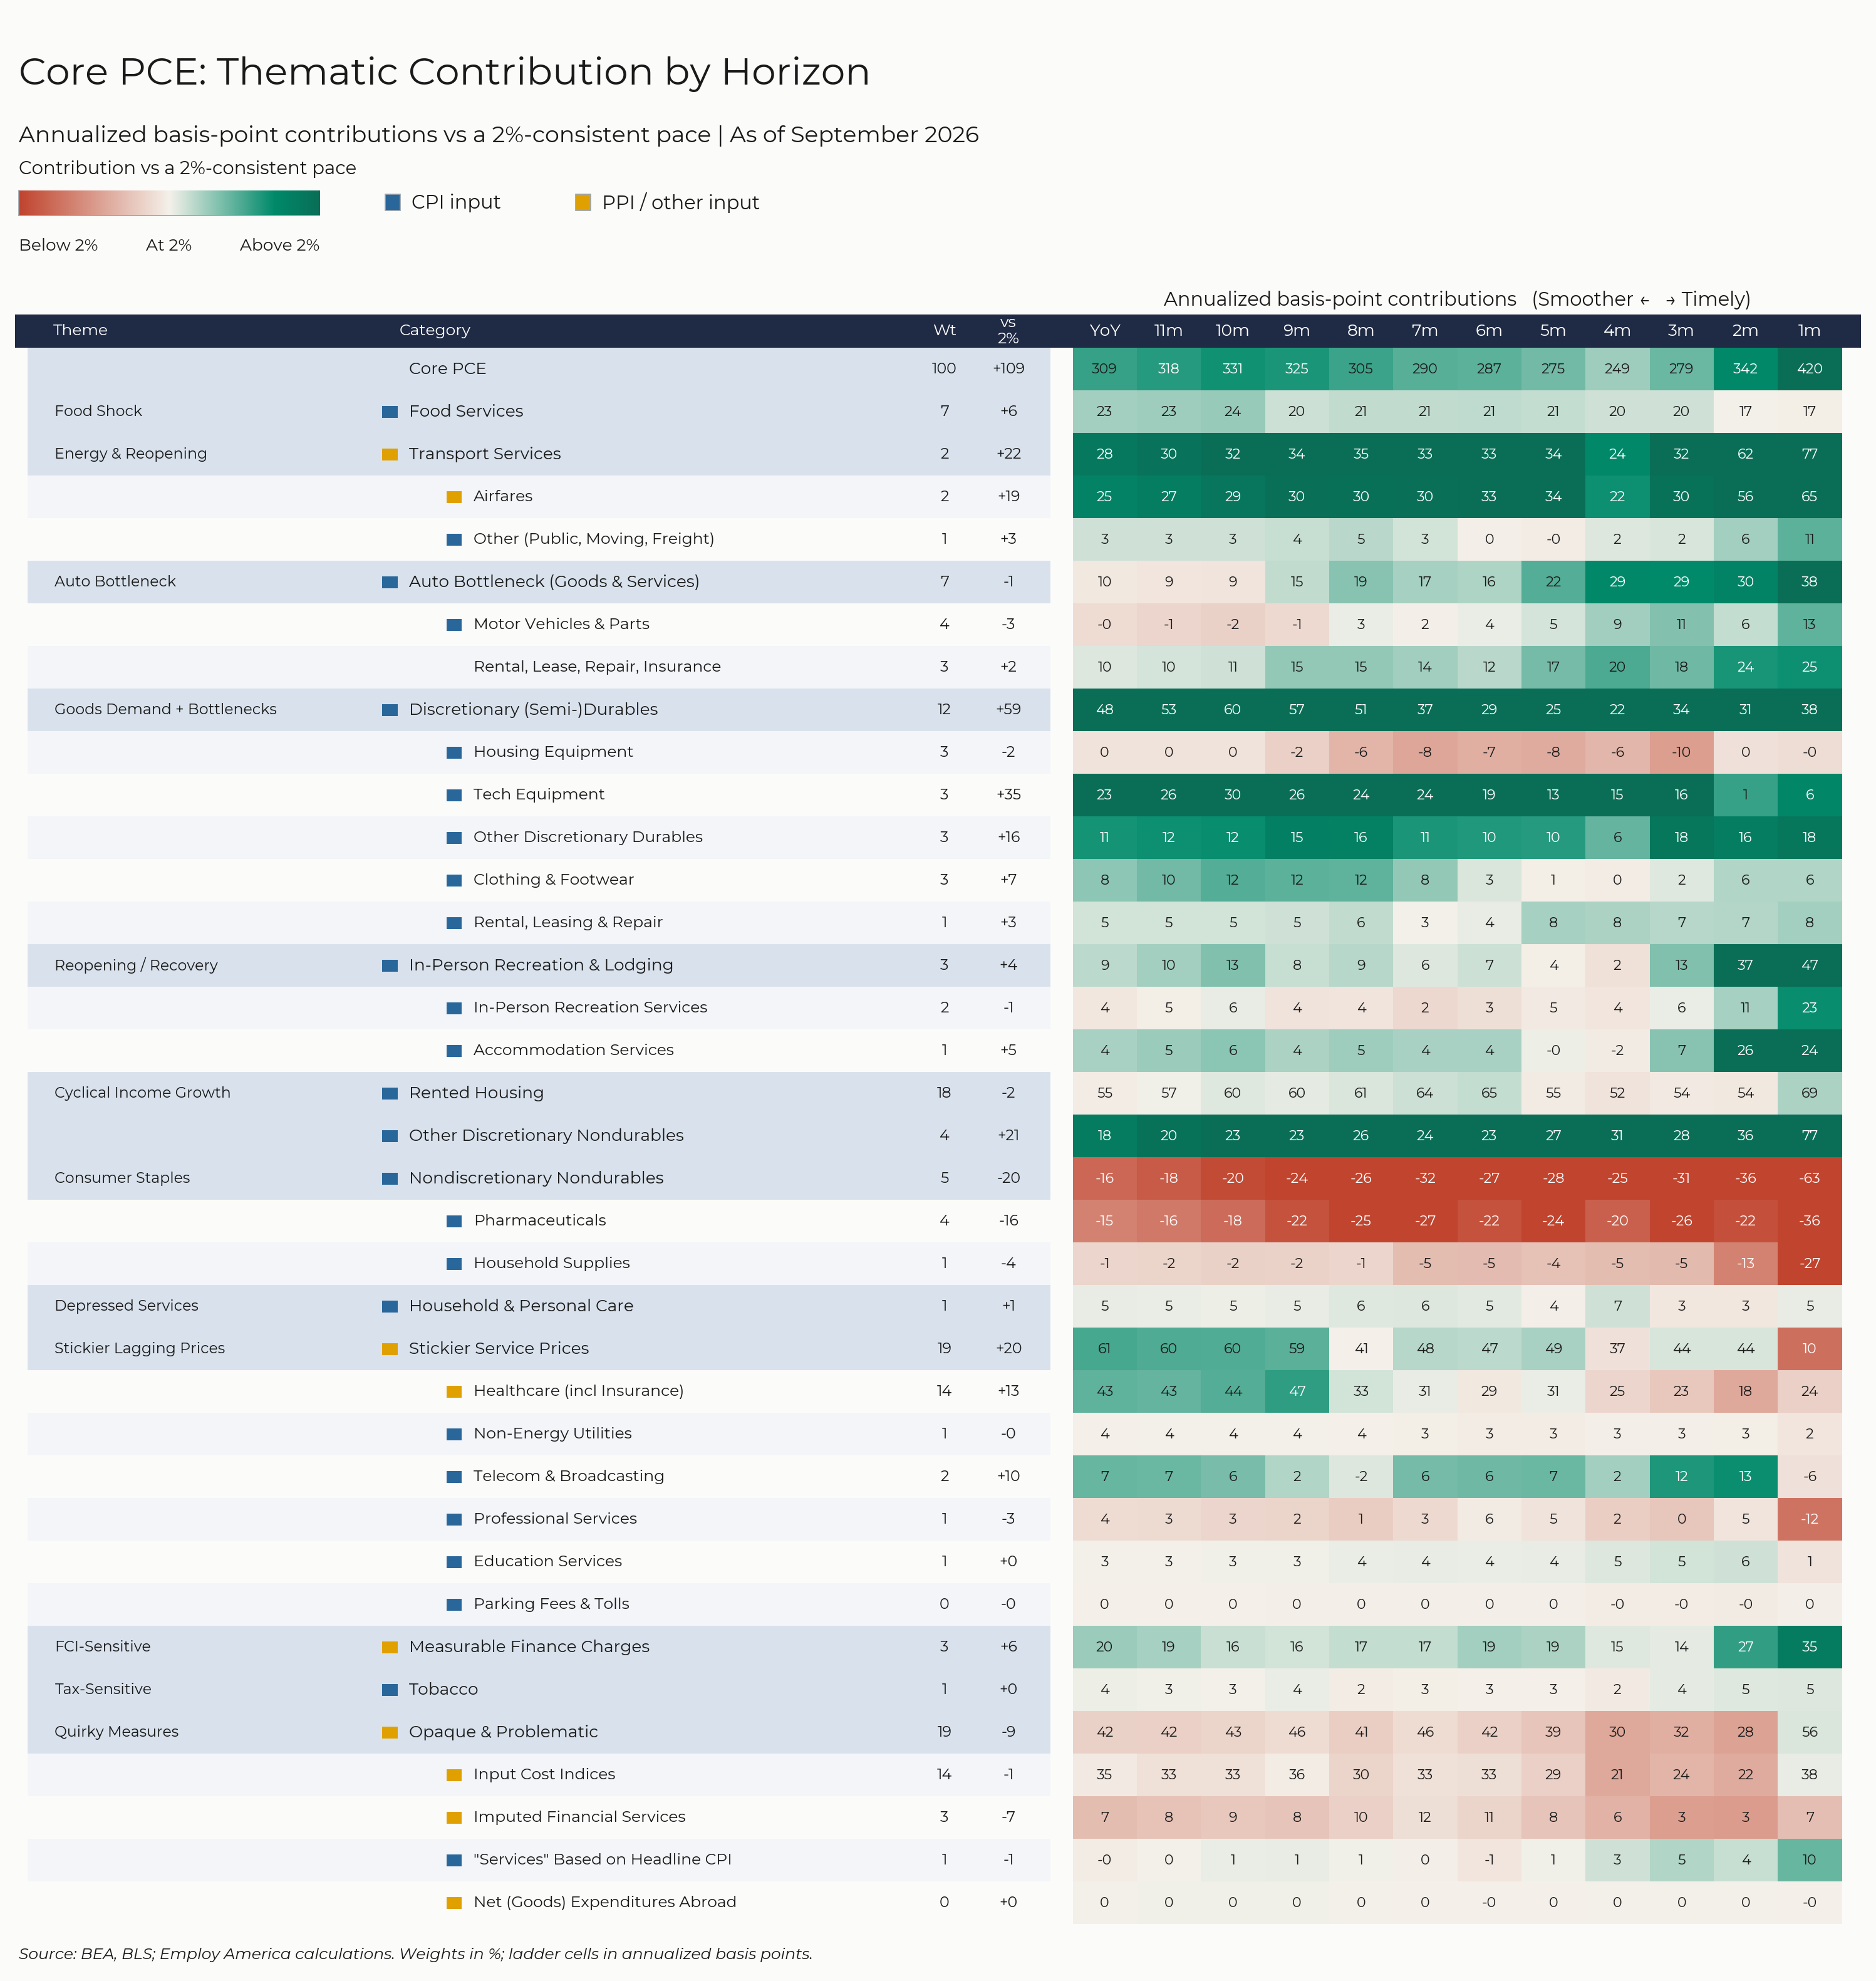
For the Detail-Oriented: Core PCE Heatmaps
Right now core PCE (PCE less food products and energy) is on track to run at a 3.09% year-over-year pace as of September, 109 basis points above the Fed's 2% inflation target for PCE.
Within this bucket, Tech equipment is adding 35 basis points.
Other discretionary nondurables are adding 21 basis points.
Airfares are adding 19 basis points.
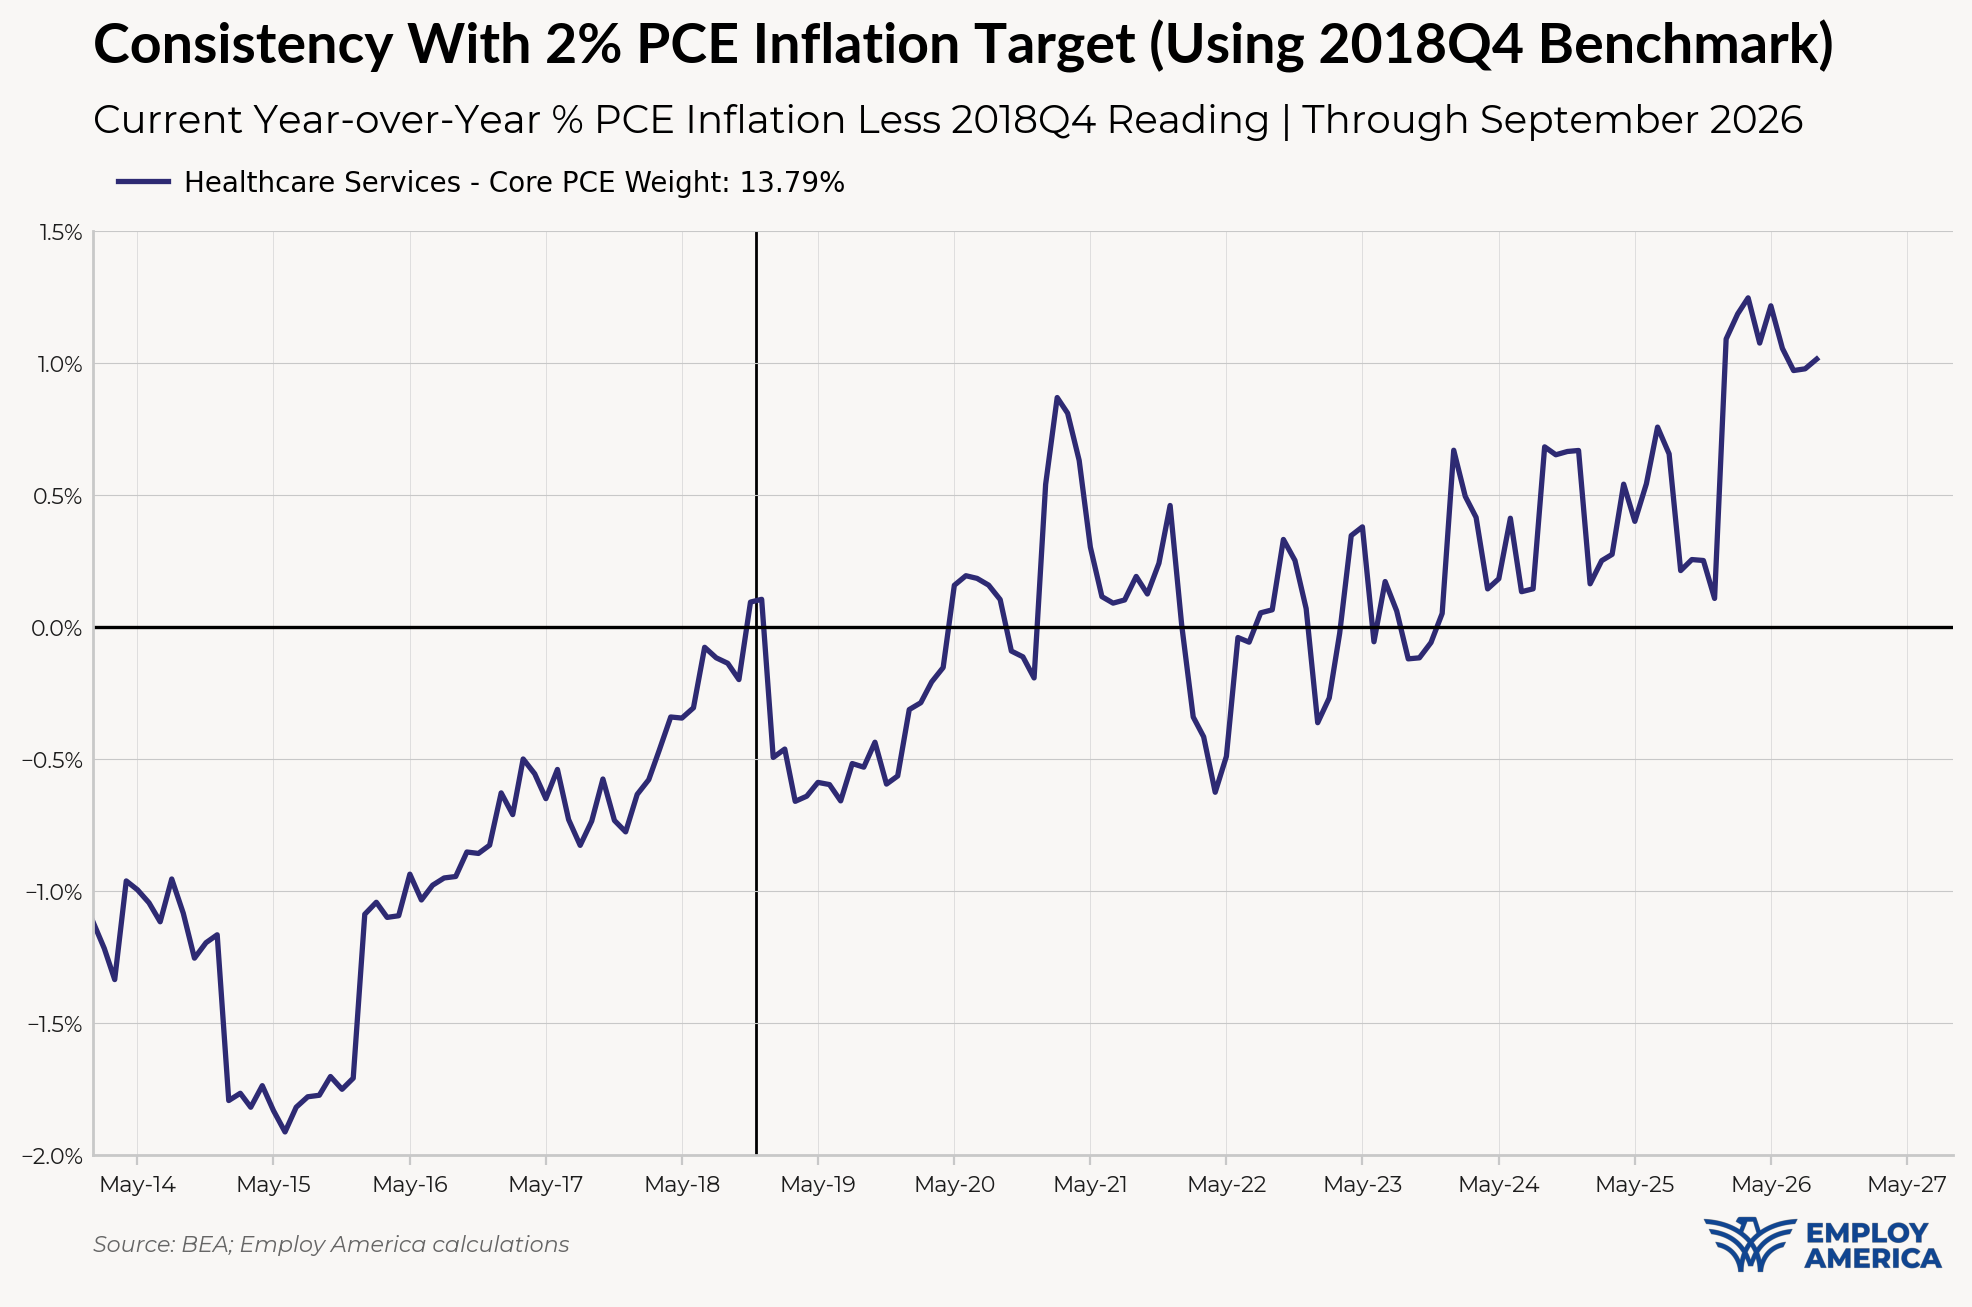
Healthcare services are adding 13 basis points.
Telecommunications and broadcasting are adding 10 basis points.
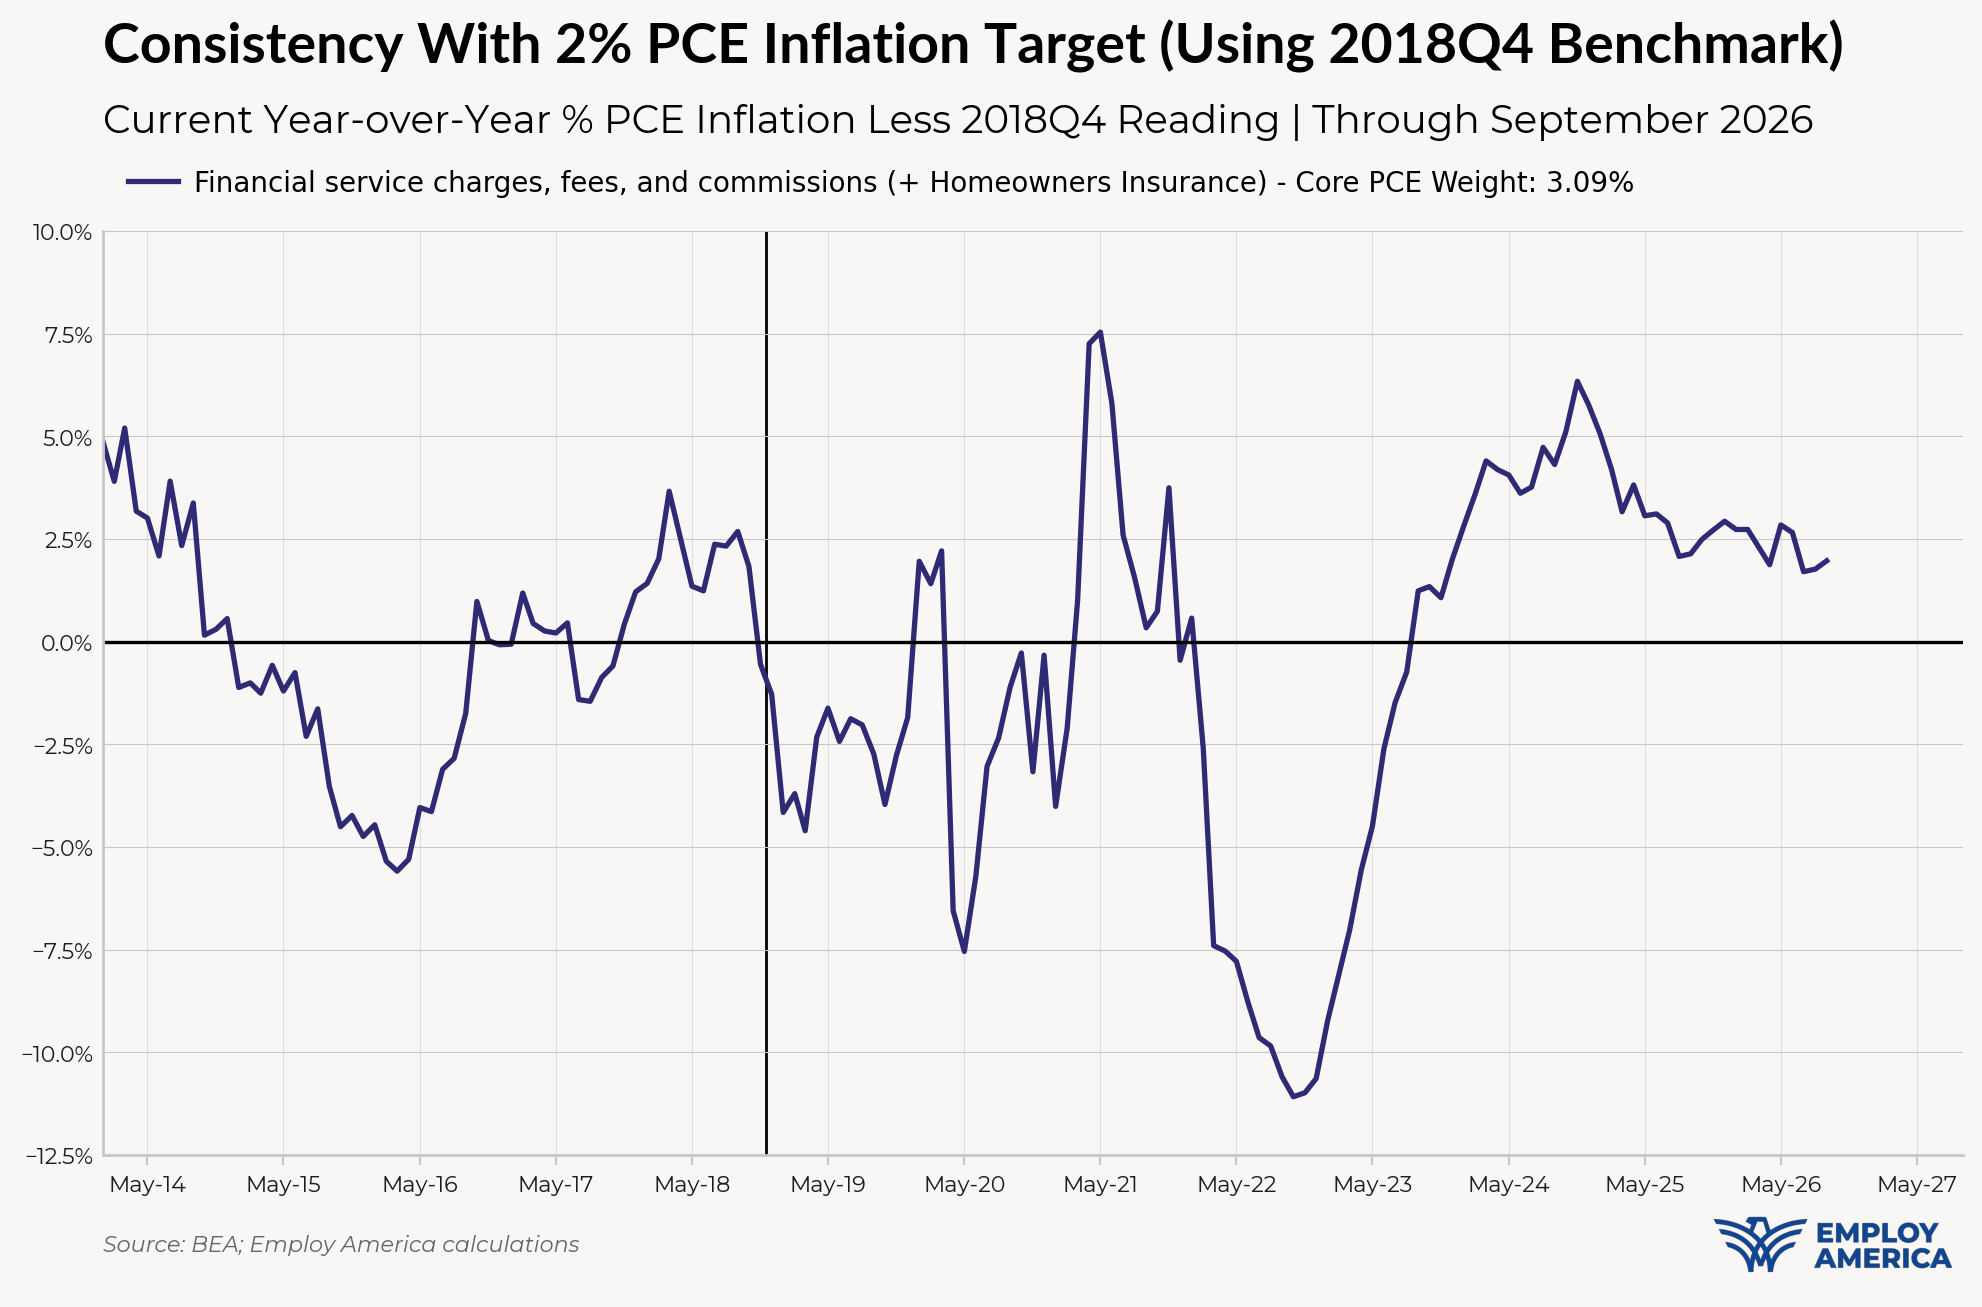
Measurable finance charges are adding 6 basis points.
Food services are adding 6 basis points to the overshoot.
The final heatmap below gives you a sense of the overshoot on shorter annualized run-rates. September monthly annualized core PCE is on track to run at a 4.20% annualized pace, a 220 basis point overshoot vs 2% target inflation.
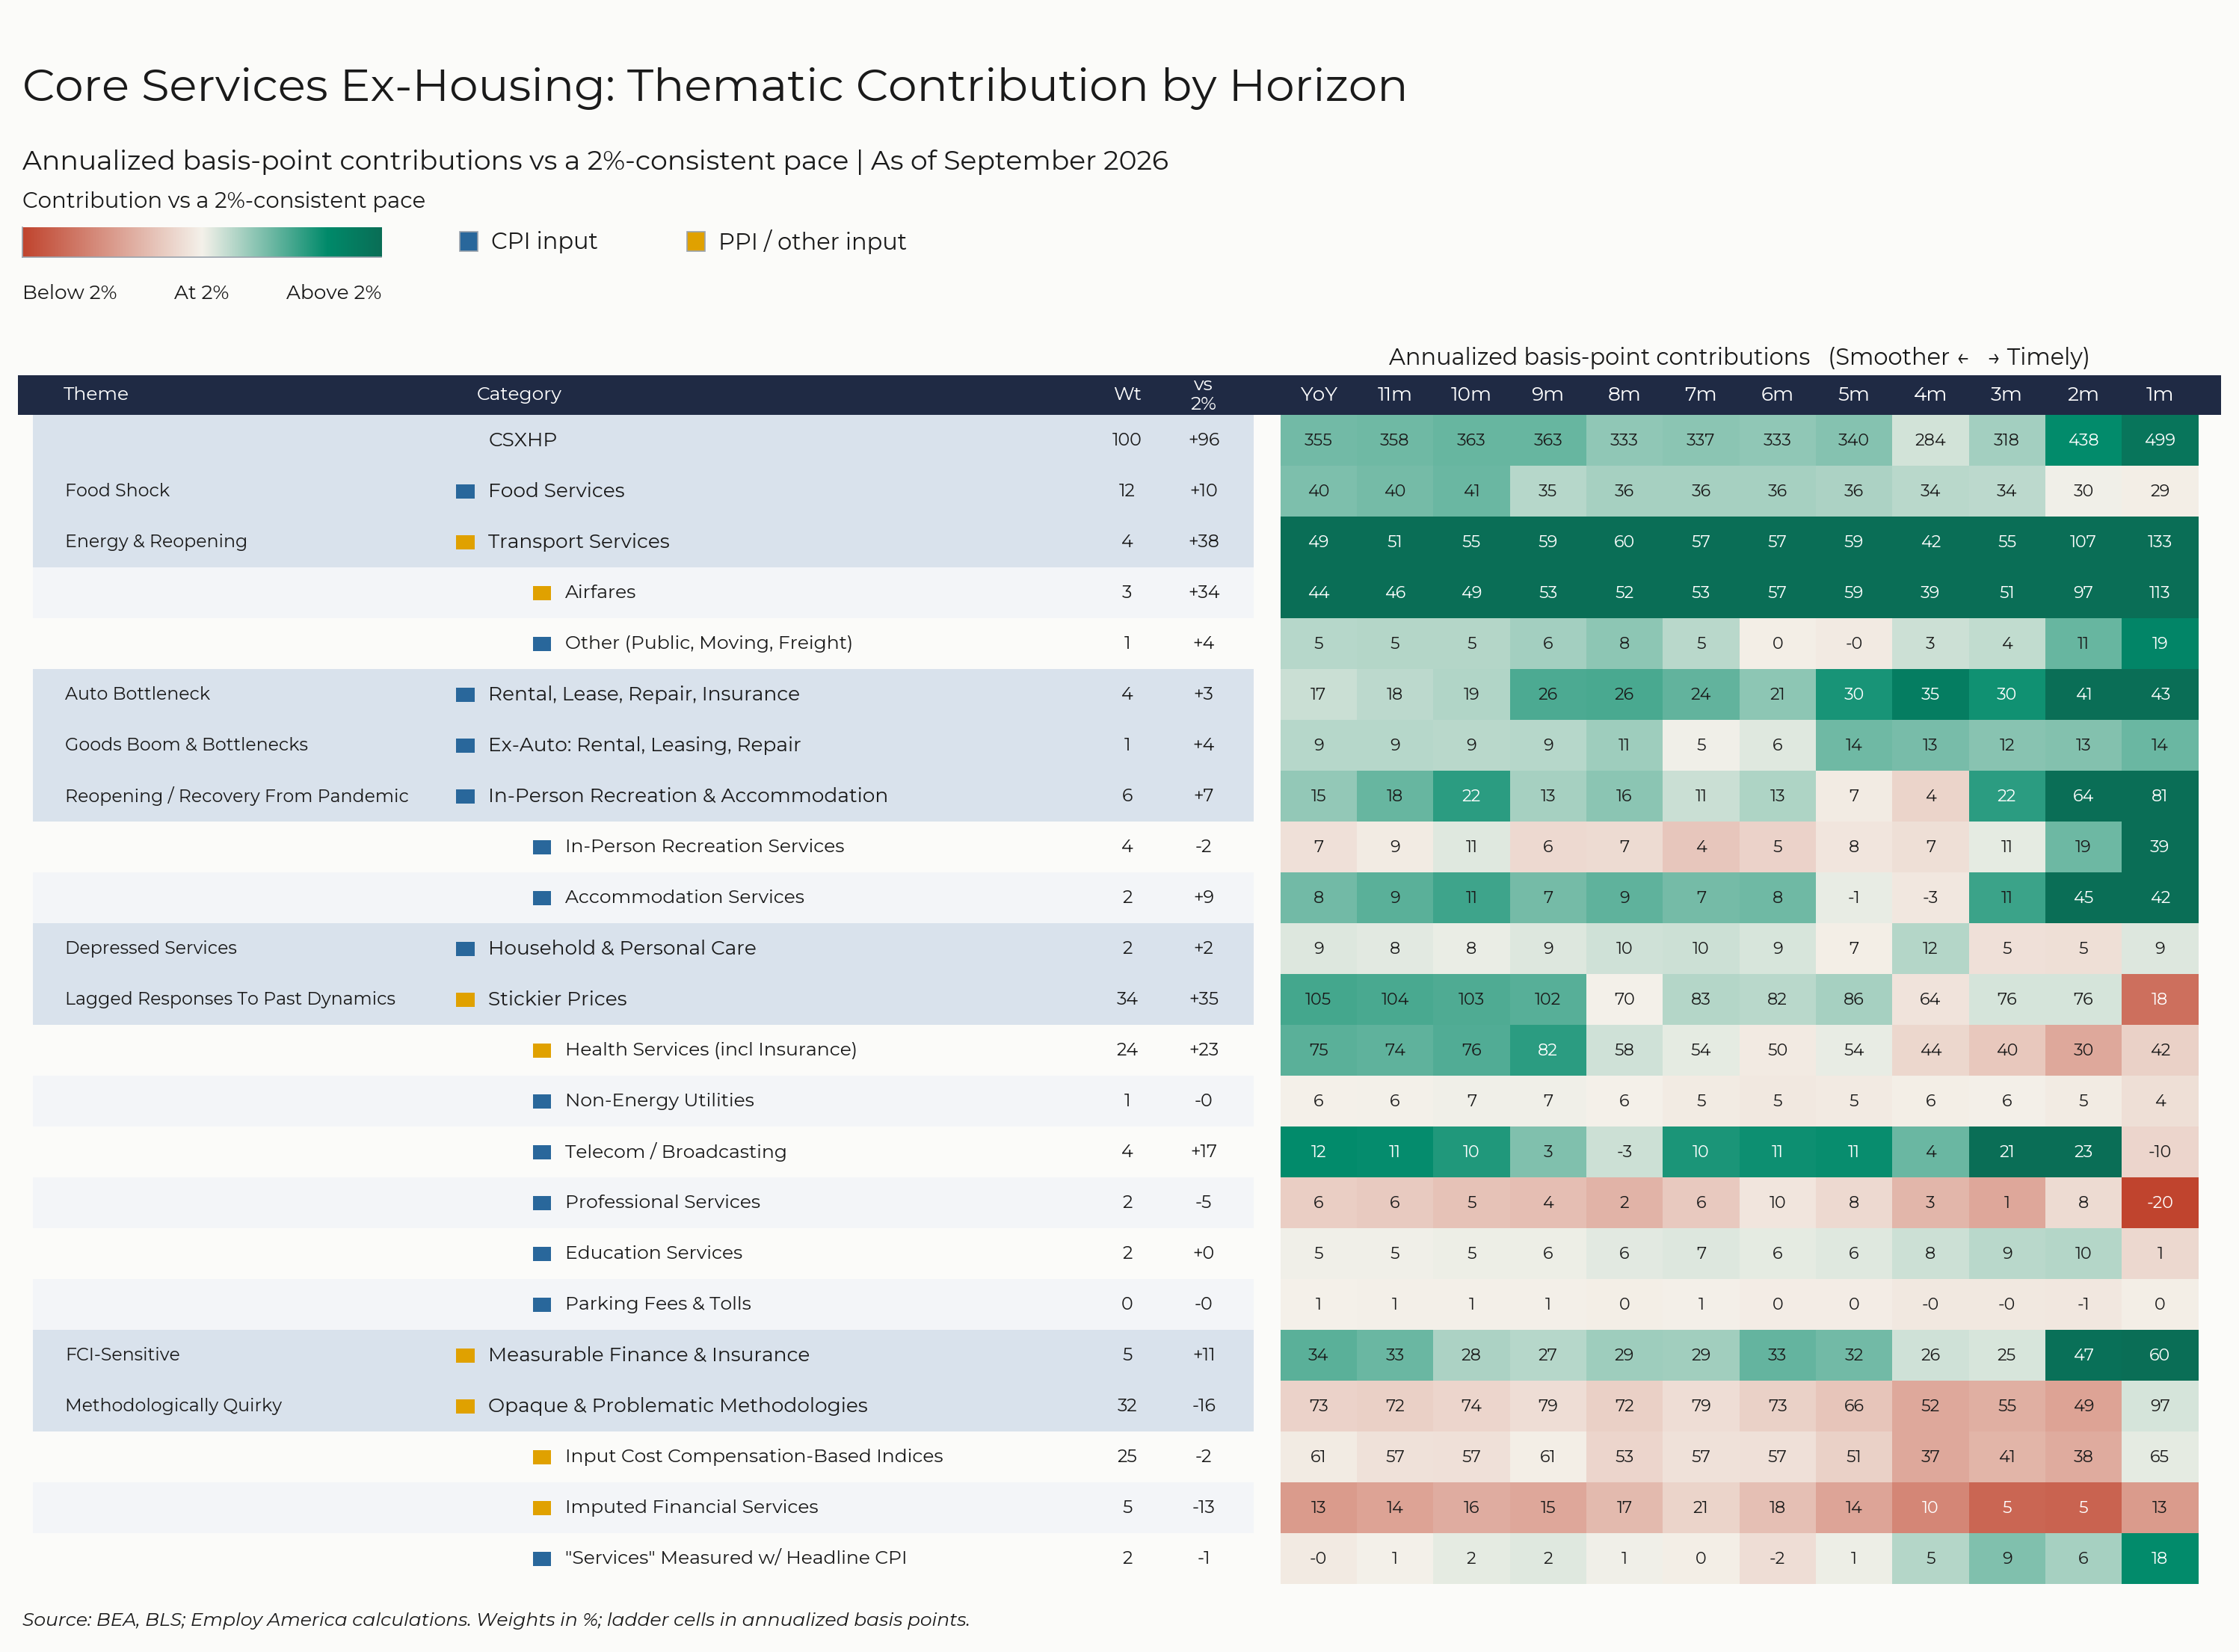
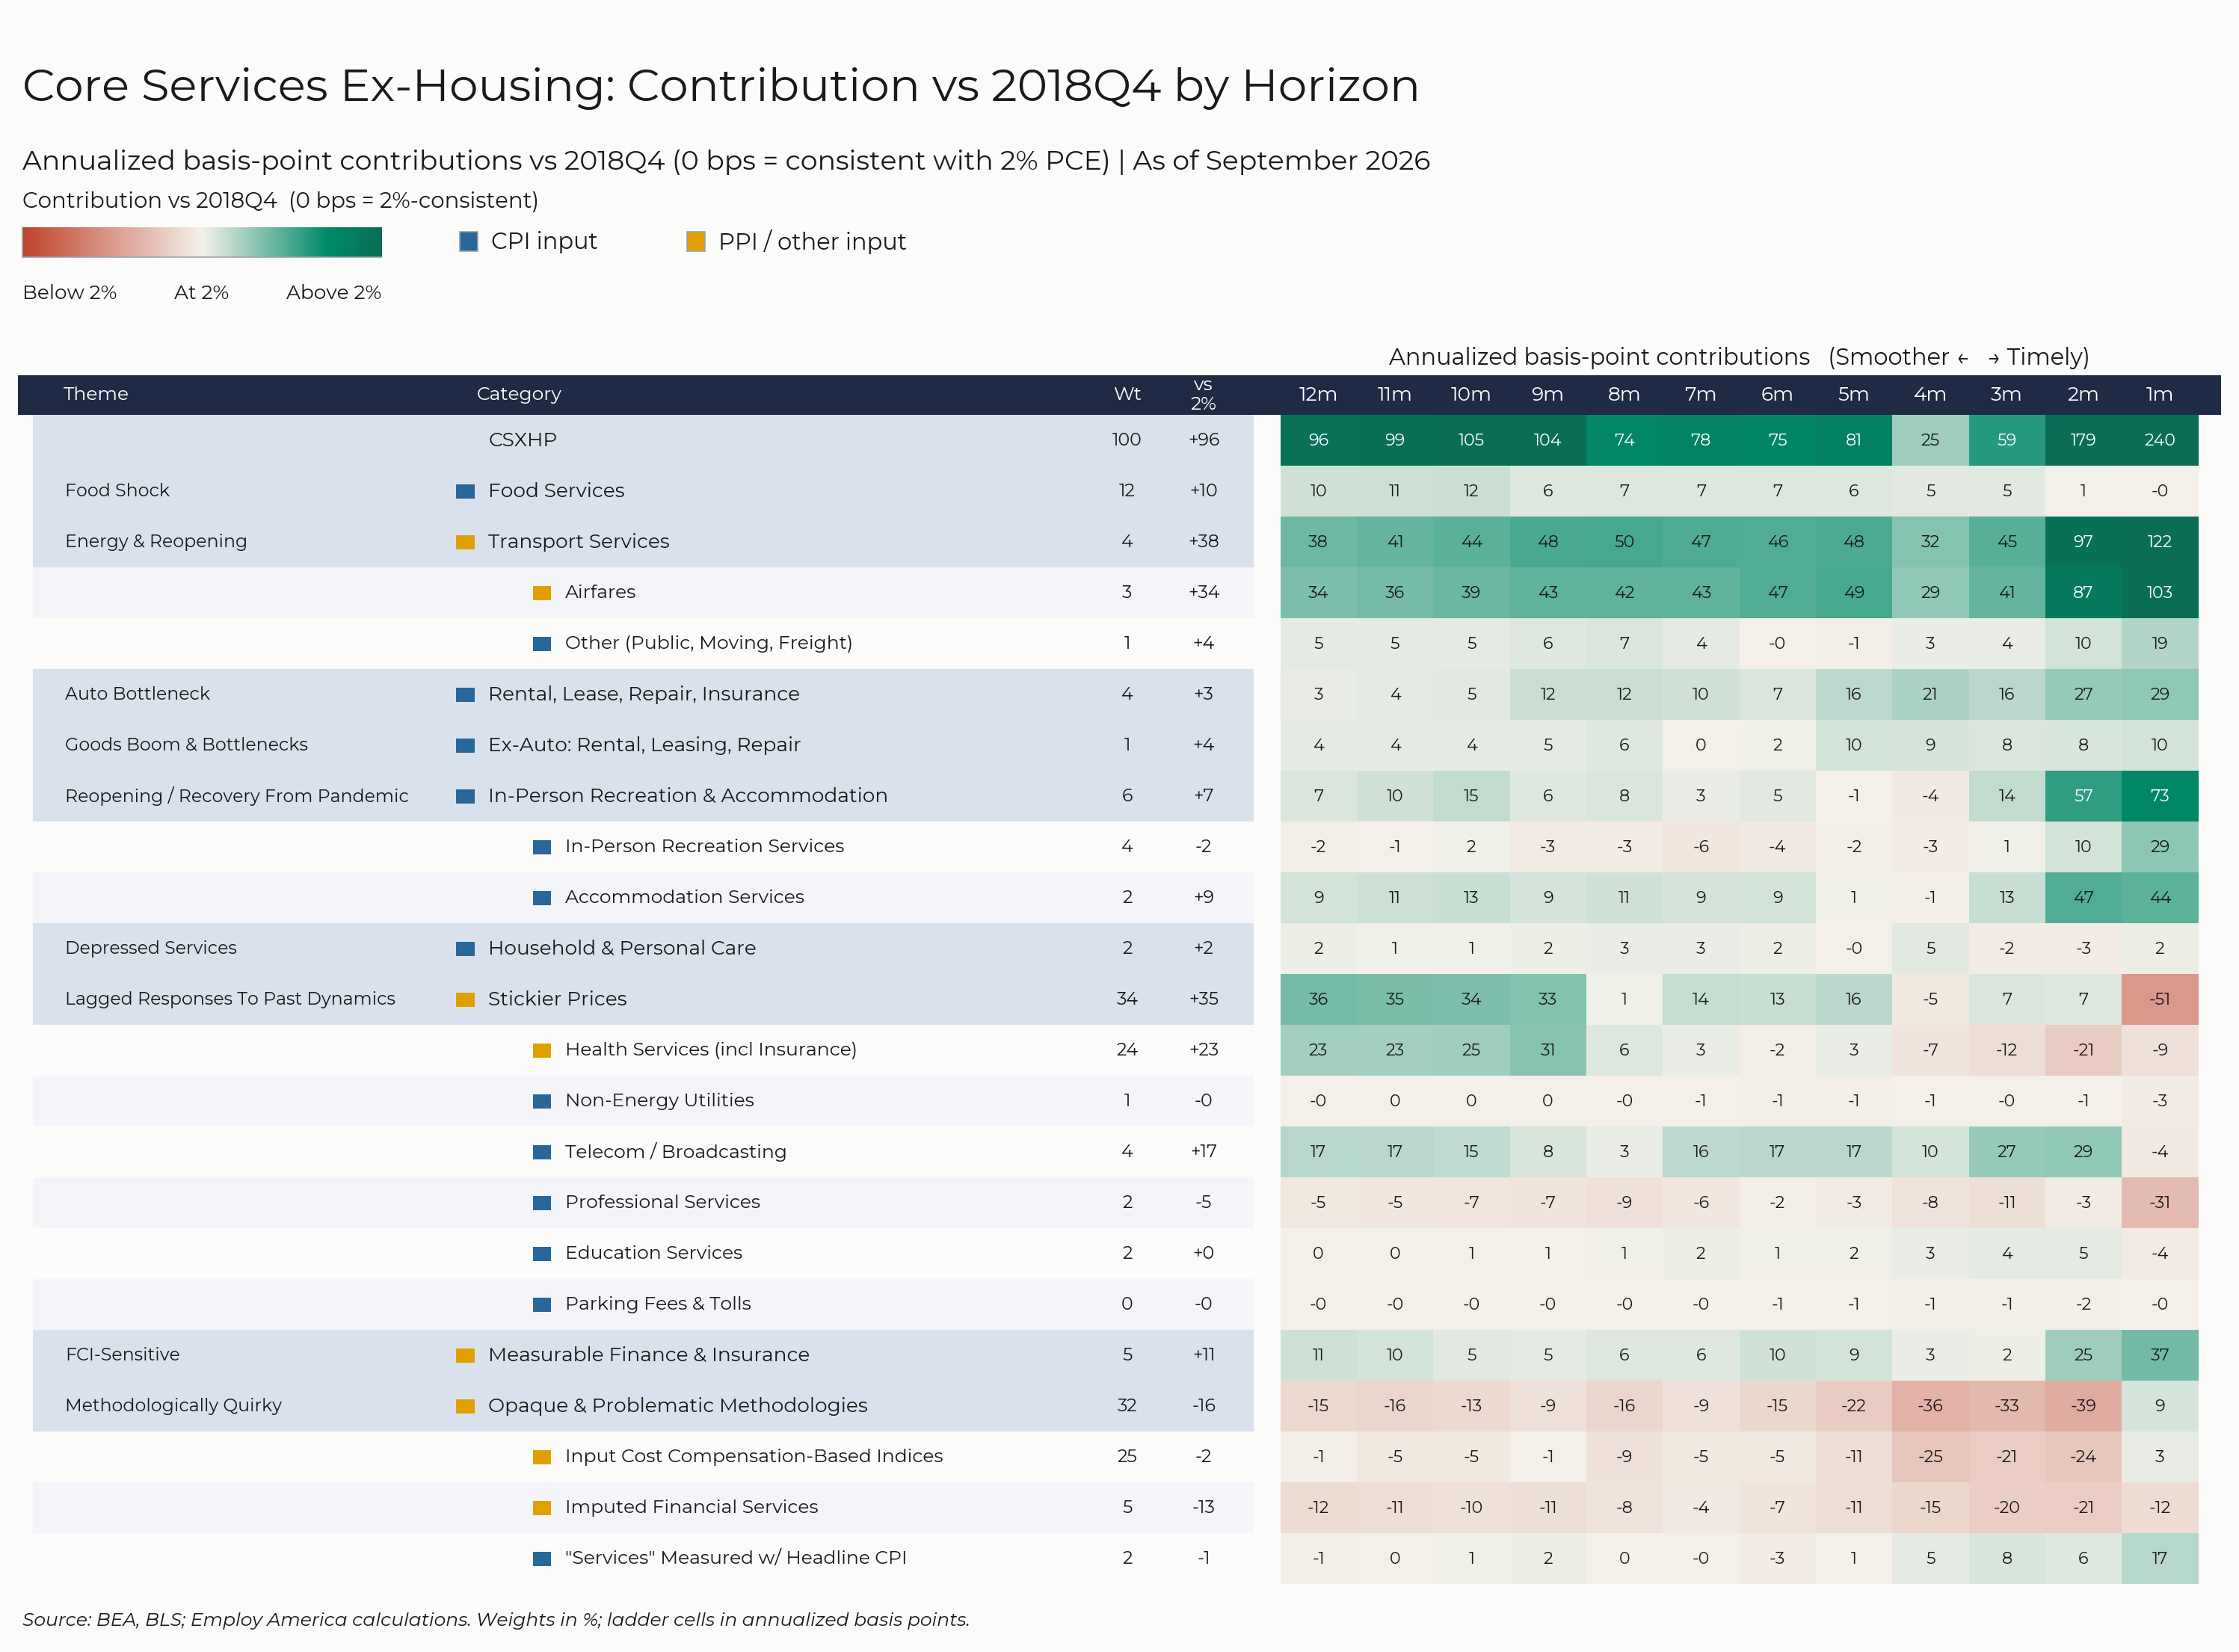
For the Detail-Oriented: Core Services Ex-Housing PCE Heatmaps
The September growth rate in "Core Services Ex-Housing" ('supercore') PCE is on track to run at a 3.55% year-over-year pace, a 96 basis point overshoot versus the ~2.59% run rate that coincided with ~2% headline and core PCE inflation.
September monthly supercore is on track to run at a 4.99% annualized rate, a 240 basis point annualized overshoot of what would be consistent with 2% headline and core PCE.
The link has been copied!
Your link has expired. Please request a new one.
Your link has expired. Please request a new one.
Your link has expired. Please request a new one.
Great! You've successfully signed up.
Great! You've successfully signed up.
Welcome back! You've successfully signed in.
Success! You now have access to additional content.