Content Paint

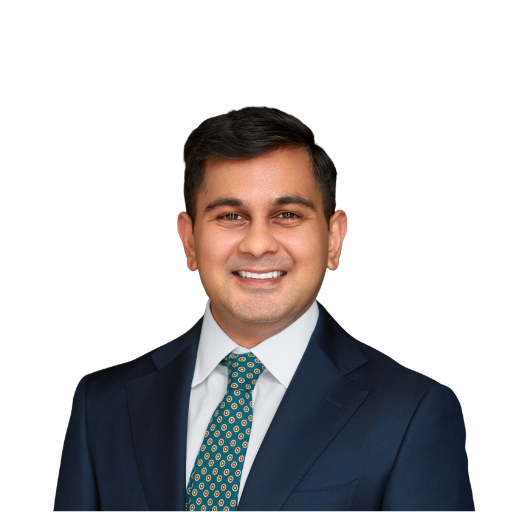
Vikas Patel

Program Manager vikas@employamerica.org

About

Vikas’s role as Program Manager at Employ America encompasses a wide scope of work, coordinating across program, communications, fundraising, and earned revenue activities to ensure our work is mission-focused, high quality, useful, and sustainable. He manages our MacroSuite premium research service, and collaborates with our economists and policy analysts to plan, publish, and promote our work strategically.

Holding a Bachelor of Arts in Economics and Political Science from Indiana University Bloomington, Vikas was previously a political campaign consultant and strategist, serving as Policy Director and Deputy Chief of Staff for congressional campaigns in New York City.

Based in New York, NY, Vikas also spends significant time in Mexico City. When he’s not working, he enjoys cooking, playing golf, going to the gym, and watching sports.
Vikas Patel's Work

59 Posts
Vikas Patel

The BEA will make three changes to how it measures price change for portfolio management, computer software and accessories, and legal services in PCE. On net, these changes would likely lower current PCE inflation readings.

Composite Activity held at +1.1σ since June 18. 1Q2026 GDP was revised up to +2.1%, but consumption was revised down to +0.5% and private final demand to +1.7%. Mfg restocking still strong, AI capex anchors the cycle; regional Fed hiring broadened. 2-3 hikes from October remains base case.

Our month-over-month May Core PCE nowcast of 0.40% came in 8 basis points above the realized 0.32% reading. Our error stemmed from Supercore (core services ex-housing) – the realized readings for nowcasts for core goods and housing came right in line with our final nowcasts for

Composite Activity rose +0.1σ to +1.1σ since June 12 — Mfg restocking still strong, AI capex anchors the cycle. Iran MOU cuts left-tail risk; inflation risks still linger. 2 hikes from October remains base case, 3 shouldn't be ruled out.

Composite Activity holds steady at +1.0σ since June 5 update ahead of data-packed weak — Mfg restocking intact, AI capex still anchors the cycle, Hormuz risk tilts inflationary rather than recessionary. 2 hikes starting in October remains the base case, 3 shouldn't be ruled out.

Composite Activity +0.21σ since May 29 — Labor + Services drove the pick-up. Mfg restocking intact, AI capex still anchors the cycle, Hormuz risk tilts inflationary rather than recessionary. October rate hike + 1 additional rate hike by 2027H1 is the new base case.

First edition under a refreshed monitor. Composite Activity +0.11σ since May 6 — broad pickup ex-housing. Manufacturing restocking continues, AI-boom continues to anchor the cycle, Hormuz risk tilts inflationary rather than recessionary. 2026Q4 rate hike remains the base case.

Your link has expired. Please request a new one.
Great! You've successfully signed up.
Welcome back! You've successfully signed in.
Success! You now have access to additional content.